
Cosmos Health CEO Greg Siokas Issues Letter to Shareholders Highlighting Record 2026 Revenue, U.S. Subscription Growth and Global Expansion
The U.S. subscription business is expected to contribute approximately $10.5 million in fourth-quarter gross profit.
Sentiment and the balance of points
Rhea-AI Sentiment reads the wording of the document, how positive or negative its language is on a 1 to 5 scale. The balance of points shown with the takes weighs what the document actually discloses, so the two can disagree, for example when a trial that missed its main goal is described in upbeat language.
Rhea-AI Summary
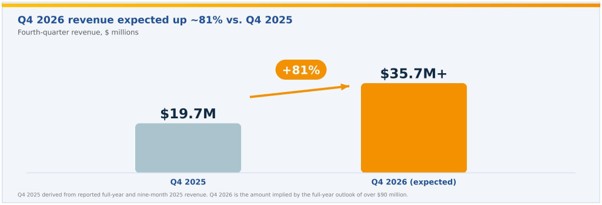
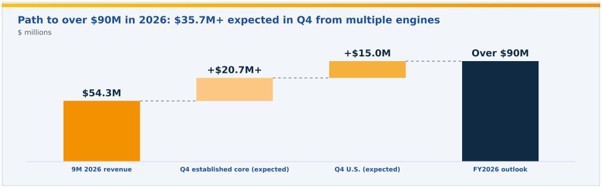
Cosmos Health (COSM) reported preliminary nine-month revenue of approximately $54.3 million and reaffirmed its expectation for record full-year revenue. Revenue rose 19% year over year; the company expects 2026 revenue to surpass $90 million, implying fourth-quarter revenue of approximately $35.7 million or more.
Its U.S. business had 8,940 active subscriptions as of October 19. Cosmos expects approximately $15 million in fourth-quarter U.S. revenue at an approximately 70% gross margin, supported by a significantly expanded marketing budget. Cana's contract manufacturing pipeline exceeds 32.7 million units, with more than $20 million in implied revenue over the agreements' lives, subject to execution. Total liabilities fell 13.3% between December 2025 and June 2026. Cosmos targets a 35.5% gross margin by fiscal 2029, versus 12.1% in fiscal 2025, and has a non-binding acquisition letter of intent for a Greek pharmacy distribution network.
How this balance works
Rhea-AI gives every point it takes from this document a weight. Minor counts 1, Moderate 3 and Major 9, so one Major point outweighs several Minor ones. The bar adds up the weights on each side, and when neither side holds more than 65% of the total the balance reads Mixed.
It reads the document as published, with the same rules for every company, and it does not look at what the market expected or at how the stock traded, so a point can be objectively good on a day the stock falls.
Rhea-AI Sentiment measures something else, the tone of the wording.
Hollow bars mark forward-looking points. How the balance works
Positive
- Major point. Forward-looking: it has not happened yet and may not happen.2026 revenue outlook remains above $90 million, implying approximately $35.7 million or more in fourth-quarter revenue.
- Major point. Forward-looking: it has not happened yet and may not happen.Manufacturing agreements imply more than $20 million revenue and $18 million gross profit over their lives. 61% of market cap
- Moderate pointPreliminary nine-month revenue reached approximately $54.3 million, up 19% year over year and 35% versus 2024.
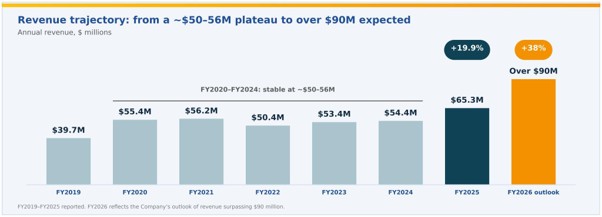
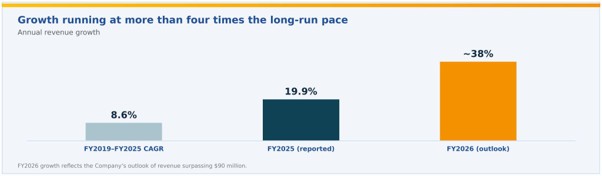
- Moderate pointFiscal 2025 revenue reached a record $65.3 million, with growth accelerating to 19.9%.
- Moderate pointFiscal 2025 gross profit rose 83% to $7.9 million; gross margin expanded 418 basis points to 12.1%.
- Moderate point. Forward-looking: it has not happened yet and may not happen.Gross margin target is 35.5% by fiscal 2029, versus 12.1% in fiscal 2025.
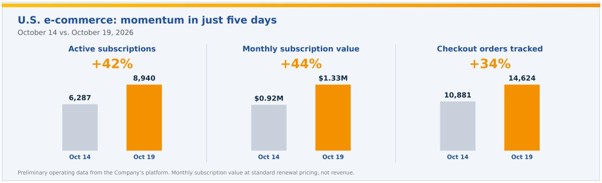
- Moderate pointActive U.S. subscriptions reached 8,940 on October 19, up 42% from 6,287 five days earlier.
- Moderate point. Forward-looking: it has not happened yet and may not happen.Year-end U.S. targets exceed 40,000 active subscriptions and $200,000 daily sales, versus $60,000 at the quarter's start.
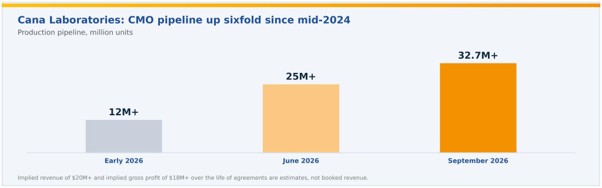
- Moderate pointCana's manufacturing pipeline exceeds 32.7 million units, up sixfold since mid-2024, across 11 therapeutic categories.
- Moderate point. Forward-looking: it has not happened yet and may not happen.Cana's full-capacity potential exceeds $10 million recurring annual gross profit, management believes.
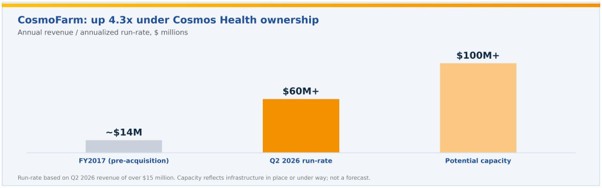
- Moderate pointCosmoFarm second-quarter revenue exceeded $15 million, approximately 4.3 times its roughly $14 million fiscal 2017 annual revenue.
- Moderate point. Forward-looking: it has not happened yet and may not happen.CosmoFarm's automated capacity could support more than $100 million annual revenue over time, the company believes.
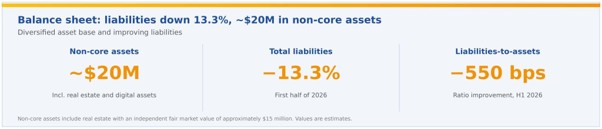
- Moderate pointTotal liabilities fell 13.3% between December 31, 2025 and June 30, 2026.
15 minor points
- Minor pointThird-quarter revenue reached approximately $17.4 million, a third-quarter record and up 40% versus 2024.
- Minor pointFirst-half revenue increased approximately 30% year over year; first-quarter growth was 31% and second-quarter growth was 29%.
- Minor pointMonthly subscription value at standard renewal pricing reached $1,325,338, up 44% over the same five days.
- Minor pointU.S. online checkout orders reached 14,624, up 34% over the same five days.
- Minor pointSubscription adoption reached 65.2% of checkout orders since platform inception and more than 85% of recent daily orders.
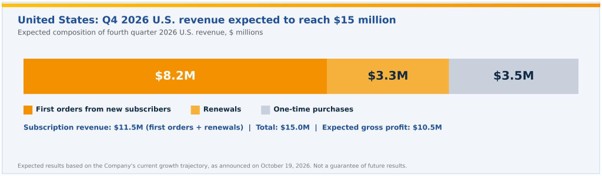
- Minor point. Forward-looking: it has not happened yet and may not happen.Fourth-quarter U.S. forecast includes approximately $15 million revenue and $10.5 million gross profit at approximately 70% margin.
- Minor point. Forward-looking: it has not happened yet and may not happen.Subscription expansion into additional products and markets is planned for evaluation using retention, acquisition costs and contribution economics.
- Minor pointManufacturing agreement duration averages approximately four years and extends up to ten years.
- Minor pointCana's capsule production line was inaugurated in June 2026, expanding manufacturing capabilities.
- Minor pointCosmoFarm customer additions totaled nearly 100 pharmacies in 2025, alongside record distribution volumes.
- Minor point. Forward-looking: it has not happened yet and may not happen.Key proprietary brands are expected to generate gross margins above 70%.
- Minor pointLiabilities-to-assets ratio improved 550 basis points, from approximately 71.9% to 66.4%.
- Minor pointNon-core assets total approximately $20 million, including real estate independently valued at approximately $15 million.
- Minor pointCCX0722 patent application entered the European regional phase and national phases in the United States, Australia and Canada.
- Minor pointAnticancer development rights include exclusive licensing and buy-out rights to two patented drug candidates.
Negative
- Moderate point. Forward-looking: it has not happened yet and may not happen.Manufacturing pipeline execution determines actual orders, volumes and timing under the multi-year agreements.
- Moderate pointGreek distribution acquisition remains subject to a non-binding letter of intent; the target has approximately €10 million annual revenue.
- Minor point. Forward-looking: it has not happened yet and may not happen.U.S. fourth-quarter forecast depends on the current growth trajectory and a significantly expanded marketing budget.
- Minor point. Forward-looking: it has not happened yet and may not happen.U.S. subscription durability depends on renewals, retention and customer acquisition efficiency.
News Explained
The new 2029 financial figures are objectives, not present results.
Cosmos Health says CEO Greg Siokas issued a shareholder letter with a 2026 business update. The letter reports that the company has already spent about
The company estimates more than
For fiscal 2029, the company sets objectives of
Details
Market move: COSM +5.05% vs previous close. 2026 revenue guidance update
On Oct 20, the day this news came out, the latest delayed price for COSM is 5.05% above the previous close. Our momentum scanner has recorded 9 alerts for this stock so far that day. The latest delayed price is $0.34.
Data tracked by StockTitan Argus (15 min delayed). Upgrade to Gold for real-time data.
Key Figures
- Nine-month revenue
- approximately $54.3 million, up 19% year over year
- Preliminary 2026 results
- 2026 revenue outlook
- surpass $90 million
- Full-year expectation reaffirmed
- Active U.S. subscriptions
- 8,940
- As of October 19, 2026
- Monthly subscription value
- $1,325,338
- At standard renewal pricing
- Expected fourth-quarter U.S. revenue
- approximately $15 million
- 2026 outlook
- 2029 revenue guidance
- $200.6 million
- Fiscal 2029 financial objectives
- 2029 gross margin objective
- approximately 35.5%
- Fiscal 2029 guidance; compared with 12.1% in fiscal 2025
- Contract manufacturing pipeline
- more than 32.7 million units
- Cana Laboratories pipeline
Historical Context
-
Reported 6,287 subscriptions and 60.5% order subscription share, providing comparable baselines for the updated figures.
24h Move is the share-price change in the day after each event; other market factors may also have contributed.
Key Terms
adjusted ebitda financial
non-gaap financial
sale-and-leaseback financial
AI-generated analysis. How Rhea-AI works. Not financial advice.




CHICAGO, IL / ACCESS Newswire / October 20, 2026 / Cosmos Health Inc. ("Cosmos Health" or the "Company") (NASDAQ:COSM), a diversified, vertically integrated global healthcare group, today announced that its Chief Executive Officer, Greg Siokas, has issued the following letter to the Company's shareholders, providing a 2026 business update.
Dear Fellow Shareholders,
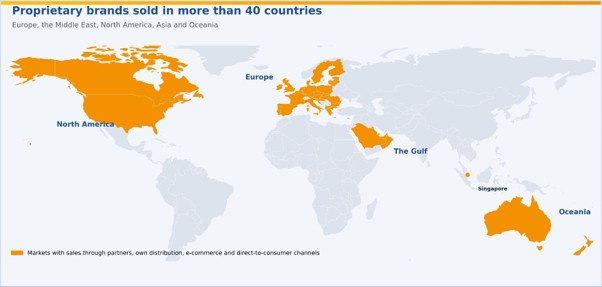
2026 marks a defining moment in the evolution of Cosmos Health. For years, we have invested in pharmaceutical manufacturing, automated distribution, proprietary brands, technology and international expansion to build a vertically integrated global healthcare platform. Today, those investments are converging. Our established businesses are operating at record levels, our proprietary brands are sold in more than 40 countries, our contract manufacturing pipeline has expanded sixfold since mid-2024, and our recently launched U.S. direct-to-consumer business is adding a new source of higher-margin, recurring revenue. We have achieved this amid global uncertainty and geopolitical instability.
Our preliminary nine-month revenue of approximately
Our Strategy: Five Pillars
We have built complementary capabilities across pharmaceutical manufacturing, automated distribution, proprietary products, direct-to-consumer sales and research. Five strategic pillars guide how we convert these assets into stronger operating performance and long-term shareholder value:
- Higher-margin proprietary portfolio. We are shifting our business mix toward proprietary, science-driven products and specialized contract manufacturing. This shift is the principal driver of our planned gross margin expansion, from
12.1% in fiscal 2025 toward a targeted35.5% by fiscal 2029. - Recurring, direct-to-consumer revenue. Through our U.S. e-commerce platform, we sell proprietary products directly to customers, increasingly on a subscription basis, creating recurring relationships and a materially higher expected gross margin. We intend to evaluate extending this model to additional products and markets.
- Innovation. Our R&D programs, including the CCX0722 weight-management device, our novel anticancer drug candidates, the Cloudscreen AI drug repurposing platform and our nanotechnology-based formulations, are designed to create proprietary intellectual property and future product opportunities.
- Global integrated healthcare platform. Pharmaceutical manufacturing, automated distribution supported by robotics and AI-enabled systems, and commercial reach in more than 40 countries allow us to develop, produce and sell products across multiple markets while controlling quality and cost.
- Financial discipline and capital allocation. We prioritize high-return investments, recurring revenue, balance sheet strength and cash generation, and we evaluate targeted acquisitions where they can accelerate growth.
What matters now is how these priorities translate into measurable operating performance, beginning with revenue.
1. Record Revenue: Preliminary Nine-Month Revenue Up
Every quarter of 2026 has set a record for its period:
- Nine months: preliminary revenue of approximately
$54.3 million , up19% , or$8.7 million , from the same period of 2025 and up35% from the first nine months of 2024 - First half: revenue up approximately
30% year over year, with the first quarter up31% and the second quarter up29% - Third quarter: approximately
$17.4 million , the highest third quarter in our history and up40% from the third quarter of 2024, building on a strong third quarter of 2025 - Scale: in nine months, we generated approximately the same revenue as in all of 2024, and
83% of record full-year 2025 revenue
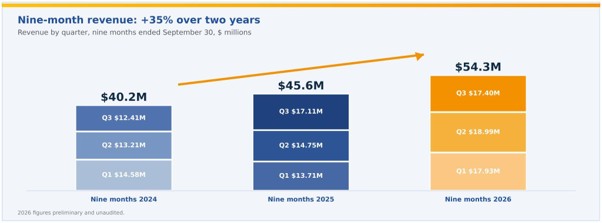
Quarterly revenue has also moved to a structurally higher level, from approximately
Viewed over a longer horizon, the shift is even more pronounced. From fiscal 2020 to fiscal 2024, revenue held within a range of approximately
The pace of growth confirms the change. From fiscal 2019 to fiscal 2025, revenue grew at a compound annual rate of approximately
2. 2026 Outlook Reaffirmed: Over
We reaffirm our expectation that full-year 2026 revenue will surpass
A step-up of this size is driven by every part of our business. All of our segments are core to Cosmos Health; in this letter, we refer to contract manufacturing, pharmaceutical distribution and proprietary brands as our established core segments, and we discuss our U.S. e-commerce business separately because it is new and growing at a different pace. For the fourth quarter, we expect:
- Established core segments, approximately
$20.7 million or more: led by contract manufacturing orders under Cana's record CMO pipeline, seasonal strength in pharmaceutical distribution at CosmoFarm and continued growth of our proprietary brands - U.S. e-commerce business, approximately
$15 million : from our direct-to-consumer subscription model, as announced on October 19, 2026
The figure for our established core segments is implied by our consolidated outlook rather than separate segment guidance. The outlook therefore rests on two complementary foundations: continued growth from businesses with long operating histories, and a new, rapidly scaling source of revenue in the United States.
3. United States: 8,940 Subscriptions and Approximately
Our U.S. business was launched only months ago. We designed it as an e-commerce, direct-to-consumer model: our products are sold through our own online stores directly to customers, who can choose a subscription for recurring delivery at checkout. Selling directly, without intermediaries, allows us to retain the full margin and build a direct relationship with every customer.
It is already our fastest-growing business. As of October 19, 2026:
- 8,940 active U.S. subscriptions, up
42% from 6,287 just five days earlier $1,325,338 in monthly subscription value at standard renewal pricing, up44% over the same five days- 14,624 U.S. online checkout orders tracked by our platform, up
34% over the same five days 65.2% of U.S. online checkout orders have included a subscription since the inception of our subscription platform, rising to more than85% of daily orders in recent days
Subscription adoption is a promising early indicator. When more than eight in ten new orders include a subscription, each new customer represents a potential recurring relationship rather than a single sale, and successive monthly cohorts can build on one another. Over time, the durability of this business will depend on renewals, retention and the efficiency of customer acquisition, which we monitor closely.
Based on our current growth trajectory and a significantly expanded marketing budget, we expect for the fourth quarter:
- U.S. revenue of approximately
$15 million , with gross profit of approximately$10.5 million at an approximately70% gross margin - Subscription revenue of approximately
$11.5 million , including approximately$8.2 million from first orders and$3.3 million from renewals, with one-time purchases contributing approximately$3.5 million - U.S. daily sales to more than triple, from
$60,000 at the start of the quarter to more than$200,000 b y year-end - More than 40,000 active U.S. subscriptions by year-end, more than four times current levels
The margin profile is what makes this business strategically important. With an expected gross margin of approximately
We intend to evaluate extending the subscription model to additional products and markets, guided by customer retention, acquisition costs and contribution economics. While the U.S. is our newest growth engine, our established core segments continue to provide the foundation on which it builds, beginning with contract manufacturing.
4. Contract Manufacturing: CMO Pipeline Up Sixfold to More Than 32.7 Million Units
Cana Laboratories, our pharmaceutical manufacturing subsidiary, operates a 54,000-square-foot facility in Athens and has built the largest contract manufacturing (CMO) pipeline in its history:
- More than 32.7 million units, up sixfold since mid-2024, from more than 12 million units at the start of 2026 and more than 25 million in June
- 11 therapeutic categories, under agreements averaging approximately four years and extending up to ten years
- More than
$20 million in implied revenue and more than$18 million in implied gross profit over the life of the agreements - Expanding capabilities, including a new capsule production line inaugurated in June 2026
Two features make this pipeline particularly valuable. Because the agreements run for several years, it offers multi-year production visibility, although actual orders, volumes and timing will depend on execution. And with an implied gross margin of approximately
5. Pharmaceutical Distribution: CosmoFarm Revenue Up 4.3 Times Under Our Ownership
If contract manufacturing provides visibility, CosmoFarm, our pharmaceutical distribution subsidiary, provides scale. It continues to set new records:
- Record second-quarter revenue of more than
$15 million , an annualized run-rate of more than$60 million and approximately 4.3 times the roughly$14 million CosmoFarm generated in fiscal 2017, the year before we acquired it - Record volumes across a network of more than 1,500 pharmacies, after adding nearly 100 new pharmacy customers in 2025 alone
- Automated operations, including ROWA and A-frame robotic systems and AI-enabled order management, building capacity that we believe could support more than
$100 million in annual revenue over time - Acquisition opportunity: a non-binding letter of intent to acquire an established pharmacy distribution network serving the Greek market, with approximately €10 million in annual revenue
As volume increases through our existing network and automated infrastructure, we see opportunities to improve operating efficiency and service levels, while product mix, pricing and working capital discipline will determine how that scale translates into earnings. The same network also supports the international reach of our proprietary brands.
6. Proprietary Brands: Six Categories, More Than 40 Countries
Our portfolio of more than 15 proprietary brands and product lines across nutraceuticals, infection control, advanced formulations, and skin care and mother and baby, plus ten branded generics, is now sold in more than 40 countries across Europe, the Middle East, North America, Asia and Oceania, through local partners, our own distribution network, e-commerce and direct-to-consumer channels, addressing global markets worth an estimated
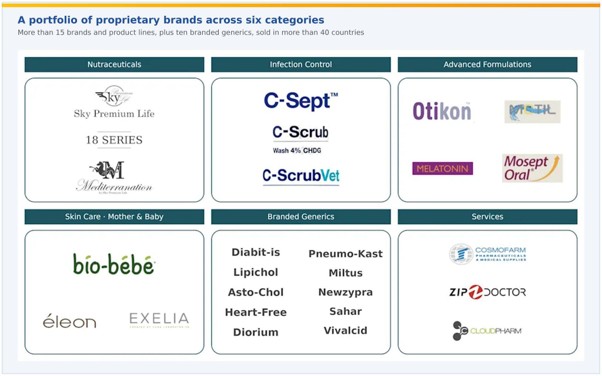
- Sky Premium Life: our flagship nutraceutical brand, with more than 150 SKUs, showing particular momentum in Europe and the Gulf. It is present in five Gulf markets through leading local pharmacy partners and is available across all 27 EU Member States through e-commerce.
- C-Scrub: validated under EN 12791 for surgical hand disinfection, opening hospital and clinical channels, and available through Tesco, Superdrug and Amazon in the United Kingdom.
- C-Sept PRO: adopted across leading Greek public and private hospital groups.
- C-ScrubVet: tested under EN 1656 and EN 1657 and launched in the United Kingdom, marking our entry into the global animal health market, a sector worth an estimated
$69 billion . - Subscription model: driving our U.S. e-commerce growth.
Growth across these businesses is supported by a balance sheet that has become both stronger and more diversified.
7. Balance Sheet: Liabilities Down
Our balance sheet has strengthened as our business has grown, and we continue to manage it with discipline:
- Total liabilities down
13.3% between December 31, 2025 and June 30, 2026, improving our liabilities-to-assets ratio by 550 basis points, from approximately71.9% to66.4% - Approximately
$20 million in non-core assets, including wholly owned real estate with an independent fair market valuation of approximately$15 million and digital assets - Flexibility to unlock value through options such as a sale, a sale-and-leaseback or borrowing against these assets, which we would pursue only where it creates value for shareholders and without affecting our operations
- A diversified operating base spanning pharmaceutical manufacturing, robotic logistics, proprietary intellectual property and a growing U.S. e-commerce platform
- More than 5.1 million shares repurchased for approximately
$1.1 million under our$5.0 million share repurchase program, reflecting our confidence in the Company's long-term prospects
Our approach to capital allocation is straightforward: we prioritize opportunities that can improve long-term returns while strengthening the Company's financial position. Non-core assets provide additional flexibility, but our objective is for a growing share of our investment to be funded by the performance of the businesses we operate.
8. Innovation: From Weight Management to Oncology, With R&D Programs Enhanced by AI Drug Repurposing
- CCX0722: Cana Laboratories owns international patent application WO2025108566A1, "Hydrogel for Body Weight Management," for CCX0722, a superabsorbent hydrogel in development for weight management, designed to expand in the stomach and support satiety through a mechanical mode of action. The application has entered the European regional phase and national phases in the United States, Australia and Canada, in a global weight-management market valued at approximately
$190 billion in 2025 and projected to reach$562 billion by 2033. - Novel anticancer drugs: exclusive licensing and buy-out rights to two patented anticancer drug candidates targeting, among others, prostate, ovarian and colorectal cancers, markets projected to reach a combined value of approximately
$44 billion by 2030. The drug candidates were independently valued at approximately$24.6 million in January 2025. - Cloudscreen: our AI-driven drug repurposing platform combines computational methods with experimental validation to identify potential new uses for known compounds in oncology, neurology, inflammation, obesity and diabetes.
- Nanotechnology: our program develops next-generation nutraceutical formulations designed to improve absorption, stability and bioactivity, manufactured at Cana Laboratories.
We continue to invest in innovation while remaining focused on disciplined execution across our existing operations. Both priorities inform our long-term financial plan.
9. The Road to 2029:
Our 2029 financial objectives are built around an evolving business mix: an established distribution base, a growing contract manufacturing pipeline, an international portfolio of proprietary brands and a newer U.S. subscription platform. As higher-margin activities represent a greater share of revenue, our fiscal 2029 guidance calls for:
- Revenue of
$200.6 million , up207% from fiscal 2025 - Gross profit of
$71.2 million , up801% , with gross margin expanding from12.1% to approximately35.5% - Adjusted EBITDA, a non-GAAP measure, of
$44.2 million , an improvement of$47.6 million from negative$3.4 million in fiscal 2025 - Net income of
$31.0 million and stockholders' equity of$92.3 million , up402%
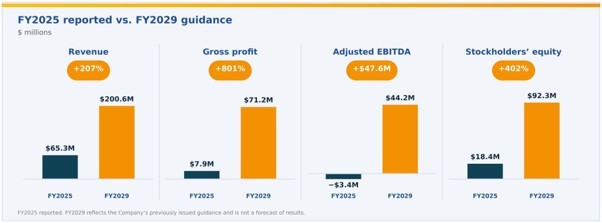
These targets depend on more than growing the top line. Increasing the share of proprietary products, specialized manufacturing and direct sales is intended to drive gross profit growth that outpaces revenue, while achieving our adjusted EBITDA objectives will require disciplined marketing investment, execution of manufacturing contracts, customer retention and control of operating expenses. Our objective is for the business to become self-funding by 2027.
Looking Ahead: Realizing the Platform's Potential
I believe Cosmos Health is entering a new phase. We have spent years building a diversified healthcare platform; our priority now is to convert that foundation into durable operating results. Our CMO pipeline, distribution network, international brands and U.S. subscription platform provide complementary sources of growth, rather than dependence on any single product or market.
Our priorities are clear: deliver on our 2026 outlook of more than
I thank our employees, partners and shareholders for their continued commitment and trust. We have built the platform. We are now focused on realizing its potential.
A Personal Word to Our Shareholders
In 2015, I began building Cosmos Health in Thessaloniki from a small 650-square-foot office, with a very strong conviction: that a company from Greece could build healthcare products good enough for the world. People told me it could not be done. Eleven years later, our products are sold in more than 40 countries. Surgeons scrub with our antiseptics before they operate. Our laboratory in Athens manufactures medicines for partners across Europe. And families across America open a box from Cosmos Health at their front door.
I will not pretend the road has been easy, for me or for you. I have felt your frustration, because I share it, and I am grateful for the patience and trust you have shown. I am confident that we are on a path of strong growth and that our strategy is delivering. Every decision I make, I make as the largest shareholder of this Company, with my own investment on the line beside yours. I believe the years of delivering have begun. You believed in us before the results were visible. Now they are becoming visible, and I intend to prove, quarter after quarter, that your belief was not misplaced.
Sincerely,
Greg Siokas, Chief Executive Officer, Cosmos Health Inc.
«Το εφικτό του ανέφικτου έλαβε χώρα»
"The unthinkable has happened. The impossible has been achieved."
Revenue figures for 2026 are estimated, preliminary and unaudited, fourth-quarter 2025 revenue is derived from reported results, and subscription and order figures are preliminary operating data. Monthly subscription value, calculated at standard renewal pricing, and adjusted EBITDA are non-GAAP measures that should not be considered substitutes for revenue, net income or other GAAP measures; a reconciliation of forward-looking adjusted EBITDA is not provided because certain reconciling items cannot be predicted without unreasonable efforts. The 2026 outlook, implied fourth-quarter revenue, including the implied contribution of established core segments, which is not separate guidance, U.S. expectations, capacity estimates, the 2027 self-funding objective and 2029 guidance are estimates based on current trends and internal assumptions, and actual results may differ materially. Implied CMO revenue, asset values and market sizes are estimates; the proposed acquisition is subject to a non-binding letter of intent; share repurchases are at management's discretion; and CCX0722 and the Company's anticancer drug candidates have not been approved by any regulatory authority.
About Cosmos Health Inc.
Cosmos Health Inc. (NASDAQ: COSM), incorporated in 2009 in Nevada, is a diversified, vertically integrated global healthcare group. The Company owns a portfolio of proprietary pharmaceutical and nutraceutical brands, including Sky Premium Life®, Mediterranation®, bio-bebe®, C-Sept® and C-Scrub®. Through its subsidiary Cana Laboratories S.A., licensed under European Good Manufacturing Practices (GMP) and certified by the European Medicines Agency (EMA), it manufactures pharmaceuticals, food supplements, cosmetics, biocides, and medical devices within the European Union. Cosmos Health also distributes a broad line of pharmaceuticals and parapharmaceuticals, including branded generics and OTC medications, to retail pharmacies and wholesale distributors through its subsidiaries in Greece and the UK. Furthermore, the Company has established R&D partnerships targeting major health disorders such as obesity, diabetes, and cancer, enhanced by artificial intelligence drug repurposing technologies, and focuses on the R&D of novel patented nutraceuticals, specialized root extracts, proprietary complex generics, and innovative OTC products. Cosmos Health has also entered the telehealth space through the acquisition of ZipDoctor, Inc., based in Texas, USA. With a global distribution platform, the Company is currently expanding throughout Europe, Asia, and North America, and has offices and distribution centers in Thessaloniki and Athens, Greece, and in Harlow, UK. More information is available at www.cosmoshealthinc.com, www.skypremiumlife.com, www.cana.gr, www.zipdoctor.co, www.cloudscreen.gr, as well as LinkedIn and X.
Forward-Looking Statements
With the exception of the historical information contained in this news release, the matters described herein may contain forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Words such as "believes," "expects," "anticipates," "intends," "projects," "estimates," "plans," and similar expressions, or future or conditional verbs such as "will," "should," "would," "may," and "could," generally identify forward-looking statements, although not all forward-looking statements contain these words. These statements involve risks and uncertainties that may individually or materially affect the matters discussed herein for a variety of reasons outside the Company's control, including, but not limited to: the Company's ability to raise sufficient financing to implement its business plan; the effectiveness of its digital asset strategies, including accumulation and yield-generating activities; the impact of the war in Ukraine and ongoing conflicts in the Middle East and other regions on the Company's business, operations, and the economy in general; the Company's ability to successfully develop and commercialize its proprietary products and technologies; the timing, execution, regulatory clearance, valuation, structuring, and completion of any potential asset-backed or tokenized financing program; the legal, regulatory, and technological risks associated with digital assets and blockchain-based financial structures; the conversion of contract manufacturing pipeline volumes into production and revenue, including the timing, volume and terms of orders placed under multi-year agreements; the realization of anticipated gross margins; the timing, cost and completion of planned capital investments; changes in interest rates; changes in foreign currency exchange rates, commodity or other price inflation and deflation; our ability to issue debt on terms and at rates acceptable to us; the impact and expected outcome of investigations, inquiries, claims, and litigation; the challenges of operating in international markets; the adequacy of insurance coverage; the effect of accounting charges and of adopting certain accounting standards; the impact of legal and regulatory changes, including changes to tax laws and regulations; guidance for fiscal 2026 and beyond and financial outlook. Forward-looking statements are based on currently available information and our current assumptions, expectations and projections about future events. You should not rely on our forward-looking statements. These statements are not guarantees of future performance and are subject to future events, risks and uncertainties - many of which are beyond our control, dependent on the actions of third parties, or currently unknown to us - as well as potentially inaccurate assumptions that could cause actual results to differ materially from our historical experience and our expectations and projections. These risks and uncertainties include, but are not limited to, those described from time to time in our periodic reports filed with the SEC and available at the SEC's website (www.sec.gov). There also may be other factors that we cannot anticipate or that are not described herein, generally because we do not currently perceive them to be material. Such factors could cause results to differ materially from our expectations. Forward-looking statements speak only as of the date they are made, and we do not undertake to update these statements other than as required by law. You are advised, however, to review any further disclosures we make on related subjects in our filings with the Securities and Exchange Commission and in our other public statements.
Investor Relations Contact:
BDG Communications
cosm@bdgcommunications.com
SOURCE: Cosmos Health Inc.
View the original press release on ACCESS Newswire
FAQ
AI-generated questions and answers. How Rhea-AI works. Not financial advice.
What is Cosmos Health's 2026 revenue outlook?
Cosmos Health expects full-year 2026 revenue to surpass $90 million. Preliminary revenue through September was approximately $54.3 million, implying fourth-quarter revenue of approximately $35.7 million or more, an increase of approximately 81% over approximately $19.7 million in the fourth quarter of 2025.
How much fourth-quarter revenue does Cosmos Health expect from U.S. subscriptions?
Cosmos Health expects approximately $11.5 million in fourth-quarter subscription revenue, including approximately $8.2 million from first orders and $3.3 million from renewals. One-time purchases are expected to contribute approximately $3.5 million, bringing expected U.S. revenue to approximately $15 million.
How could Cosmos Health use its non-core assets?
Cosmos Health is considering a sale, sale-and-leaseback or borrowing against non-core assets. The company would pursue these options only where they create shareholder value without affecting operations. Its approximately $20 million in non-core assets includes wholly owned real estate and digital assets.