
Saturn Oil & Gas Inc. Continues Strategic Core Area Expansion with Acquisition of 100% Light Oil-Weighted Corex Resources Ltd.
Corex shareholders holding greater than 72% of outstanding shares have approved the acquisition, exceeding the two-thirds threshold.
Sentiment and the balance of points
Rhea-AI Sentiment reads the wording of the document, how positive or negative its language is on a 1 to 5 scale. The balance of points shown with the takes weighs what the document actually discloses, so the two can disagree, for example when a trial that missed its main goal is described in upbeat language.
Rhea-AI Summary
Saturn Oil & Gas (OILSF) agreed to acquire all shares of privately held Corex Resources for approximately $302 million.
Consideration comprises approximately $252 million cash and $50 million in Saturn shares. Closing is expected in December 2026, subject to court, regulatory and stock exchange approvals. The Manitoba assets add approximately 7,000 barrels per day of light oil production, assuming $77.8 million of development capital over the next 12 months.
Saturn forecasts $192 million in run-rate net operating income at October 13, 2026 strip pricing, or market-implied future prices. The purchase price represents 1.6 times that income. Saturn raised its forecast 2026 exit production to 54,000–56,000 barrels of oil equivalent per day; full-year average guidance remains 43,000–44,000. Its target exit-2027 net debt to adjusted EBITDA ratio remains below one times. Cash on hand and a credit facility draw will fund the cash consideration.
How this balance works
Rhea-AI gives every point it takes from this document a weight. Minor counts 1, Moderate 3 and Major 9, so one Major point outweighs several Minor ones. The bar adds up the weights on each side, and when neither side holds more than 65% of the total the balance reads Mixed.
It reads the document as published, with the same rules for every company, and it does not look at what the market expected or at how the stock traded, so a point can be objectively good on a day the stock falls.
Rhea-AI Sentiment measures something else, the tone of the wording.
Hollow bars mark forward-looking points. How the balance works
Positive
- Major point$302 million purchase price represents approximately 1.6 times run-rate net operating income and 82% of PDP NPV10. 30% of market cap
- Major point. Forward-looking: it has not happened yet and may not happen.54,000–56,000 boe/d forecast 2026 exit production reflects the acquisition and expanded capital program.
- Moderate point. Forward-looking: it has not happened yet and may not happen.Approximately 7,000 bbl/d of light oil production added, assuming $77.8 million development capital over the next 12 months. 7.6% of market cap
- Moderate point. Forward-looking: it has not happened yet and may not happen.Operating netback and adjusted and free funds flow per share expected to increase immediately.
- Minor point. Forward-looking: it has not happened yet and may not happen.$192 million net operating income forecast for November 2026–November 2027, assuming October 13, 2026 strip pricing.
11 minor points
- Minor point. Forward-looking: it has not happened yet and may not happen.$82.00/bbl operating netback, revenue less royalties and operating and transportation costs, estimated at current strip prices.
- Minor point. Forward-looking: it has not happened yet and may not happen.Exit-2027 leverage target below one times net debt to adjusted EBITDA remains unchanged.
- Minor point323 gross / 279 net identified drilling locations include 206 gross / 189 net booked locations.
- Minor pointNearly 30 net Lodgepole and an estimated 25 net Spearfish unbooked multi-lateral drilling locations identified.
- Minor point. Forward-looking: it has not happened yet and may not happen.Approximately $6 million annual efficiency synergies estimated; Saturn expects approximately $2.85/bbl lower acquired-asset costs.
- Minor point. Forward-looking: it has not happened yet and may not happen.Approximately 86% liquids weighting expected following the addition of Corex's light oil volumes.
- Minor point. Forward-looking: it has not happened yet and may not happen.Waterflood expansion potential could mitigate declines; existing schemes cover approximately 14% of forecast 2026 production.
- Minor pointOwned and operated infrastructure includes underutilized marketing infrastructure, with no apportionment concerns in Southwest Manitoba.
- Minor point. Forward-looking: it has not happened yet and may not happen.Marketing improvements planned to pursue premium pricing through transportation and blending synergies.
- Minor pointGreater than 72% shareholder approval at Corex exceeds the acquisition's two-thirds threshold.
- Minor point. Forward-looking: it has not happened yet and may not happen.$15 million termination fee payable to Saturn in specified circumstances, including Corex accepting a superior proposal.
Negative
- Major point. Forward-looking: it has not happened yet and may not happen.Approximately $252 million cash consideration requires cash on hand and additional credit facility borrowing. 25% of market cap
- Moderate point. Forward-looking: it has not happened yet and may not happen.$77.8 million development capital over the next 12 months underpins the acquired production assumption. 7.6% of market cap
- Minor point. Forward-looking: it has not happened yet and may not happen.$50 million in Saturn shares, valued using the preceding 20-day volume-weighted average price, will dilute holders.
- Minor pointCourt, regulatory and stock exchange approvals remain conditions for the expected December 2026 closing.
- Minor point. Forward-looking: it has not happened yet and may not happen.$15 million reciprocal fee payable by Saturn in specified circumstances, including failure to fund acquisition consideration.
News Explained
Corex shareholder approval has been secured, but the acquisition is not closed and still requires court, regulatory and stock-exchange approvals.
Saturn has entered a definitive agreement to acquire all Corex shares for
Corex shareholders holding more than
Shares issued to Corex majority shareholder Azimuth are subject to a lock-up, with release in three equal tranches over the 18 months after closing.
AI-generated analysis. How Rhea-AI works. Not financial advice.




Acquisition adds ~7,000 bbl/d(1,5) of
100% light oil production, expanding Saturn's Southeast Saskatchewan core area into Manitoba and increasing our forecast 2026 exit production rate to 54,000 - 56,000 boe/d(1,6)Accretive
$82.00 /bbl(2)netbacks at current strip pricing, contributing to an estimated$192 million of run-rate net operating income (NOI)(2,5)Purchase price of
$302 million represents 1.6x NOI(2,5) and82% of PDP NPV10(4) value, aligning with Saturn's blueprint strategyTransaction is expected to be immediately accretive to operating netback, adjusted funds flow per share and free funds flow per share, while exit 2027 target leverage metrics remain unchanged at under one times
Complementary development adds 323 gross (279 net) identified locations(3,7) to Saturn's drilling inventory, with incremental open hole multi-lateral potential not reflected in current reserves value
Calgary, Alberta--(Newsfile Corp. - October 19, 2026) - Saturn Oil & Gas Inc. (TSX: SOIL) (OTCQX: OILSF) ("Saturn" or the "Company"), a light oil-weighted producer focused on unlocking value through the development of assets in Saskatchewan, Alberta and Manitoba, is pleased to announce that we have entered into a definitive arrangement agreement (the "Arrangement Agreement") with Corex Resources Ltd. ("Corex"), a privately held Calgary-based company, pursuant to which Saturn will acquire all of the issued and outstanding shares of Corex by way of a plan of arrangement under the Business Corporations Act (Alberta), for total consideration to Corex shareholders of
The Acquisition consists of approximately 7,000 bbl/d(1,6) of
"This Acquisition embodies the Saturn blueprint in action, adding premium oil barrels for only 1.6 times net operating income(2,5) ("NOI") and approximately
Francesco Mele, COO & Partner at Azimuth, commented on the Acquisition, "Given the development success that Saturn has demonstrated, particularly with the advancement of OHML drilling and the application of new technologies in SE SK, including equity as a component of consideration enables Corex shareholders to participate in future upside driven by Saturn's continued strategic execution and oil-weighted asset base that offers attractive, long-term development potential."
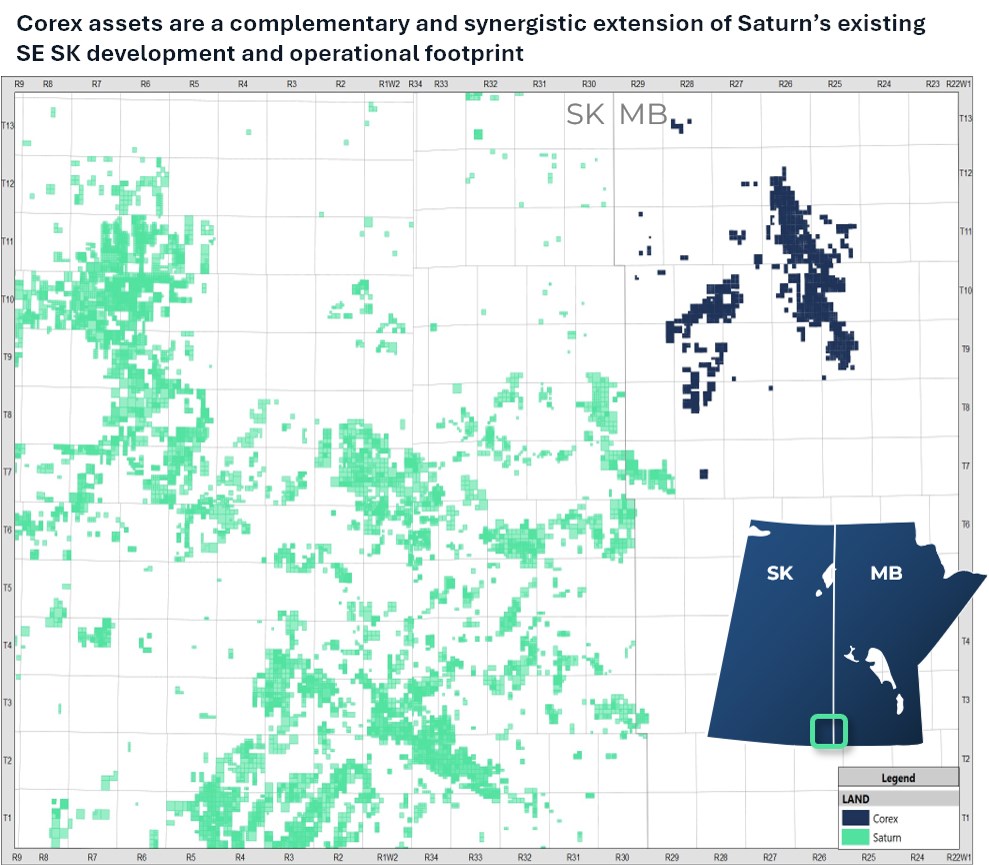
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/8024/319625_e61febdb04643bc1_001full.jpg
ACQUISITION HIGHLIGHTS
Core-Up Strategy in Action: Builds on Saturn's established operations and play expertise within our core SE SK and new SW MB areas, where we expect to capture synergies, reduce operating costs and improve margins while advancing development of the Lower Mississippian conventional reservoir. In SE SK, Saturn has realized ongoing development success and a track record of capturing synergistic efficiencies due to our size and scale, which we intend to replicate in SW MB.
Strong Operating Netbacks: Operating netbacks at current strip prices are estimated at
$82.00 /bbl(2,5), supported by100% light oil production and the potential to reduce per unit costs on the acquired assets by approximately$2.85 /bbl upon integration.Setting Up for a Strong 2027: While the addition of Corex production and inventory during the first half of December is not anticipated to impact our full year 2026 average production guidance of 43,000 to 44,000 boe/d, the Acquisition, along with Saturn's expanded 2026 capital program, positions the Company to exit this year with production of 54,000 to 56,000 boe/d, establishing a strong base for 2027.
Enhanced Net Debt Reduction: With an estimated
$192 million of NOI(2,5) forecast over the next 12 months at current strip prices, the acquired assets are expected to support increased adjusted funds flow(5) ("AFF") per share and free funds flow per share(5) in 2027, which will afford Saturn financial flexibility to continue reducing net debt, returning capital to shareholders through share buybacks, and is expected to position the Company to exit 2027 with net debt to adjusted EBITDA(5) of less than one times.Expanded Drilling Inventory with OHML Development Potential: Attractive location inventory includes over 323 gross identified locations (279 net)(3,7), including 206 gross (189 net) booked locations(4) within Corex's most recent reserve report. Nearly 30 net unbooked OHML locations(3) have been identified by Saturn in the Lodgepole formation at Virden, plus an estimated 25 net unbooked OHML Spearfish locations(3), representing potential value beyond what is booked in the most recent Corex reserves report.
Marketing Opportunities to Improve Realized Pricing: With expanded production in SE SK and SW MB, Saturn is positioned to capture synergies in transportation and blending agreements, and we intend to enhance marketing arrangements to achieve premium pricing and maintain clear market access. In addition, the assets' proximity to the Enbridge Mainline and gathering systems improves stability in oil differentials, which can translate into higher pricing.
Waterflood Expansion Opportunities: Existing waterflood schemes on approximately
14% of forecast 2026 production have the potential to be expanded to further mitigate declines, provide pressure support and enhance Saturn's long-term sustainability.Owned Infrastructure: The Acquisition includes owned and operated infrastructure, including underutilized marketing infrastructure, with no apportionment concerns in SW MB, and optimal positioning for pipeline egress. Saturn has also identified meaningful consolidation opportunities to improve efficiencies and streamline costs.
STRATEGIC BENEFITS
Increased Light Oil Weighting: Adding approximately 7,000 bbl/d(1,6) of
100% light oil volumes increases Saturn's liquids weighting to approximately86% , while the addition of premium barrels is accretive to our netbacks.Expanded Size and Scale: The clean, contiguous and high working interest (~
96% ) asset base increases our production and reserves, positioning the Company to negotiate stronger marketing arrangements and enhancing our ability to optimize operations. Pro-forma the Acquisition, Saturn is expected to be the second-largest producer in MB.Accretive on Key Metrics with No Change to Target Leverage Ratios: The Acquisition is accretive to Saturn on key metrics, including netback per boe, AFF per share and free funds flow per share. With the addition of higher netback volumes plus organic growth from our expanded second-half 2026 capital program, Saturn maintains our target exit 2027 net debt to adjusted EBITDA ratio at under one times.
Identified Synergies and Lower Operating Costs: Saturn has identified approximately
$6 million of estimated annual efficiency synergies. By targeting facility consolidations, streamlining labour, reducing operating costs and improving marketing arrangements, the Company expects to realize a reduction in per-unit costs on the assets of approximately$2.85 /bbl.
TRANSACTION DETAILS & ACQUISITION METRICS
Pursuant to the Arrangement Agreement, Saturn will acquire all of the issued and outstanding shares of Corex for aggregate consideration of approximately
"As Saturn has systematically bought nearly 26 million shares over the past two years at an average price of approximately
A summary of the relevant metrics associated with the Acquisition follows:
| Total consideration ($MM) | |
| Production (bbl/d)(1,6) | 7,000 |
| Oil & liquids weighting (%) | |
| Land (net acres) | ~84,000 |
| PDP NPV10 ($MM)(4) | ~ |
| Total proved (1P) NPV10 ($MM)(4) | ~ |
| Total proved + probable (2P) NPV10 ($MM)(4) | ~ |
| Identified drilling locations (gross / net)(3,7) | 323 / 279 |
| Booked drilling locations (gross / net)(7) | 206 / 189 |
| Operating netback ($/bbl)(5) | |
| Run Rate NOI ($MM)(2,5) | |
| Purchase Price as a Multiple of Run Rate NOI (x)(5) | 1.6 |
THE ARRANGEMENT AGREEMENT
In connection with the Arrangement Agreement, certain shareholders of Corex, who collectively hold greater than
The board of directors of each of Saturn and Corex has unanimously determined that entering into the Arrangement Agreement is in the best interests of its respective company. The board of directors, after considering the recommendation by a special committee of the Corex board, and after consultation with its financial and legal advisors, has unanimously determined that the Acquisition is in the best interests of Corex and fair to Corex shareholders from a financial point of view, and resolved to recommend that Corex shareholders approve the Acquisition. Completion of the Acquisition is subject to customary closing conditions for a transaction of this nature, including the receipt of all required court, regulatory and stock exchange approvals. Corex will be distributing further information to the Corex shareholders regarding the Acquisition in the near future, including an information document and the written resolution approving the Acquisition, for review and consideration by the Corex shareholders.
A copy of the Arrangement Agreement will be filed under Saturn's profile on SEDAR+ at www.sedarplus.ca.
ADVISORS
McCarthy Tétrault LLP is acting as legal counsel to Saturn in respect of the Acquisition.
NOTES
(1) Assumes development capital of
(2) On a forward 12-month basis from effective date (November 2026 to November 2027), assuming October 13, 2026, strip pricing.
(3) Based on Company-prepared internal projections.
(4) See reader advisory: Reserves and Future Net Revenue Disclosures
(5) See reader advisory: Non-GAAP and Other Financial Measures.
(6) See reader advisory: Supplemental Information Regarding Product Types.
(7) See reader advisory: Drilling Locations.
ABOUT SATURN
Saturn is a returns-driven Canadian energy company focused on the efficient, responsible and innovative development of high-quality, light oil-weighted assets, supported by an acquisition strategy targeting accretive and complementary opportunities. The Company's portfolio of free-cash-flowing, low-decline operated assets in Saskatchewan, Alberta and Manitoba provides a deep inventory of long-term economic drilling opportunities across multiple zones. With an unwavering commitment to building an entrepreneurial and safety-focused culture, Saturn's goal is to increase per-share reserves, production and cash flow at an attractive return on invested capital. The Company's Shares are listed for trading on the TSX under ticker 'SOIL' and on the OTCQX under the ticker 'OILSF'. Further information and our corporate presentation are available on Saturn's website at www.saturnoil.com.
INVESTOR & MEDIA CONTACTS
John Jeffrey, MBA - Chief Executive Officer
Tel: +1 (587) 392-7900
www.saturnoil.com
Cindy Gray, MBA - VP Investor Relations
Tel: +1 (587) 392-7900
info@saturnoil.com
READER ADVISORIES
Non-GAAP and Other Financial Measures
Throughout this news release and in other materials disclosed by the Company, Saturn employs certain measures to analyze financial performance, financial position and cash flow. These non-GAAP and other financial measures do not have any standardized meaning prescribed under IFRS Accounting Standards, as issued by the International Accounting Standards Board ("IFRS") and therefore may not be comparable to similar measures presented by other entities. The non-GAAP and other financial measures should not be considered to be more meaningful than GAAP measures which are determined in accordance with IFRS, such as net income (loss), cash flow from operating activities, and cash flow used in investing activities, as indicators of Saturn's performance.
The disclosure under the section "Non-GAAP and Other Financial Measures" in our management's discussion and analysis for the year ended December 31, 2025 and three and six months ended June 30, 2026 ("MD&A"), including non-GAAP financial measures and ratios, capital management measures and supplementary financial measures in the Company's financial statements and MD&A are incorporated by reference into this news release.
This news release may use the terms "adjusted EBITDA", "adjusted funds flow", "net debt", "free funds flow", "net debt to annualized adjusted EBITDA" and "net debt to annualized AFF" which are capital management financial measures. See the disclosure under "Capital Management" in our financial statements for the three and six months ended June 30, 2026, for an explanation and composition of these measures, how these measures provide useful information to an investor, and the additional purposes, if any, for which management uses these measures, and, where applicable, a reconciliation of the Company's historical non-GAAP financial measures to the most directly comparable measure calculated in accordance with GAAP for the applicable period then ended.
Adjusted Funds Flow per Share
Adjusted funds flow per share is a non-GAAP ratio used by management to better analyze the Company's performance against prior periods on a more comparable basis. Adjusted funds flow per share is calculated as adjusted funds flow from operations divided by weighted average shares outstanding during the applicable period on a basic or diluted basis.
Free Funds Flow and Free Funds Flow per Share
Saturn uses free funds flow as an indicator of the efficiency and liquidity of its business, measuring its funds after capital investment available to manage debt levels, pursue acquisitions and gauge optionality to pay dividends and/or return capital to shareholders through activities such as share repurchases. Saturn calculates free funds flow as adjusted funds flow in the period less capital expenditures. By removing the impact of current period capital expenditures from adjusted funds flow, management monitors its free funds flow to inform its capital allocation decisions.
Net Operating Expenses
Net operating expense is calculated by deducting processing income primarily generated by processing third party production at processing facilities where the Company has an ownership interest, from operating expenses presented on the statement of income (loss). Where the Company has excess capacity at one of its facilities, it will process third-party volumes to reduce the cost of ownership in the facility. The Company's primary business activities are not that of a midstream entity whose activities are focused on earning processing and other infrastructure-based revenues, and as such third-party processing revenue is netted against operating expenses in the Company's MD&A. This metric is used by management to evaluate the Company's net operating expenses on a unit of production basis. Net operating expense per boe is a non-GAAP financial ratio and is calculated as net operating expense divided by total barrels of oil equivalent produced over a specific period of time. The calculation of the Company's net operating expenses is shown within the "Net Operating Expenses" section of the MD&A.
Operating Netback
The Company's operating netback is determined by deducting royalties, net operating expenses and transportation expenses from petroleum and natural gas sales. The Company's operating netback is used in operational and capital allocation decisions. Presenting operating netback on a per boe basis is a non-GAAP financial ratio and allows management to better analyze performance against prior periods on a per unit of production basis.
Capital Management Measures
National Instrument 52-112 Non-GAAP and Other Financial Measures Disclosure defines a capital management measure as a financial measure that: (i) is intended to enable an individual to evaluate an entity's objectives, policies and processes for managing the entity's capital; (ii) is not a component of a line item disclosed in the primary financial statements of the entity; (iii) is disclosed in the notes to the financial statements of the entity; and (iv) is not disclosed in the primary financial statements of the entity. Please refer to note 13 "Capital Management" in Saturn's financial statements as at and for the period ended June 30, 2026, for additional disclosure on: net debt, adjusted EBITDA, AFF and free funds flow, each of which are capital management measures used by the Company in this news release.
Supplementary Financial Measures
NI 52‐112 defines a supplementary financial measure as a financial measure that: (i) is, or is intended to be, disclosed on a periodic basis to depict the historical or expected future financial performance, financial position or cash flow of an entity; (ii) is not disclosed in the financial statements of the entity; (iii) is not a non‐GAAP financial measure; and (iv) is not a non‐GAAP ratio. The supplementary financial measures used in this news release are either a per unit disclosure of a corresponding GAAP measure, or a component of a corresponding GAAP measure, presented in the financial statements. Supplementary financial measures that are disclosed on a per unit basis are calculated by dividing the aggregate GAAP measure (or component thereof) by the applicable unit for the period. Supplementary financial measures that are disclosed on a component basis of a corresponding GAAP measure are a granular representation of a financial statement line item and are determined in accordance with GAAP.
Supplemental Information Regarding Product Types
The addition of 7,000 bbl/d through the Acquisition, forecast exit 2026 production and forecast 2026 average volumes and the references to "crude oil", "NGLs", and "natural gas" reported in this news release consist of the product types described below, as defined in National Instrument 51-101 - Standards of Disclosure for Oil and Gas Activities ("NI 51-101").
References to gas or natural gas and NGLs in this news release refer to conventional natural gas and natural gas liquids product types, respectively, as defined in NI 51-101, except where specifically noted otherwise. The 7,000 bbl/d being acquired is
Boe Presentation
Boe means barrel of oil equivalent. All boe conversions in this news release are derived by converting gas to oil at the ratio of six thousand cubic feet ("Mcf") of natural gas to one barrel ("Bbl") of oil. Boe may be misleading, particularly if used in isolation. A boe conversion rate of 1 Bbl : 6 Mcf is based on an energy equivalency conversion method primarily applicable at the burner tip and does not represent a value equivalency at the wellhead. Given that the value ratio of oil compared to natural gas based on currently prevailing prices is significantly different than the energy equivalency ratio of 1 Bbl: 6 Mcf, utilizing a conversion ratio of 1 Bbl : 6 Mcf may be misleading as an indication of value.
Reserves and Future Net Revenue Disclosures
All reserves values and future net revenue in respect of Corex contained in this news release are derived from an evaluation by a third-party engineering firm prepared in accordance with the definitions, standards and procedures contained in the Canadian Oil and Gas Evaluation Handbook ("COGEH") and NI 51-101 unless otherwise noted. Corex's reserves and associated net present value are derived from an independent reserves assessment prepared by that third party engineering firm dated April 1, 2026, evaluating the oil and gas properties of Corex as at April 1, 2026 (the "Corex Reserves Report"). The Corex Reserves Report utilizes forecast prices based on the average of forecast prices of McDaniel, Sproule and GLJ Ltd. as at April 1, 2026.
All reserve references in this news release are "Company Gross Reserves". Company Gross Reserves are defined as the applicable company's working interest share of reserves prior to royalty deductions. Estimates of reserves and future net revenue for individual properties may not reflect the same level of confidence as estimates of reserves and future net revenue for all properties, due to the effect of aggregation. There is no assurance that the forecast price and cost assumptions applied by the third party engineering firm in evaluating Corex's reserves will be attained and variances could be material. All reserves assigned in the Corex Reserves Report are located in the Province of Manitoba.
All evaluations and summaries of future net revenue are stated prior to the provision for interest, debt service charges and general and administrative expenses and after the deductions of royalties, operating costs, estimated well abandonment and reclamation costs and estimated future capital expenditures. It should not be assumed that the estimates of future net revenues presented in this news release represent the fair market value of the reserves. The recovery and reserve estimates of crude oil, natural gas liquids and natural gas reserves provided herein are estimates only and there is no guarantee that the estimated reserves will be recovered. Actual crude oil, natural gas and natural gas liquids reserves may be greater than or less than the estimates provided herein. There are numerous uncertainties inherent in estimating quantities of crude oil, reserves and the future cash flows attributed to such reserves. The reserves and associated cash flow information set forth herein are estimates only.
Proved reserves are those reserves that can be estimated with a high degree of certainty to be recoverable. It is likely that the actual remaining quantities recovered will exceed the estimated proved reserves. Probable reserves are those additional reserves that are less certain to be recovered than proved reserves. It is equally likely that the actual remaining quantities recovered will be greater or less than the sum of the estimated proved plus probable reserves. Proved developed producing reserves are those reserves that are expected to be recovered from completion intervals open at the time of the estimate. These reserves may be currently producing, or if shut-in, they must have previously been on production, and the date of resumption of production must be known with reasonable certainty. Undeveloped reserves are those reserves expected to be recovered from known accumulations where a significant expenditure (e.g., when compared to the cost of drilling a well) is required to render them capable of production. They must fully meet the requirements of the reserves category (proved, probable, possible) to which they are assigned. Certain terms used in this news release but not defined are defined in NI 51-101, CSA Staff Notice 51-324 - Revised Glossary to NI 51-101 ("CSA Staff Notice 51-324") and/or the COGEH and, unless the context otherwise requires, shall have the same meanings herein as in NI 51-101, CSA Staff Notice 51-324 and the COGEH, as the case may be.
Drilling Locations Disclosure
This news release discloses "booked" drilling locations with respect to the acquired assets derived from the Corex Reserves Report Booked locations are proved and probable locations derived from the Corex Reserves Report, which were prepared in accordance with NI 51-101 and COGEH. Un-booked locations are internal estimates based on the Company's assumptions as to the number of wells that can be drilled per section based on industry practice and internal review. Un-booked locations do not have attributed reserves or resources. The drilling locations considered for future development will ultimately depend upon the availability of capital, regulatory approvals, seasonal restrictions, oil and natural gas prices, costs, actual drilling results, additional reservoir information that is obtained and other factors.
Future-Oriented Financial Information
This news release contains future-oriented financial information and financial outlook information (collectively, "FOFI") about Saturn's production, capital expenditures, AFF, free funds flow, net debt and leverage, netbacks, forecast NOI, and cost reductions, all of which are subject to the same assumptions and risk factors as other forward-looking information and statements provided in the paragraphs below. Saturn's management believes that FOFI has been prepared on a reasonable basis, reflecting management's best estimates and judgments, and is provided to assist readers in understanding management's expectations for the Company's near-term operating performance and may not be appropriate for other purposes. Saturn disclaims any intention or obligation to update or revise any FOFI contained in this document, whether as a result of new information, future events, or otherwise unless required pursuant to applicable law.
Forward-Looking Information and Statements
Certain information included in this news release constitutes forward-looking information under applicable securities legislation. Forward-looking information typically contains statements with words such as "anticipate", "believe", "expect", "plan", "intend", "estimate", "propose", "project", "scheduled", "will" or similar words suggesting future outcomes or statements regarding an outlook.
Forward-looking information in this news release may include, but is not limited to, statements concerning: the Acquisition, including the anticipated benefits thereof; the anticipated Closing Date; the satisfaction or waiver of the conditions to completion of the Acquisition, including the receipt, in a timely manner and on satisfactory terms, of the required legal and regulatory approvals for the completion of the Arrangement (including court approval, approval of the Toronto Stock Exchange, and approval under the Competition Act (Canada)); the amount and form of consideration payable in connection with the Acquisition, including the number and deemed price of the Saturn Shares to be issued; funding and payment of the purchase price in respect of the Acquisition; the lock-up of the Saturn Shares to be issued to Azimuth; the circumstances in which a termination fee may be payable by Saturn or Corex; the expectation that the Acquisition will be accretive to operating netback, adjusted funds flow per share and free funds flow per share; expected production, oil weighting, operating netbacks and NOI attributable to the acquired assets; expected development capital to be invested in the acquired assets; Saturn's anticipated position as the second-largest producer in SW MB; the timing of release of Saturn's 2027 capital budget, program and guidance; the expected number, timing and economics of future drilling locations related to the acquired assets, including OHML and Spearfish development potential and anticipated rates of return; waterflood expansion opportunities; expected synergies, cost savings and reductions in operating costs resulting from the Acquisition; marketing opportunities and anticipated improvements in realized pricing; target net debt to adjusted EBITDA and leverage ratios exiting 2027; future net debt reduction and the return of capital to shareholders, including through Saturn's normal course issuer bid; management's ability to replicate past performance; reserves estimates; future production levels; decline rates; future negotiation of contracts; future consolidation opportunities and acquisition targets; the business plan, cost model and strategy of the Company; future cash flows; and future commodity prices.
The forward-looking statements contained in this news release are based on certain key expectations and assumptions made by Saturn, including expectations and assumptions concerning: the ability of Saturn and Corex to satisfy the conditions to completion of the Arrangement, including obtaining the required court, regulatory and stock exchange approvals, in a timely manner and on satisfactory terms; the completion of the Acquisition on the terms and within the time currently anticipated; Saturn's ability to fund the cash portion of the purchase price through its credit facility; the accuracy of the reserves, production, drilling location and other information relating to Corex and the acquired assets; the ability to integrate the acquired assets and realize the anticipated benefits and synergies of the Acquisition; the timing and success of future drilling; commodity prices; development and completion activities; the performance of existing wells; the performance of new wells; the availability and performance of facilities and pipelines; the ability to allocate capital to pay down debt and grow or maintain production; the impact of our hedging strategy; the geological characteristics of Saturn's properties; the application of regulatory and licensing requirements; the availability of capital, labour and services; and the creditworthiness of industry partners.
Although Saturn believes that the expectations and assumptions on which the forward-looking statements are based are reasonable, undue reliance should not be placed on the forward-looking statements because Saturn can give no assurance that they will prove to be correct. Since forward-looking statements address future events and conditions, by their very nature they involve inherent risks and uncertainties. Actual results could differ materially from those currently anticipated due to a number of factors and risks. These include, but are not limited to: the risk that the Arrangement may not be completed on the terms or within the time currently anticipated, or at all, including as a result of a failure to satisfy the conditions to completion of the Arrangement or to obtain the required court, regulatory and stock exchange approvals in a timely manner or on satisfactory terms; the risk that the Arrangement Agreement may be terminated in certain circumstances, in which case Saturn may be required to pay a termination fee of
Forward-looking information is based on a number of factors and assumptions which have been used to develop such information but which may prove to be incorrect. Although Saturn believes that the expectations reflected in its forward-looking information are reasonable, undue reliance should not be placed on forward-looking information because Saturn can give no assurance that such expectations will prove to be correct. In addition to other factors and assumptions which may be identified in this news release, assumptions have been made regarding and are implicit in, among other things, the completion and timing of the Acquisition, the integration of the acquired assets, our capital expenditure and drilling programs, production and revenue guidance, ESG initiatives, debt repayment plans and future growth plans. Readers are cautioned that the foregoing list is not exhaustive of all factors and assumptions which have been used.
The forward-looking information in this news release reflects the Company's current expectations, assumptions and/or beliefs based on information currently available to the Company. The forward-looking information contained in this news release is made as of the date hereof and Saturn undertakes no obligation to update publicly or revise any forward-looking information, whether as a result of new information, future events or otherwise, except as may be required by applicable securities laws. The forward-looking information contained in this news release is expressly qualified by this cautionary statement.
All dollar figures included herein are presented in Canadian dollars, unless otherwise noted.
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/319625
FAQ
AI-generated questions and answers. How Rhea-AI works. Not financial advice.
How much will Saturn Oil & Gas pay for Corex Resources?
Saturn will pay approximately $302 million, comprising approximately $252 million cash and Saturn shares with a deemed value of $50 million. The cash portion will be funded through cash on hand and a draw on Saturn's credit facility.
When is Saturn Oil & Gas expected to close the Corex acquisition?
Saturn expects the Corex acquisition to close in December 2026, subject to required court, regulatory and stock exchange approvals and other customary closing conditions.
When will Saturn Oil & Gas provide its 2027 guidance after the Corex deal?
Saturn expects to issue its full 2027 capital budget, program and guidance concurrently with, or shortly after, acquisition closing in the first half of December.