
Bonterra Releases Robust Preliminary Economic Assessment for the Barry Project, Highlighted by After-Tax NPV of C$665 Million and IRR of 54% at US$3,500/oz Long-Term Gold Price
The toll-milling scenario estimates average annual after-tax free cash flow of C$92 million on a 100% project basis.
Sentiment and the balance of points
Rhea-AI Sentiment reads the wording of the document, how positive or negative its language is on a 1 to 5 scale. The balance of points shown with the takes weighs what the document actually discloses, so the two can disagree, for example when a trial that missed its main goal is described in upbeat language.
Rhea-AI Summary
Bonterra Resources (BONXF) released a preliminary economic assessment for Barry estimating C$665 million in after-tax net present value. The estimate uses a 5% discount rate and US$3,500/oz gold; after-tax internal rate of return is 54%, with a 2.5-year payback. These modeled returns are on a 100% project basis, not Bonterra's ownership share.
The toll-milling scenario estimates 696,772 payable gold ounces, averaging 87,097 ounces annually. Initial capital is C$118.7 million, sustaining capital C$354.3 million and closure costs C$7.3 million; all-in sustaining costs are C$3,017/oz. Gold Fields can earn 70% through C$30 million in work expenditures. Neither Gold Fields nor Windfall Mining has endorsed the assessment, which is not an approved joint-venture development decision. Implementation assumes access to infrastructure, permits and third-party arrangements.
How this balance works
Rhea-AI gives every point it takes from this document a weight. Minor counts 1, Moderate 3 and Major 9, so one Major point outweighs several Minor ones. The bar adds up the weights on each side, and when neither side holds more than 65% of the total the balance reads Mixed.
It reads the document as published, with the same rules for every company, and it does not look at what the market expected or at how the stock traded, so a point can be objectively good on a day the stock falls.
Rhea-AI Sentiment measures something else, the tone of the wording.
Hollow bars mark forward-looking points. How the balance works
Positive
- Major point. Forward-looking: it has not happened yet and may not happen.Barry's preliminary assessment estimates C$665 million after-tax net present value at 5%, using US$3,500/oz gold.
- Moderate pointGold Fields' earn-in requires C$30 million in work expenditures, with a C$10 million annual minimum over three years.
- Minor point. Forward-looking: it has not happened yet and may not happen.Modeled after-tax returns include 54% internal rate of return and a 2.5-year payback.
- Minor point. Forward-looking: it has not happened yet and may not happen.Modeled payable production totals 696,772 gold ounces, averaging 87,097 ounces annually on a 100% project basis.
- Minor point. Forward-looking: it has not happened yet and may not happen.Modeled mill feed totals 8.4 million tonnes at 2.79 g/t gold, with 93.0% recovery.
6 minor points
- Minor point. Forward-looking: it has not happened yet and may not happen.Modeled mine life is 7.2 years, combining open-pit and underground mining.
- Minor point. Forward-looking: it has not happened yet and may not happen.Modeled life-of-mine revenue totals C$3,292 million on a 100% project basis.
- Minor point. Forward-looking: it has not happened yet and may not happen.Modeled after-tax free cash flow totals C$827 million, averaging C$92 million annually.
- Minor point. Forward-looking: it has not happened yet and may not happen.At US$4,100/oz gold, estimated after-tax net present value is C$976 million and internal rate of return 77%.
- Minor point. Forward-looking: it has not happened yet and may not happen.Bonterra identifies expansion potential: the mine plan includes only approximately 40% of February 2026 resource gold ounces.
- Minor pointBarry mineralization has been identified more than 100 meters beyond the mineral resource estimate boundary.
Negative
- Moderate point. Forward-looking: it has not happened yet and may not happen.Development depends on infrastructure availability, approvals, essential permits and third-party arrangements.
- Moderate point. Forward-looking: it has not happened yet and may not happen.Gold Fields can acquire 70% of Barry by completing the earn-in expenditures.
- Moderate point. Forward-looking: it has not happened yet and may not happen.Estimated initial capital is C$118.7 million, including C$23.7 million contingency.
- Moderate point. Forward-looking: it has not happened yet and may not happen.Estimated cash costs are C$2,411/oz; all-in sustaining costs are C$3,017/oz.
- Moderate point. Forward-looking: it has not happened yet and may not happen.At US$2,500/oz gold and a 1.35 exchange-rate assumption, modeled after-tax net present value falls to C$71 million.
- Moderate point. Forward-looking: it has not happened yet and may not happen.At 140% operating and capital costs, modeled after-tax net present value at 5% is negative C$10 million.
6 minor points
- Minor pointThe preliminary assessment is not an approved joint-venture program, budget or development decision.
- Minor pointGold Fields and Windfall Mining have not verified, approved or endorsed the assessment or development scenario.
- Minor point. Forward-looking: it has not happened yet and may not happen.Estimated sustaining capital is C$354.3 million over the project's life.
- Minor point. Forward-looking: it has not happened yet and may not happen.Estimated site closure costs are C$7.3 million.
- Minor point. Forward-looking: it has not happened yet and may not happen.Estimated life-of-mine operating costs total C$1,682 million on a 100% project basis.
- Minor point. Forward-looking: it has not happened yet and may not happen.Estimated royalty costs, including buyback, total C$66 million.
AI-generated analysis. How Rhea-AI works. Not financial advice.


Val-d'Or, Quebec--(Newsfile Corp. - October 14, 2026) - Bonterra Resources Inc. (TSXV: BTR) (OTCQB: BONXF) (FSE: 9BR2) ("Bonterra" or the "Company") is pleased to announce robust results from the independent preliminary economic assessment ("PEA") on the Barry open pit and underground project (the "Project") in the Urban-Barry Camp in northern Quebec. The PEA has been prepared by BBA Consultants ("BBA") in accordance with National Instrument 43-101 - Standards of Disclosure for Mineral Projects ("NI 43-101"). The PEA is based on the recent mineral resources estimate that was prepared by P&E Mining Consultants Inc. (see press release dated February 23, 2026). BBA has independently reviewed and endorsed the mine engineering and cost estimates as used in the PEA. The Project is under a definitive earn-in and joint venture agreement (the "JV Agreement") with Gold Fields Limited ("Gold Fields"). Under the JV Agreement, Gold Fields, through its affiliate Windfall Mining Group Inc. ("Windfall Mining"), has the right to acquire a
PEA Highlights (
- Long-term gold price per ounce ("oz"): US
$3,500 - Exchange rate: C
$1.00 = US$0.74 - After-tax net present value ("NPV") at a
5% discount rate: C$665 million - After-tax internal rate of return ("IRR"):
54% - Initial capital costs: C
$119 million - Sustaining life of mine ("LOM") capital costs: C
$354 million - Total mill feed: 8.4 million tonnes ("Mt") at 2.79 grams-per-tonne gold ("g/t Au")
- LOM average annual payable gold: 87,097 oz
- LOM Open pit strip ratio (waste: mined resource): 6.7:1
- LOM total production: 696,772 oz (
93.0% mill recovery) - LOM cash costs: C
$2,411 /oz (US$1,786 /oz) - LOM all-in sustaining costs ("AISC"): C
$3,017 /oz (US$2,235 oz)
Cesar Gonzalez, Executive Chairman and Interim CEO commented: "Bonterra's PEA demonstrates the potential economic viability and robustness of the Project in a conceptual case based on a toll-milling operating model and on a
Overview
The Project is located 110 kilometers ("km") east of Lebel-sur-Quévillon, which is 150 km to the city of Val d'Or, in the mining-friendly province of Quebec, within the Abitibi Greenstone Belt. Past production occurred in 2006-2008 at Barry where over 600,000 tonnes were processed at the Bachelor Mill, producing over 43,000 ounces of gold. In 2018, Bonterra constructed an underground exploration ramp extending to 100 m below the surface. The PEA assumes the availability of certain existing infrastructure and the ability to obtain or maintain the approvals, mining lease, essential permits and third-party arrangements required to implement the development scenario. No assurance is provided that those assumptions will be realized or that the development scenario will be approved or implemented.
Mine Plan and Production Overview
Bonterra's PEA mine plan contemplates eight years of mine operations, during which approximately 700,000 ounces of gold are expected to be produced. It also contemplates mining using a combination of underground and open pit methods (see Figure 1), with the extracted mineralized material processed at a nearby toll-milling facility. The open pit and underground mine plans were evaluated using DeswikTM algorithms to create optimal mineable shapes based on economic and technical parameters such as mine dilution and recovery.
Open pit mine design consists of 10.0 m high benches with an overall slope angle of 45 degrees. Proposed production totals 4.9 Mt, along with 33.0 Mt of overburden and waste rock, leading to a LOM strip ratio of 6.7. The open pit operation has an average mined grade of 1.9 g/t Au, resulting in total contained gold production of more than 302,000 ounces. The PEA contemplates underground mining continuing throughout the open pit mining operations. The underground mine plan comprises 3.4 Mt of mineralized material mined at an average grade of 4.05 g/t Au, containing approximately 448,000 ounces of gold. The contemplated underground mining methods consist of a combination of long-hole mining and modified cut and fill operation. The metallurgical information presented in the PEA was based, among other sources, on historical production data from Barry open pit mineralized material processed at Bachelor Mill.
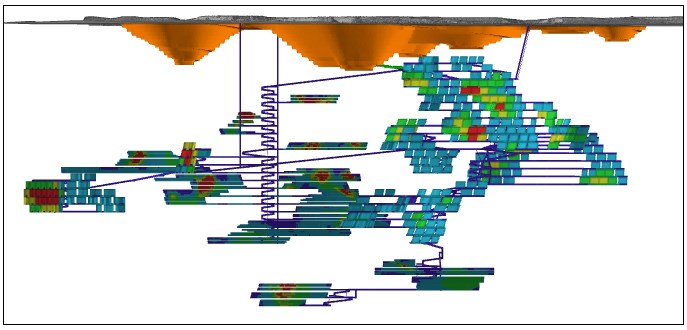
Figure 1: Longitudinal section showing PEA Open pit and Underground Stoping
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/1528/318781_42004efbc48ca92a_001full.jpg
Base Case
The economic analysis was conducted using a
Base Case PEA Summary (
| Description | Unit | Value |
| Total Tonnes Mined (Open Pit and Underground) | Mt | 8.4 |
| Average Diluted Gold Grade | g/t | 2.79 |
| Total Gold Contained | oz | 749,944 |
| Overall Gold Recovery | % | 93.0 |
| Total Gold Payable | oz | 696,772 |
| Mine Life | years | 7.2 |
| Average Annual Gold Produced | Au oz per year | 87,097 |
| Long Term Gold Price | US$/oz | 3,500 |
| Exchange Rate | CAD: USD | 0.74 |
| Discount Rate | % | 5 |
| Total LOM Revenue | C$M | 3,292 |
| Total Royalty Costs (including buyback) | C$M | 66 |
| Total LOM Operating Costs | C$M | 1,682 |
| Total Initial Capital | C$M | 119 |
| Cash Cost per ounce | C$/oz | 2,411 |
| Total LOM Sustaining Costs | C$M | 354 |
| All-in-Sustaining Capital (AISC) | C$/oz | 3,017 |
| Total LOM Pre-tax Cash Flow | C$M | 1,183 |
| Average Annual Pre-tax Cash Flow | C$M | 131 |
| Total LOM After-tax Free Cash Flow | C$M | 827 |
| Average Annual After-tax Free Cash Flow | C$M | 92 |
| After-tax Summary | ||
| After-tax NPV | C$M | 665 |
| After-tax IRR | % | 53.5 |
| After-tax Payback | years | 2.5 |
Capital and Operating Costs
The initial capital cost for the Project is estimated at C
The sustaining capital cost is estimated at C
The total capital cost for the project is estimated at C
Barry Capital Cost Summary (
| Capital Cost Description | CAPEX C$M |
| General and Civil | 33.4 |
| Infrastructures | 42.4 |
| Indirect Costs | 19.2 |
| Contingency | 23.7 |
| Initial CAPEX | 118.7 |
| Sustaining Capex | 354.3 |
| Site Closure Costs | 7.3 |
| Total | 480.3 |
Project Operating Cost Summary (
| Operating Cost Description | Unit | Cost |
| Mining - Open pit | C$/t milled | 73.33 |
| Mining - Underground | C$/t milled | 199.28 |
| Processing | C$/t milled | 44.56 |
| Transport & Refining | C$/t milled | 10.41 |
| G&A | C$/t milled | 20.86 |
| Total | C$/t milled | 200.95 (1) |
(1) Weighted average between OP and UG mining cost.
Cash Cost and All in Sustaining Costs Summary (
| Cash and AISC Costs | Unit | Cost |
| Cash Cost | C$/oz | 2,411 |
| AISC | C$/oz | 3,017 |
| Cash Cost | US$/oz | 1,786 |
| AISC | US$/oz | 2,235 |
Sensitivity Analysis
A financial sensitivity analysis was conducted on the PEA, after-tax NPV and IRR of the Project, using the following variables: capital costs, CAD: USD exchange rate and the price of gold. The after-tax results for the Project IRR and NPV
NPV Sensitivity Results (after-tax) for Gold Price and Exchange Rate Variations
(
| NPV@ | |||||
| Gold Price | US | US | US | US | US |
| Exchange Rate | |||||
| 1.43 | 190 | 493 | 774 | 1,046 | 1,313 |
| 1.41 | 163 | 469 | 747 | 1,016 | 1,279 |
| 1.39 | 133 | 445 | 720 | 985 | 1,246 |
| 1.37 | 102 | 421 | 692 | 955 | 1,212 |
| 1.35 | 71 | 397 | 665 | 925 | 1,179 |
| 1.33 | 39 | 373 | 638 | 895 | 1,145 |
| 1.31 | 8 | 348 | 610 | 864 | 1,112 |
| 1.29 | (23) | 324 | 583 | 833 | 1,078 |
| 1.27 | (54) | 299 | 555 | 802 | 1,044 |
NPV Sensitivity Results (after-tax) for Capital and Operating Costs Variations
(
| NPV@ | |||||||||
| CAPEX | |||||||||
| OPEX | |||||||||
| 1,340 | 1,332 | 1,323 | 1,315 | 1,306 | 1,297 | 1,289 | 1,280 | 1,271 | |
| 1,180 | 1,171 | 1,163 | 1,154 | 1,146 | 1,137 | 1,128 | 1,120 | 1,111 | |
| 1,020 | 1,011 | 1,003 | 994 | 986 | 977 | 968 | 960 | 951 | |
| 860 | 851 | 843 | 834 | 826 | 817 | 808 | 799 | 791 | |
| 699 | 691 | 682 | 674 | 665 | 657 | 648 | 639 | 631 | |
| 539 | 531 | 522 | 514 | 505 | 497 | 488 | 479 | 470 | |
| 379 | 371 | 362 | 354 | 345 | 336 | 328 | 319 | 310 | |
| 219 | 210 | 202 | 193 | 185 | 176 | 167 | 159 | 150 | |
| 59 | 50 | 42 | 33 | 25 | 16 | 7 | (1) | (10) | |
The sensitivity analysis reveals that the price of gold has the most significant influence on both NPV and IRR. After the price of gold, the NPV and IRR were most impacted by the OPEX and to a lesser extent by variation in capital costs and exchange rate.
Mineral Resources
The Company notes that mineral resources are not mineral reserves as they do not have demonstrated economic viability. The Company further notes that a PEA is preliminary in nature and may include inferred mineral resources that are considered too speculative geologically to have economic consideration applied to them that would enable them to be categorized as mineral reserves, and there is no certainty that the PEA will be realized. All figures are stated in Canadian dollars unless otherwise stated.
Phoenix JV
Under the JV Agreement, Gold Fields has the right to acquire a
This news release, including the PEA disclosed herein, has been prepared solely by the Company and is based on information available to the Company as of the date hereof. Neither Gold Fields nor its affiliate Windfall Mining participated in the preparation of, or has verified, approved, or endorsed the PEA or the content of this news release, and no representation or warranty is made by Gold Fields or Windfall Mining with respect thereto. References to the Phoenix Joint Venture are provided for contextual purposes only and should not be construed as statements made by, or on behalf of, Gold Fields or Windfall Mining.
Bonterra's PEA does not constitute an approved program, budget or development decision under the JV Agreement. Nothing in this news release should be interpreted as indicating that Gold Fields or Windfall Mining intends to pursue, fund or implement the mine plan or development scenario described in the PEA. If Gold Fields completes the earn-in, future exploration, evaluation and development activities will be determined in accordance with the applicable governance, operatorship and approval provisions of the JV Agreement.
QUALIFIED PERSONS
The PEA production scenario is based on the Measured, Indicated and Inferred mineral resources from the 2026 MRE issued on February 23, 2026. The PEA was prepared by the following Qualified Persons as defined by NI 43-101: Gabriel Monty, P.Eng.; Vera Gella, P.Eng.; Benoit Ouellet, P.Eng. Hugo Latulippe, P.Eng, of BBA Consultants; and Antoine Yassa, P.Geo. OGQ of P&E Mining Consultants Inc. as it relates to MREs, all each of whom are independent of the Company in accordance with NI 43-101. They are not aware of any environmental, permitting, legal, title, taxation, socio-economic, marketing, political, or other relevant factors that could materially affect the results of the PEA. The Qualified Persons have reviewed, verified, and approved the scientific and technical data for which they have responsibility contained in this news release pertaining to the PEA.
The full technical report, which is being prepared in accordance with NI 43-101 - Standards of Disclosure for Mineral Projects will be available on SEDAR+ (www.sedarplus.com) under the Company's issuer profile within 45 days from this news release. The effective date of the PEA is October 8, 2026.
About Bonterra Resources Inc.
Bonterra is a Canadian gold exploration company with a portfolio of advanced exploration assets anchored by a central milling facility in Quebec, Canada. The Company's assets include the Gladiator, Barry(1), Moroy, and Bachelor(2) gold deposits, which collectively hold 16.8 million tonnes ("Mt") at an average grade of 3.02 g/t Au for 1.63 million ounces ("Moz") of Measured & Indicated Mineral Resources, plus 15.6 Mt at 4.32 g/t Au for 2.17 Moz of Inferred Mineral Resources.
In November 2023, the Company entered into an earn-in and joint venture agreement with Osisko Mining Inc. ("Osisko Mining") for the Urban-Barry properties (the "JV Agreement"), which include the Gladiator and Barry deposits. In October 2024, Gold Fields Ltd, through a wholly owned Canadian subsidiary Windfall Mining Group Inc., completed the acquisition of Osisko Mining for C
1) See news release of the Company dated February 23, 2026, and titled "Bonterra Reports Significant Mineral Resources Growth at Barry and Gladiator Deposits" for further details.
2) See news release of the Company dated April 1, 2026, and titled "Bonterra Reports Significant Mineral Resource Growth at Bachelor and Moroy,
FOR ADDITIONAL INFORMATION
Cesar Gonzalez, Executive Chairman & Interim CEO
ir@btrgold.com
2872 Sullivan Road, Suite 2, Val d'Or, Quebec J9P 0B9
819-825-8678 | Website: www.btrgold.com
Neither TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
Cautionary and Forward-Looking Statements
The reader is advised that the PEA summarized in this press release is intended to provide only an initial, high-level review of the Project potential and design options. The PEA mine plan and economic model include numerous assumptions and the use of Inferred resources. Inferred resources are considered to be too speculative to be used in an economic analysis except as allowed for by Canadian Securities Administrators' National Instrument 43-101 in PEA studies. There is no guarantee that Inferred resources can be converted to Indicated or Measured resources, and as such, there is no guarantee the Project economics described herein will be achieved.
This news release contains "forward-looking information" within the meaning of the applicable Canadian securities legislation that is based on expectations, estimates, projections and interpretations as at the date of this news release. Any statement that implies predictions, expectations, interpretations, opinions, plans, projections, objectives, assumptions, future events or performance (often using words such as "expects" or "does not expect", "is expected", "interpreted", "in management's opinion", "anticipates", or "plans", "budget", "schedule", "intends", "forecasts", "estimates", "believes", or variations of such words and phrases or statements that certain actions, events or results "may", "could", "should", "would", "might" or "will" be taken, occur or be achieved) is not a statement of historical fact and may constitute forward-looking information and is intended to identify forward-looking information. This news release may contain forward-looking information relating to, among other things, the outlook for the Barry, Gladiator, Moroy and Bachelor projects; updated mineral resources, Barry Open Pit PEA; the deposit remaining open laterally and at depth; and future drilling. These factors include, but are not limited to, risks associated with the ability of exploration activities (including drilling results) to accurately predict mineralization; the Company's ability to obtain required approvals; the results of exploration activities; risks associated with mining operations; global economic conditions; metal prices; dilution; environmental risks; and community and non-governmental actions. Although the forward-looking information contained in this news release is based on assumptions that management believes are reasonable at the time of release, Bonterra cannot assure shareholders and prospective purchasers of the Company's securities that actual results will be consistent with the forward-looking information, as there may be other factors that cause results not to be as anticipated, estimated or intended, and neither Bonterra nor any other person assumes responsibility for the accuracy or completeness of forward-looking information. All statements made, other than statements of historical fact, that address the Company's intentions and the events and developments that the Company anticipates, are considered forward-looking statements. Although the Company believes that the expectations expressed in such forward-looking statements are based on reasonable assumptions, such statements are not guarantees of future performance, and actual results or developments may differ from those in the forward-looking statements.
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/318781
FAQ
AI-generated questions and answers. How Rhea-AI works. Not financial advice.
What are the main economic results of Bonterra's Barry preliminary assessment?
Barry's preliminary assessment estimates C$665 million after-tax net present value at a 5% discount rate, using US$3,500/oz gold. The modeled after-tax internal rate of return is 54%, with a 2.5-year payback. These figures cover 100% of the project rather than Bonterra's ownership share.
How would Barry development decisions be made if Gold Fields completes its earn-in?
If Gold Fields completes the earn-in, future exploration, evaluation and development activities will follow the joint-venture agreement's governance, operatorship and approval provisions. The assessment does not indicate that Gold Fields or Windfall Mining intends to pursue, fund or implement the proposed mine plan.
When will Bonterra publish the full Barry preliminary assessment technical report?
Bonterra expects the full technical report to be available on SEDAR+ under its issuer profile within 45 days of the October 14, 2026 announcement. The preliminary assessment's effective date is October 8, 2026.