
PMET Resources Delivers Enhanced CV5 Lithium-Tantalum Feasibility Study
The revised plan adds tantalum recovery and starts with higher-grade underground ore, while using a higher lithium price assumption.
Sentiment and the balance of points
Rhea-AI Sentiment reads the wording of the document, how positive or negative its language is on a 1 to 5 scale. The balance of points shown with the takes weighs what the document actually discloses, so the two can disagree, for example when a trial that missed its main goal is described in upbeat language.
Rhea-AI Summary
PMET Resources (PMETF) completed an updated CV5 lithium-tantalum feasibility study projecting an after-tax net present value of approximately CA$5.10 billion. At an 8% discount rate, that valuation assumes spodumene at US$1,788/t and tantalum at US$120/lb; the projected after-tax return is 40.4%. At approximately US$1,400/t spodumene, the valuation is approximately CA$3.29 billion.
The plan starts underground mining before adding open-pit production, with concentrate capacity rising to approximately 800,000 tonnes annually. Probable reserves total 83.0 million tonnes grading 1.27% lithium oxide and 148 ppm tantalum pentoxide. Estimated cash operating costs fall 19% versus the 2025 study, including tantalum credits and excluding royalties. Initial capital is CA$1,391 million, with CA$672 million for expansion. PMET targets commissioning from late 2029; a final investment decision and mine authorisation remain pending.
How this balance works
Rhea-AI gives every point it takes from this document a weight. Minor counts 1, Moderate 3 and Major 9, so one Major point outweighs several Minor ones. The bar adds up the weights on each side, and when neither side holds more than 65% of the total the balance reads Mixed.
It reads the document as published, with the same rules for every company, and it does not look at what the market expected or at how the stock traded, so a point can be objectively good on a day the stock falls.
Rhea-AI Sentiment measures something else, the tone of the wording.
Hollow bars mark forward-looking points. How the balance works
Positive
- Major point. Forward-looking: it has not happened yet and may not happen.After-tax value at an 8% discount rate rises 220% versus 2025 to CA$5,100 million.
- Moderate point. Forward-looking: it has not happened yet and may not happen.CA$593.5/t life-of-mine cash operating cost falls 19% versus 2025, net of tantalum credits; excludes royalties.
- Moderate pointMaiden tantalum probable reserve accompanies 83.0 Mt grading 1.27% lithium oxide and 148 ppm tantalum pentoxide.
- Minor point. Forward-looking: it has not happened yet and may not happen.After-tax internal rate of return increases to 40.4% from 18.1% in the 2025 study.
- Minor point. Forward-looking: it has not happened yet and may not happen.After-tax payback shortens to 2.7 years from 4.7 years in the 2025 study.
9 minor points
- Minor point. Forward-looking: it has not happened yet and may not happen.Approximately CA$3.29 billion after-tax value at an 8% discount rate is projected at approximately US$1,400/t spodumene.
- Minor point. Forward-looking: it has not happened yet and may not happen.CA$657/t life-of-mine all-in sustaining cost falls 18%, net of tantalum credits; excludes royalties.
- Minor point. Forward-looking: it has not happened yet and may not happen.CA$849.1 million sustaining cost decreases 9% from CA$936.4 million in the 2025 study.
- Minor point. Forward-looking: it has not happened yet and may not happen.Phase 1 production is planned to ramp to approximately 560,000 tonnes annually within the first three production years.
- Minor point. Forward-looking: it has not happened yet and may not happen.Phase 2 capacity is planned to reach up to approximately 800,000 tonnes of spodumene concentrate annually.
- Minor point. Forward-looking: it has not happened yet and may not happen.Tantalum output is projected to average approximately 635,000 pounds annually of contained tantalum pentoxide over mine life.
- Minor point. Forward-looking: it has not happened yet and may not happen.Phase 1 tantalum output is projected at up to approximately 455,000 pounds annually of contained tantalum pentoxide.
- Minor point. Forward-looking: it has not happened yet and may not happen.Underground-first development targets plant commissioning from the latter part of 2029.
- Minor point. Forward-looking: it has not happened yet and may not happen.Alternative development assessment is targeted this quarter, evaluating CV5 and CV13 for lithium, caesium and tantalum.
Negative
- Major point. Forward-looking: it has not happened yet and may not happen.CA$1,391 million initial capital is required; CA$1,080 million is net of anticipated pre-production and tax credits.
- Moderate point. Forward-looking: it has not happened yet and may not happen.CA$672 million expansion capital is required; CA$595 million is net of anticipated tax credits.
- Moderate pointFinal investment decision remains outstanding and is targeted for late 2027.
- Moderate pointFinal mine authorisation is still being sought under the existing environmental and social assessment framework.
- Minor point. Forward-looking: it has not happened yet and may not happen.Phase 1 capital net of pre-production credit rises 1% versus 2025; Phase 2 capital rises 7%.
- Minor pointUS$1,788/t spodumene assumption is 46% above the 2025 study assumption, contributing to improved economics.
AI-generated analysis. How Rhea-AI works. Not financial advice.


Derisked and improved development scenario delivers lower operating cost and stronger Project economics at Shaakichiuwaanaan
- New Feasibility Study ("FS") development scenario pursues higher-grade underground operations first, introduces tantalum recovery and higher phase 1 production capacity, materially reducing LOM1 operating cost and improving overall Project economics:
19% lower average LOM Total Cash Operating Cost (FOB Quebec ports)2 = CA$594 /t (US /t) (net of CA$433 $148 /t orUS /t tantalum credit);$108 18% lower average LOM AISC (FOB Quebec ports)3 = CA$657 /t (US /t) (net of tantalum credit);$480 - CAPEX similar to the prior lithium-only FS study despite the additional tantalum scope, with optimisation work offsetting broader inflationary pressures:
- Initial CAPEX (Phase 1 – 2.2 Mtpa processing capacity) = CA
$1,391M (CA$1,080M net of anticipated pre-production credit and tax credits4; and - Expansion CAPEX (Phase 2 – combined 5.1 Mtpa processing capacity) = CA
$672M (or CA$595M net of anticipated tax credits).
- Initial CAPEX (Phase 1 – 2.2 Mtpa processing capacity) = CA
- After-tax NPV
8% of ~CA$5.10B (US ) and IRR of ~$3.72B 40.4% , at a long-term spodumene price ofUS /t (SC5.5 basis and FOB Quebec ports) (using Benchmark Minerals base case data) and tantalum price of$1,788 US /lb (contained Ta2O5 basis) (OnG Commodities); and$120 - After-tax NPV
8% of ~CA$3.29B (US ) at near broker consensus spodumene pricing of$2.40B ~US /t (SC5.5 basis).$1,400
- The Updated CV5 Lithium-Tantalum FS establishes a highly competitive lithium–tantalum base case for a large-scale, economically robust and long-life critical minerals operation in the Eeyou Istchee James Bay Region of
Québec . - Updated Project scope:
- Hybrid mining operation combining high-grade underground mining (Phase 1) and low strip ratio (3.5 over LOM) open-pit mining (introduced for Phase 2);
- Two process plants for Phase 1 and Phase 2, with up to 5.1 Mtpa combined ore feed capacity via DMS5-only processing; and
- Introduction of a tantalum recovery circuit expected to yield a significant co-product credit to spodumene production, further improving early Project cashflow and economics.
- Higher Phase 1 annual production, ramping up to ~560,000 tpa of spodumene concentrate (SC5.5) in the first 3 years of production6:
- Underground mining commences first, providing access to the high-grade Nova Zone7 from the onset, resulting in more spodumene concentrate produced from lower tonnages processed (2.2 Mtpa); and
- Streamlined high-grade single-stage DMS-only process flowsheet for Phase 1 reduces initial plant footprint while targeting higher lithium recoveries.
- Phase 2 ramps production capacity to up to ~800,000 tpa of spodumene concentrate (SC5.5), with Phase 1 and 2 over LOM of ~20 years.
- Average LOM yearly production of tantalite concentrate ~635,000 lbs per year (contained Ta2O5) for Phase 1 and 2 and up to ~455,000 lbs per year of contained Ta2O5 in Phase 1.
- Maiden tantalum Mineral Reserve declared and lithium Mineral Reserve largely unchanged:
- 83.0 Mt at
1.27% Li2O and 148 ppm Ta2O5 (Probable).
- 83.0 Mt at
- Derisked execution strategy - Underground first providing early access to the high-grade Nova Zone is expected to derisk Phase 1 execution and seasonality risk, targeting plant commissioning from the latter part of 2029.
- The Company is targeting the release of a Preliminary Economic Assessment ("PEA") this quarter, exploring an alternative development scenario inclusive of both CV5 and CV13 and on three commodities – lithium, caesium, and tantalum.
|
____________ |
|
1 LOM = Life of Mine |
|
2 Total cash operating cost (FOB Quebec ports) includes mining, processing, site administration, and product transportation costs to a port in |
|
3 All-in sustaining costs ("AISC") (FOB Quebec ports) includes mining, processing, site administration, and product transportation costs to a port in |
|
4 Tax credits means Canadian Clean Technology Manufacturing - Investment Tax Credits ("CTM-ITC" (enacted on June 20, 2024) which provides for up to |
|
5 DMS = Dense Media Separation |
|
6 Refer to Figure 5 for further details of the spodumene concentrate production schedule. |
|
7 The high-grade Nova Zone has been traced over a strike length of approximately 1.5 km and includes multiple drill intersections ranging from 2 m to 25 m (core length) at > |
Ken Brinsden, PMET Resources CEO and President, comments: "The Updated CV5 Feasibility Study marks an important step forward for Shaakichiuwaanaan. It demonstrates greatly improved economics, a stronger Phase 1 production profile, a more advanced and substantially de-risked execution plan to underpin an upcoming Final Investment Decision, targeted for late 2027. By bringing forward higher-grade Nova Zone material, simplifying the DMS-only flowsheet and incorporating tantalum recovery from the outset, we have materially lowered our costs and enhanced the Project's value.
"The declaration of a maiden Probable Mineral Reserve for tantalum further highlights the strategic importance of Shaakichiuwaanaan as a globally significant critical-minerals asset.
"Furthermore, our upcoming PEA will evaluate an integrated development scenario for the recovery of all 3 critical minerals - lithium, tantalum, and caesium - from a project combining both CV5 and our higher grade CV13 Deposit. We expect this work to build on the improved development scenario outlined in this Updated FS and further demonstrate the scale, optionality, and distinctive multi-commodity potential of our – truly unique – Shaakichiuwaanaan Project," added Mr. Brinsden
PMET Resources Inc. (the "Company" or "PMET") (TSX: PMET) (ASX: PMT) (OTCQX: PMETF) (FSE: R9GA) is pleased to announce the results of its Updated CV5 Feasibility Study ("Updated FS") at the Company's wholly owned Shaakichiuwaanaan Property (the "Property" or "Project") located in the Eeyou Istchee James Bay region of
The Updated FS is underpinned by a Mineral Reserve derived from the CV5 Pegmatite's Indicated Mineral Resource component, part of the current Shaakichiuwaanaan Consolidated Mineral Resource Estimate ("MRE"), which is one of the top 10 largest known lithium pegmatite MREs globally (see news release dated November 3 2026).
While a final investment decision ("FID") has yet to be made for the Shaakichiuwaanaan Project, the Updated FS reaffirms the CV5 Pegmatite's potential to position the Company as a globally significant spodumene concentrate producer and it firmly demonstrates its potential to become a top-tier tantalum concentrate producer.
This announcement has been prepared in accordance with the JORC Code (2012) and the ASX Listing Rules. A technical report prepared in accordance with National Instrument 43-101 - Standards of Disclosure for Mineral Projects ("NI 43-101"), detailing the Updated FS and the MRE, will be filed on SEDAR+ within 45 days of this announcement.
Unless otherwise indicated, all references to "$" or "CA$" in this release are to Canadian dollars and references to "US$" in this release are to US dollars. A foreign exchange conversion rate of 1.37 CA$/US$ has been used over the LOM.
EXECUTIVE SUMMARY
SCOPE
The Updated FS outlines an improved development scenario for the Project inclusive of lithium and tantalum production at CV5, working within the constraints of the scope established under the Company's existing Environmental and Social Impact Assessment ("ESIA"). Building on the Company's 2025 Lithium-Only Feasibility Study on CV5, it retains the hybrid underground ("UG") and open-pit ("OP") mining model while incorporating production of tantalum alongside that of lithium to maximise the value of the Mineral Resource.
The ESIA filed in March 2026 established the broad development scope for which final mine authorisation is being sought, including processing capacity of up to 5.1 Mtpa. The Updated FS now optimises the phased development case within this existing ESIA authorisation framework, accessing and leveraging the high-grade UG Nova Zone earlier. This improves early years cashflow generation while preserving optionality and flexibility over time to unlock the full potential of the Shaakichiuwaanaan Project and potentially position it as a leading, low-cost lithium and tantalum raw materials supplier to North American, European, and Asian markets.
CONTRIBUTING SPECIALIST CONSULTANTS/ADVISORS
The Company engaged external consultant, BBA Consultants, as lead consultant, with contributions from Primero Group Americas Inc., AtkinsRéalis Group Inc., Vision Geochemistry Ltd., Alius Mine Consulting, WSP Canada Inc., Mailloux Hydrogéologie, and CGM Expert, to prepare an independent Updated Feasibility Study and Technical Report for the CV5 Pegmatite (lithium-tantalum) at the Shaakichiuwaanaan Project.
STUDY OUTCOMES
The Updated FS reaffirms that the CV5 Pegmatite, with a nameplate design production rate of up to 800,000 tonnes per annum of SC5.5 spodumene concentrate, positioning PMET as a globally significant spodumene concentrate producer. With planned ore processing capacity of up to 5.1 Mtpa and production spanning approximately 20 years, the Project is set to become a large-scale, long-life lithium pegmatite operation. Further, the Updated FS establishes the potential for PMET to produce tantalum as a valuable co-product to the lithium operation and therefore also become a globally significant tantalum producer.
Through the application of the tantalum revenue as a credit to its spodumene concentrate production, Shaakichiuwaanaan materially improves on its overall competitive cost position, with a projected LOM AISC (FOB Quebec ports)8 of ~CA
The Updated FS delivers an after-tax NPV
Importantly, the Updated FS reaffirms that Shaakichiuwaanaan's CV5 is both technically feasible and economically viable and positions the Project to become a cornerstone supplier to the North American, European, and Asian critical minerals supply chains. The combination of scale, longevity, and cost competitiveness, together with the ability to supply a coarse, high-quality SC5.5 spodumene concentrate from a DMS only operation alongside a
|
__________ |
|
8 AISC (FOB Quebec ports) includes mining, processing, site administration, and product transportation costs to a port in |
Table 1: Summary of Estimated Project Economics
|
Financial Results |
Unit |
CA$ |
US$ |
|
Long-term spodumene concentrate price assumption ( |
$/t |
2,450 |
1,788 |
|
Long-term tantalite concentrate price assumption (contained Ta2O5) |
$/lb |
164 |
120 |
|
Pre-Tax NPV |
M$ |
20,793 |
15,178 |
|
Pre-Tax NPV |
M$ |
8,461 |
6,176 |
|
After-Tax NPV |
M$ |
12,538 |
9,152 |
|
After-Tax NPV |
M$ |
5,100 |
3,723 |
|
Pre-Tax IRR |
% |
47.2 % |
|
|
After-Tax IRR |
% |
40.4 % |
|
|
Pre-Tax Payback Period |
year |
2.6 |
|
|
After-Tax Payback Period |
year |
2.7 |
|
Table 2: Estimated Production Metrics
|
Key Metrics |
Unit |
Value |
|
Phase 1 (Underground) Construction and Ramp Up Phase (from breaking ground) |
year |
2.3 |
|
Life of Mine (LOM) |
year |
19 |
|
Underground |
|
|
|
Ore Mined |
Mt |
34.9 |
|
Waste Mined |
Mt |
4.8 |
|
Total Tonnes Mined |
Mt |
39.6 |
|
Open Pit |
|
|
|
Ore Mined |
Mt |
48.2 |
|
Waste Mined (including pre-stripping) |
Mt |
167.8 |
|
Total Tonnes Mined |
Mt |
215.9 |
|
LOM Open Pit Strip Ratio (waste tonnes: ore tonnes) |
w:o |
3.5:1 |
|
Total |
|
|
|
Total Mineral Reserve (Open Pit + Underground) mined and processed |
Mt |
83.0 |
|
Nominal Process Plant Feed Rate |
Mtpa |
5.1 |
|
Average Process Plant Feed Rate |
Mtpa |
4.4 |
|
Average Li2O Feed Grade |
% |
1.27 |
|
Average Li2O Recovery |
% |
69.7 |
|
LOM Spodumene Concentrate (SC5.5) |
Mt |
13.4 |
|
Spodumene Li2O Concentrate Grade |
% |
5.5 |
|
Nominal Spodumene Concentrate Production Rate |
ktpa |
800.0 |
|
LOM Average Spodumene Concentrate Production Rate |
ktpa |
702.8 |
|
Average Ta2O5 Feed Grade |
ppm |
148 |
|
Average Ta2O5 Recovery |
% |
44.6 |
|
LOM Tantalite Concentrate ( |
kt |
27.4 |
|
Tantalite Ta2O5 Concentrate Grade |
% |
20 |
|
Nominal Tantalite Concentrate Production Rate |
tpa |
1,625 |
|
LOM Average Tantalite Concentrate Production Rate |
tpa |
1,441 |
The Updated FS demonstrates a significant improvement in the Project's economics compared to the 2025 Feasibility Study (Table 3), driven by optimized operating costs, the inclusion of tantalum as a valuable by-product, and revised long-term commodity price assumptions.
Table 3: Comparison of Key metrics – Updated FS vs 2025 FS
|
Key Metrics |
Unit |
Updated FS |
FS 2025 |
Variation |
|
Long-term spodumene concentrate price assumption ( |
USD/t |
|
|
46 % |
|
Long-term tantalite concentrate price assumption (contained Ta2O5) |
USD/lbs |
|
- |
N/A |
|
Exchange rate |
CAD/USD |
1.37 |
1.34 |
2 % |
|
|
|
|
|
|
|
Pre-Tax NPV |
CA$M |
20,793 |
8,358 |
149 % |
|
Pre-Tax NPV |
CA$M |
8,461 |
2,514 |
237 % |
|
After-Tax NPV |
CA$M |
12,538 |
5,418 |
131 % |
|
After-Tax NPV |
CA$M |
5,100 |
1,594 |
220 % |
|
Pre-Tax IRR |
% |
47.2 % |
19.9 % |
138 % |
|
After-Tax IRR |
% |
40.4 % |
18.1 % |
124 % |
|
Pre-Tax Payback Period |
year |
2.6 |
4.9 |
(47 %) |
|
After-Tax Payback Period |
year |
2.7 |
4.7 |
(43 %) |
|
|
|
|
|
|
|
Phase 1 Initial Capital cost (net of pre-production credit) |
CA$M |
1,260.4 |
1,247.7 |
1 % |
|
Phase 2 Expansion Capex |
CA$M |
672.4 |
628.8 |
7 % |
|
LOM Sustaining Cost |
CA$M |
849.1 |
936.4 |
(9 %) |
|
|
|
|
|
|
|
LOM Total Cash Operating Cost (FOB Quebec ports)[9] |
CA$/t |
593.5 |
729.1 |
(19 %) |
|
LOM AISC (FOB Quebec ports)[10] |
CA$/t |
657.1 |
799.8 |
(18 %) |
The pre-tax NPV
Importantly, the Updated FS demonstrates a substantial reduction in operating costs, with LOM total cash operating costs9 decreasing by
On a like-for-like basis removing impact of lithium price and exchange rate assumptions (using FS 2025 lithium price and exchange rate), the Updated FS increases after-tax NPV
Overall, the Updated FS highlights the Project's enhanced profitability, improved cost competitiveness and stronger cash flow generation potential, further reinforcing its position as a globally significant, long-life lithium development project.
|
___________ |
|
9 Total cash operating cost (FOB Quebec ports) includes mining, processing, site administration, and product transportation costs to a port in |
|
10 AISC (FOB Quebec ports) includes mining, processing, site administration, and product transportation costs to a port in |
NEXT STEPS
The Company will continue to advance detailed engineering for the Phase 1 development. In parallel, the Company is advancing a PEA-level of assessment on an alternate development scenario inclusive of both CV5 and the Company's higher grade CV13 pegmatite for lithium, caesium, and tantalum.
To support this optimisation process and further de-risk the Project, the Company continues to advance its UG bulk sample program targeting the CV5 high-grade Nova Zone, which will provide additional data to validate key design assumptions, test product specification and quality at scale, and confirm mine plan enhancements.
In parallel, the completion of the Updated FS positions the Company to further advance its ongoing discussions with customers, strategic investors and government stakeholders, reflecting the Shaakichiuwaanaan Project's importance to develop a robust western-facing critical minerals supply chain.
The FID remains targeted for late 2027, subject to securing project approvals and funding. It will take into account detailed engineering, prevailing market conditions, and the Company's commercial relationships and customer requirements across the critical minerals supply chain.
FEASIBILITY STUDY - DISCUSSION
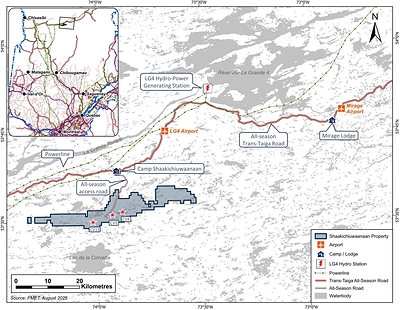
The Shaakichiuwaanaan Property is located in the Eeyou Istchee James Bay region of
The La Grande 4 ("LG-4") hydroelectric dam complex is located approximately 30 km north-northeast of the Property. The CV5 LCT Pegmatite is located central to the Property, approximately 13 km south of KM-270 on the Trans-Taiga Road, 14 km south of the powerline, and approximately 50 km southwest of the LG-4 dam complex.
The Property is situated on Category III Land within the Eeyou Istchee James Bay Territory (Cree Nation of
|
__________ |
|
11 EER = Exclusive Exploration Right (formally referred to as CDC claim) |
The Shaakichiuwaanaan Consolidated MRE, which includes the CV5, CV13, and CV4 pegmatites, has been completed in accordance with NI 43-101, and CIM Definition Standards for Mineral Resources and Reserves reporting guidelines and is presented in Table 4. As the Company is dual listed on the ASX in
Table 4: Shaakichiuwaanaan Consolidated Mineral Resource Estimate
|
Conceptual |
Pegmatite |
Classification |
Tonnes |
Li2O |
Ta2O5 |
Ga |
Contained |
Contained |
|
Open-Pit |
CV5 |
Indicated |
98,810,000 |
1.40 |
161 |
66 |
3.42 |
15.91 |
|
Underground |
4,346,000 |
1.15 |
184 |
66 |
0.12 |
0.80 |
||
|
Total |
103,156,000 |
1.39 |
162 |
66 |
3.55 |
16.71 |
||
|
Open-Pit |
CV5 |
Inferred |
4,838,000 |
1.27 |
177 |
63 |
0.15 |
0.86 |
|
Underground |
9,616,000 |
1.24 |
146 |
60 |
0.29 |
1.40 |
||
|
Total |
14,454,000 |
1.25 |
156 |
61 |
0.45 |
2.25 |
||
|
|
|
|
|
|
|
|
|
|
|
Open-Pit |
CV13 |
Indicated |
10,533,000 |
1.86 |
181 |
75 |
0.48 |
1.91 |
|
Underground |
220,000 |
0.92 |
183 |
63 |
0.01 |
0.04 |
||
|
Total |
10,753,000 |
1.84 |
181 |
74 |
0.49 |
1.95 |
||
|
Open-Pit |
CV13 |
Inferred |
14,461,000 |
1.26 |
145 |
67 |
0.45 |
2.10 |
|
Underground |
3,110,000 |
1.06 |
177 |
60 |
0.08 |
0.55 |
||
|
Total |
17,571,000 |
1.23 |
151 |
66 |
0.53 |
2.65 |
||
|
|
|
|
|
|
|
|
|
|
|
Open-Pit |
CV4 |
Indicated |
- |
- |
- |
- |
- |
- |
|
Underground |
CV4 |
Inferred |
1,748,000 |
1.24 |
91 |
59 |
0.05 |
0.16 |
|
Total |
1,748,000 |
1.24 |
91 |
59 |
0.05 |
0.16 |
||
|
|
|
|
|
|
|
|
|
|
|
|
CV5 + |
Indicated |
113,909,000 |
1.43 |
164 |
67 |
4.03 |
18.68 |
|
Inferred |
33,773,000 |
1.24 |
150 |
63 |
1.03 |
5.07 |
||
Table 5: Caesium Zone Mineral Resources within the CV13 Pegmatite.
|
Caesium |
Classification |
Tonnes |
Cs2O |
Rb2O |
Contained |
|
Rigel |
Indicated |
144,000 |
7.34 |
0.80 |
10,600 |
|
Inferred |
- |
- |
- |
- |
|
|
|
|
|
|
|
|
|
|
Indicated |
1,633,000 |
4.19 |
0.43 |
68,400 |
|
Inferred |
978,000 |
2.96 |
0.37 |
29,000 |
|
|
|
|
|
|
|
|
|
Helios |
Indicated |
67,000 |
3.35 |
0.36 |
2,200 |
|
Inferred |
3,000 |
15.16 |
0.39 |
500 |
|
|
|
|
|
|
|
|
|
Rigel + |
Indicated |
1,844,000 |
4.40 |
0.46 |
81,200 |
|
Inferred |
981,000 |
3.00 |
0.37 |
29,400 |
- Mineral Resources were prepared in accordance with NI 43-101, the CIM Definition Standards (2014), and the JORC Code (2012). Mineral Resources that are not Mineral Reserves do not have demonstrated economic viability. This estimate of Mineral Resources may be materially affected by environmental, permitting, legal, title, taxation, sociopolitical, marketing, economic, or other relevant issues.
- The independent Competent Person (CP), as defined under JORC, and Qualified Person (QP), as defined by NI 43‑101 for this resource estimate is Todd McCracken, P.Geo., Director – Mining & Geology –
Central Canada , BBA Consultants. The Effective Date of the estimate is July 10, 2026 (through drill hole CV25-1025). - Estimation was completed using a combination of inverse distance squared (ID2) and ordinary kriging (OK) for CV5 and for CV13 and inverse distance squared (ID2) for CV4 in Leapfrog Edge software with dynamic anisotropy search ellipse on specific domains.
- Drill hole composites at 1 m in length for the pegmatite domains and every 0.5 m for the caesium enriched zones (CV13). Block size is 10 m x 5 m x 5 m with sub-blocking.
- Both underground and open-pit conceptual mining shapes were applied as constraints to demonstrate reasonable prospects for eventual economic extraction. Cut-off grades for open-pit constrained resources are
0.40% Li2O for both CV5 and CV13, and for underground constrained resources are0.60% Li2O for CV5 and CV4, and0.70% Li2O for CV13. Open-pit and underground Mineral Resource constraints are based on a spodumene concentrate price ofUS /tonne ($1,500 6% basis FOB Bécancour) and an exchange rate of0.74 USD /CAD. - The cut-off grades and mining shapes are based on Li2O (%) only. All other elements are non-paid metals and estimates are reported for reference purposes only. The Caesium Zone MRE is hosted within the CV13 Pegmatite's open-pit conceptual mining shape and sub-domained using a
0.50% Cs2O grade constraint and reported at a0.50% Cs2O cut-off grade. - Rounding may result in apparent summation differences between tonnes, grade, and contained metal content.
- Tonnage and grade measurements are in metric units.
- Conversion factors used: Li2O = Li x 2.153, LCE (i.e., Li2CO3) = Li2O x 2.473, Ta2O5 = Ta x 1.221, Cs2O = Cs x 1.0602, Rb2O = Rb x 1.0936.
- Densities for pegmatite blocks (CV5, CV13, & CV4) were estimated using a linear regression function (SG = 0.0674x (Li2O% + 0.81 x B2O3%) + 2.6202) derived from the specific gravity ("SG") field measurements and Li2O grade. Non-pegmatite blocks were assigned a fixed SG based on the field measurement median value of their respective lithology.
All reported Mineral Resources have been constrained by conceptual open pit and underground mineable shapes to demonstrate reasonable prospects for eventual economic extraction ("RPEEE"). The cut-off grade ("COG") is variable depending on the mining method and pegmatite (
The Updated FS presented has been completed for lithium and tantalum only on the CV5 Pegmatite's Indicated Mineral Resource component (part of the Consolidated MRE), which totals 103.2 Mt at
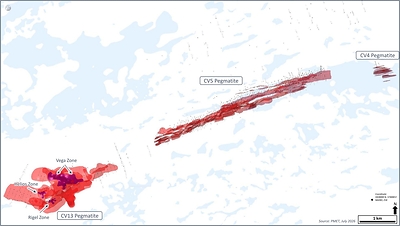
The CV5 Pegmatite is a Li-Cs-Ta (LCT) pegmatite situated central to the Property within the Guyer Greenstone Belt, considered part of the larger La Grande River Greenstone Belt, and intrudes predominantly amphibolite, metasediment, and lesser ultramafic rock types. The principal lithium mineral is spodumene which is present typically as decimetre to metre scale crystals. The principal tantalum mineral is tantalite (±columbite).
The CV5 Pegmatite, including the principal dyke, is modelled to extend continuously over a lateral distance of at least 5.0 km and remains open along strike at both ends and to depth along a large portion of its length (Figure 2). The principal dyke, comprising approximately
The Mineral Reserve for the Shaakichiuwaanaan Project is 83.0 Mt at
The mine design and Mineral Reserve Estimate for the CV5 LCT pegmatite were completed to a level appropriate for feasibility studies. The Mineral Reserves were estimated in accordance with the CIM Estimation of Mineral Resources & Mineral Reserves Best Practice Guidelines (November 29, 2019) and CIM Definition Standards for Mineral Resources and Reserves (May 10, 2014) and also comply with the JORC Code 2012.
In line with these standards, the Mineral Reserves for the CV5 LCT Pegmatite are based solely on Indicated Mineral Resources, and for lithium and tantalum only. Any Inferred Mineral Resources that fall within the mine design envelope have been treated as waste and assigned a grade of
To evaluate the potentially economical portion of the Mineral Resource Estimate, separate break-even COGs were calculated for the OP and the UG components. The calculation used OPEX reflecting current labour and fuel price, inclusive of mining, processing, G&A, concentrate transport, and royalties. The metallurgical recovery assumption followed a grade/recovery curve determined via extensive testing undertaken by SGS Canada. The COG calculations also take into account dilution and mining recovery assumptions. The resulting COGs used for the OP and the UG Mineral Reserves are
A zone-by-zone approach was applied to validate the economic viability of each area of the deposit by integrating zone-specific sustaining capital costs into the economic analysis for the UG Reserve, whereby stope clusters that did not support development costs to access them, were not converted to Reserves. The UG stopes located within the crown pillar (0-85m from lake bottom) were not converted to Reserves.
Environmental and social baseline studies and an Environmental and Social Impact Assessment (ESIA) have been submitted to federal and provincial regulators and the permitting process is ongoing. The Project is located on EERs held by the Company within
It is the opinion of the Qualified/Competent Person that the Mineral Reserve Estimate is supported by appropriate design, scheduling and costing work reported to a feasibility study level of detail. Sufficient modifying factors and economic considerations have been applied to the Indicated Mineral Resource to declare the Probable Mineral Reserve. As such, Mineral Reserves are reported commensurate with the Probable classification.
Section 4 of the JORC Code Table 1 Report is included in Appendix 2 in accordance with ASX Listing Rule 5.9.
Table 6: Shaakichiuwaanaan Mineral Reserve (CV5)
|
Area |
Classification |
Tonnes |
Grade |
Grade (ppm Ta2O5) |
Contained |
Contained |
|
Open Pit |
Proven |
- |
- |
- |
- |
- |
|
Probable |
48.2 |
1.10 |
132 |
1.31 |
6.3 |
|
|
Underground |
Proven |
- |
- |
- |
- |
- |
|
Probable |
34.9 |
1.51 |
172 |
1.30 |
6.0 |
|
|
TOTAL |
Proven |
- |
- |
- |
- |
- |
|
Probable |
83.0 |
1.27 |
148 |
2.61 |
12.3 |
- The Mineral Reserves were estimated using the Canadian Institute of Mining, Metallurgy and Petroleum (CIM) Estimation of Mineral Resources & Mineral Reserves Best Practice Guidelines (November 29, 2019) and CIM Definition Standards for Mineral Resources and Reserves (May 10, 2014).
- The mine design and Mineral Reserve Estimate have been completed to a level appropriate for feasibility studies. As such, the Mineral Reserves are based on the Indicated Mineral Resources only and do not include any Inferred Mineral Resources. The Inferred Mineral Resources contained within the mine design are classified as waste.
- Mineral Reserves are estimated using a long-term lithium price of USD 1,221/t of spodumene concentrate at
5.5% Li2O and an exchange rate CAN/USD of 1.35. - The revenue factor for the COG calculation was based solely on lithium, with no value derived from tantalum content for COG calculations purposes.
- Mineral Reserves are reported at the point of delivery to the processing plant and include allowances for mining dilution and ore losses. The reference point for the Mineral Reserve estimate is therefore the plant feed
- The QP for the estimate is Hugo Latulippe, P.Eng., MBA. The estimate has an Effective Date of October 19, 2026.
- The Mineral Reserves for open-pit are estimated using a cut-off grade of
0.40% Li2O. Mineral Reserves for underground stoping are estimated using a cut-off grade of0.70% Li2O. Underground development tonnages containing material above0.4% Li2O are also included in the statement. - The following mill recovery equation was used in the cut-off grade calculation:
Lithium Recovery = 38 + (85 - 38) x [1 - e-0.88(Li2OGrade%)] - The open pit strip ratio is 3.5 and dilution and ore loss were estimated using mining solids generated with the "Stope Optimizer" (Deswik.SO). This results in a dilution factor of
7.62% and an ore loss of4.07% . - The underground mine average external dilution factor is
16.7% including2.5% for backfill dilution,5.3% for equivalent linear overbreak/slough (ELOS) external dilution, and8.9% for internal dilution. - For the underground Mineral Reserves, a minimum mining width of 5 m was applied with a mining recovery of
95% for all stopes, while100% extraction was assumed for all development mining. - Contained lithium carbonate equivalent (LCE) is reported without accounting for metallurgical recovery.
- Conversion factors used: LCE (i.e., Li2CO3) = Li2O x 2.473.
- Total may not sum due to rounding; rounding followed the recommendations of NI 43-101.
The development strategy for the Project outlined in the Updated FS continues to consider a hybrid mining model combining UG and OP extraction methods. Phase 1 of the Project now involves the development of the UG mine and a 2.2 Mtpa DMS processing plant. It provides an initial production capacity in the first 3 years of production of up to ~560,000 tpa spodumene concentrate (SC5.5) and up to 1,000 tpa tantalite concentrate grading
The Phase 2 Expansion involves construction of a second DMS concentration plant starting in Year 3 with commissioning in Year 4, adding another 2.9 Mtpa of ore processing capacity supplied with ore from OP operations resuming at full scale after the Starter Pit having been idled at the end of Year 1. With the Phase 2 Expansion, total nameplate processing capacity of 5.1 Mtpa of ore will be attained generating nominal production capacity of ~800,000 tpa spodumene concentrate (SC5.5) and ~1,625 tpa tantalite concentrate (
Total development capital of ~CA
Initial Phase 1 CAPEX includes all construction and pre-production costs up to the date of commercial production, including early engineering and procurement expenses incurred in 2027 prior to FID. Expansion Phase 2 CAPEX includes all construction costs to develop Phase 2 and, therefore, are incurred post commercial production.
Table 7: Summary of Estimated Capital Costs
|
Capital Expenditure |
Phase 1 |
Phase 2 |
Total Capital (M$) |
LOM (M$) |
Total |
|
100 – Infrastructure |
162.7 |
57.4 |
220.1 |
0.2 |
220.3 |
|
200 – Power and Electrical |
173.0 |
29.1 |
202.1 |
- |
202.1 |
|
300 – Water Management |
60.3 |
86.7 |
147.0 |
38.4 |
185.4 |
|
400 – Surface Operations |
45.6 |
20.8 |
66.5 |
6.4 |
72.9 |
|
500 – Mining |
232.8 |
110.7 |
343.5 |
780.5 |
1,124.0 |
|
600 – Process Plant |
204.9 |
158.4 |
363.3 |
- |
363.3 |
|
700 – Construction Indirects |
201.9 |
108.1 |
310.0 |
- |
310.0 |
|
800 – General Services / Owner's Cost |
102.2 |
32.1 |
134.3 |
23.5 |
157.9 |
|
900 – Pre-production, Start-up, Comm. |
74.4 |
0.9 |
75.3 |
- |
75.3 |
|
Total Capital Expenditures (Excl. Contingency) |
1,258.0 |
604.2 |
1,862.2 |
849.1 |
2,711.3 |
|
990 – Contingency |
133.0 |
68.2 |
201.2 |
- |
201.2 |
|
Total Capital Expenditures |
1,391.0 |
672.4 |
2,063.4 |
849.1 |
2,912.5 |
|
|
|
|
|
|
|
|
Less: Pre-Production1 Credit net of TC/RC & Royalties |
(130.6) |
- |
(130.6) |
- |
(130.6) |
|
Total Capex Net of Pre-Production Credit |
1,260.4 |
672.4 |
1,932.8 |
849.1 |
2,781.9 |
|
|
|
|
|
|
|
|
Less: CTM-ITC Tax Credit |
(135.7) |
(77.1) |
(212.7) |
(1.6) |
(214.4) |
|
Less: TCRR Tax Credit |
(45.0) |
- |
(45.0) |
- |
(45.0) |
|
Total Capex Net of Pre-Production Credit, CTM-ITC and TCRR |
1,079.8 |
595.4 |
1,675.1 |
847.4 |
2,522.6 |
100: Infrastructure includes site roads, bridges, truck shop, mine dry and offices, administrative building, camp facilities as well as the fuel and explosives storage and infrastructure earthworks. 200: Power and Electrical includes the main electrical powerline and substations as well as secondary power generation and power distribution at site. 300: Water Management relates to all infrastructure required to collect, manage and treat fresh water, potable water, process water contact and non-contact water. 400: Surface operations relates to construction, process plant and G&A mobile equipment. 500: Mining includes haul roads, open pit equipment purchase, pit surface preparation and some UG infrastructure (ventilation and compressors). 600: Process plant includes capital expenditures for the first production train with a capacity of 2.2 Mtpa and certain early works from the second production train with an additional capacity of 2.9 Mtpa. 700: Construction Indirects include project management and logistics, temporary construction infrastructure and equipment, energy and engineering. 800: General Services / Owner's costs include general and administrative costs, security, IT, owner's costs, logistics, taxes and insurances as well as camp operations costs, health & safety and environment services. 900: Pre-Production costs relate to operating costs incurred in processing and mining prior to achieving commercial production. 990: An overall contingency has been applied to all direct and indirect costs based on quality and engineering level of inputs.
- Pre-Production credits relate to spodumene and tantalite concentrate revenues expected to be realized during the ramp-up period of Phase 1 before reaching commercial production.
Operating costs have been derived from first principles using supplier quotations whenever available and/or using available benchmarks, adjusted for inflation. All operating costs assume owner-run operations, except for Phase 1 Starter Pit operations (Years -1 and Year 1) and for the first three (or Years
The estimated LOM net cash operating cost at site12 including a tantalum credit is CA
LOM Sustaining Capital Costs are expected to average CA
Table 8: LOM Estimated Cash Operating Costs per Tonne of Concentrate
(SC5.5 – FOB Quebec ports)
|
Financial Results |
CA$/t |
US$/t |
|
Mining |
262.5 |
191.6 |
|
Processing |
78.1 |
57.0 |
|
Site Administration |
98.4 |
71.8 |
|
Spodumene Cash Operating Cost at Site16 |
439.0 |
320.4 |
|
Tantalum Credit13 |
(147.8) |
(107.9) |
|
Net Cash Operating Cost at Site12 |
291.2 |
212.5 |
|
Transportation cost |
302.3 |
220.7 |
|
Total Cash Operating Cost (FOB Quebec ports)14 |
593.5 |
433.2 |
|
Sustaining Capital |
63.6 |
46.4 |
|
AISC (FOB Quebec ports)15 |
657.1 |
479.6 |
|
____________ |
|
12 Net cash operating cost at site includes mining, processing and site administration costs and tantalum credit. It is a non-IFRS measure, and when expressed per tonne, a non-IFRS ratio. Refer to the "Non-IFRS and other financial measures" section of this press release for further information on these measures. |
|
13 Tantalum credit is calculated by dividing total revenue from tantalum recovered by the total dry tonnage of spodumene concentrate produced. |
|
14 Total cash operating cost (FOB Quebec ports) includes mining, processing, site administration, and product transportation costs to a port in |
|
15 AISC (FOB Quebec ports) includes mining, processing, site administration, and product transportation costs to a port in |
|
16 Spodumene cash operating cost at site includes mining, processing, site administration costs. It is a non-IFRS measure, and when expressed per tonne, a non-IFRS ratio. Refer to the "Non-IFRS and other financial measures" section of this press release for further information on these measures. |
- LOM OP Mining Cost (CA$/t mined) = CA
$6.45 - LOM UG Mining Cost (CA$/t milled) = CA
$62.52 - LOM Processing Cost (CA$/t milled) = CA
$12.61 - G&A Cost (CA$/t milled) = CA
$15.81
Where OP and UG mining costs are exclusive of pre-production and processing is inclusive of paste backfill plant, tailings and exclusive of pre-production.
The Updated FS adopts long-term price assumptions of
Spodumene price forecasts are generally expressed on a
While the Company had regard to the recent consensus broker forecast price
The Company believes that the Updated FS long term average price assumption, as supported by Benchmark's Q3 2026 annual base-case forecasts (real FOB Australia), is appropriate having regard to the Project's near 20 year mine life.
Benchmark's Q3 2026 base case estimates lithium demand for battery cell production of approximately 1.95 Mt of lithium carbonate equivalent ("LCE") in 2026, increasing to 2.61 Mt in 2030. Within these totals, battery energy storage systems ("BESS") account for approximately 0.69 Mt for 2026 and 0.84 Mt for 2030, respectively. Electric vehicles remain the largest source of demand, while BESS represents a substantial additional market.
Benchmark forecasts near-term lithium deficits, followed by surpluses from 2028 to 2034 and a return to deficits from 2035. These projections remain sensitive to demand growth, recycling, inventory movements, and the timing of new supply. The Updated FS long-term price assumption therefore considers conditions over the anticipated production period rather than prevailing spot prices alone. For added context, supply needs to increase by approximately 2.1 Mt LCE from 2026 to 2035 in Benchmark's model, the equivalent of approximately 21 Shaakichiuwaanaan's at full production. Recycling is also increasing from 86 kt LCE to 536 kt LCE during the same period in Benchmark's forecast, a more than six-fold increase. The 2035 recycling amount is also equivalent of the whole lithium industry supply of 527 kt LCE from 2021.
The Company has a binding offtake term sheet with PowerCo SE (subsidiary of Volkswagen Group) ("PowerCo") for 100,000 tonnes of spodumene concentrate per year over a 10-year term, with pricing largely linked to reported market price references. The offtake is conditional on successful commissioning of the Project by June 30, 2031.17
|
___________ |
|
17 Refer Press Release " |
The Updated FS tantalum price assumption is informed principally by OnG's October 2026 market study. Tantalum is used in computing infrastructure (and in particular recent demand growth through AI datacentres tantalum applications in capacitors, semiconductors and chip manufacturing). Tantalum is also used in aerospace, defence and other industrial applications.
OnG forecasts growth in consumption, particularly in capacitor applications associated with expanding computing infrastructure (e.g., AI data centres), while identifying uncertainty around future supply and strategic stockpiling.
Chinese strategic stockpiling has added to purchasing demand and supported prices. OnG assumes these purchases diminish through 2028, contributing to an easing of the market balance. Its forecast, which includes production from Shaakichiuwaanaan, indicates an approximately balanced market in 2026–2027, surpluses from 2028 to 2034 and deficits in 2035–2036. The timing and scale of strategic purchases remain uncertain.
The simple average of OnG's annual low-high price midpoints is approximately
For reference, the Ta₂O₅ spot price is currently quoted (November 6, 2026) on Shanghai Metal Markets as
The tantalum price assumption is expressed per pound of contained Ta₂O₅, rather than per pound of concentrate. No separate premium has been added for traceability or potential long-term supply arrangements. Actual realised prices will depend on concentrate specifications, product qualification, negotiated commercial terms and selling costs.
The lithium and tantalum price assumptions are used as suitable estimations to evaluate the Project's economics and are not guarantees of future realised prices. The Updated FS sensitivity analysis illustrates the effect of changes in commodity prices on Project value.
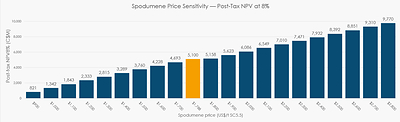
A sensitivity analysis was conducted on the base case post-tax NPV
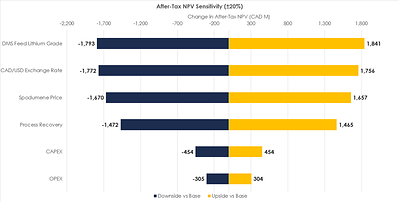
Sensitivity analysis was completed to determine the impact of various factors on the Project NPV. It indicates that the Project is most influenced by spodumene prices. For every
Recent softening in market conditions (as defined by a recent spot price of
In all cases, the Project sensitivity analysis demonstrates the relative economic resilience of the Project to lower than forecast price outcomes.
Since the release of the October 2025 Feasibility Study, the Company has made meaningful progress in advancing its Project financing strategy, translating earlier engagement with leading commercial lenders and government-backed financial institutions into tangible expressions of interest and support. The Company intends to minimise the Project's equity funding requirement by drawing on a diversified mix of potential funding sources, including commercial and government-backed debt, other federal and provincial funding mechanisms, and other sources such as offtake-linked financing, subject to availability and acceptable commercial terms.
The Company has received non-binding letters of interest or support from Société Générale, Export Development Canada (EDC), KfW IPEX-Bank and another major Canadian government-backed financial institution. Société Générale has also expressed interest in acting as Mandated Lead Arranger for a potential project debt financing. These expressions of interest and support are preliminary, non-binding and conditional and do not constitute credit approvals, commitments to lend or definitive financing arrangements.
The Company's existing strategic partnership with Volkswagen Group and PowerCo provides an additional potential avenue for Project financing. As previously disclosed, the partnership provides Volkswagen with a right to participate in funding negotiations alongside other potential strategic partners as a cornerstone investor in Project funding at FID in exchange for additional offtake, on terms to be mutually agreed.
Recent financing transactions also highlight the increasingly important role of the Canadian government in advancing critical minerals projects, through a growing range of financial and commercial support mechanisms. In September 2026, Generation Mining announced a CA
These transactions demonstrate both the scale and diversity of government support in
In parallel, PMET continues to engage with federal and
The addition of tantalum to the Updated FS further expands these financing opportunities by broadening Shaakichiuwaanaan's strategic positioning and offtake funding opportunities beyond lithium. With growing demand for advanced electronics, AI infrastructure, aerospace, and defense applications, the Project is well positioned to attract interest from a wider group of industrial partners and financial investors and government-backed funding seeking secure supplies of critical minerals from stable jurisdictions.
Taken together, these relationships, financing milestones and recent Canadian precedents provide a strong foundation to support the Company's financing strategy. While a FID is not targeted until late 2027, the Company continues to advance discussions with a growing group of credible financial and strategic partners, positioning the Company to establish a competitive and diversified financing structure that seeks to maximise shareholder return while delivering the funding required to develop the Project and advance Shaakichiuwaanaan towards becoming a strategically important source of critical minerals for North American, European and Asian supply chains.
The CV5 LCT Pegmatite deposit consists of a large principal dyke, flanked by several smaller dykes striking approximately east-west. Planned mining operations will incorporate both mechanized long hole open stoping underground ("UG") mining and conventional open-pit ("OP") mining methods. The pegmatite dykes dip at approximately 70-80° northerly and extend over a strike length of approximately 5.0 km with mineralization intersected as deep as 450 m vertical depth from surface. A significant portion of the orebody is located under Lake 001, which will require partial dewatering to enable the full-scale Phase 2 OP operations.
The Project follows a staged two-phase execution strategy:
- Phase 1 prioritizes high-grade underground Nova Zone ore to feed a 2.2 Mtpa capacity dense media separation ("DMS") concentration plant. During Year 1, UG production is supplemented by a small Starter Pit requiring minimal pre-stripping and involving no lake disturbance to sustain the processing plant. The UG production is sufficient to sustain planned processing capacity starting in Year 2 resulting in the Starter Pit operations being idled after Year 1.
- Phase 2 Expansion involves construction of a second DMS concentration plant starting in Year 3 with commissioning in Year 4, adding a further 2.9 Mtpa of processing capacity and supplied with ore coming from resumption of OP operations at full scale. Thereafter, UG and OP production will be coordinated to maximize utilization and recovery of both plants over the near 20 year mine life, with a total installed processing capacity of 5.1 Mtpa of ore.
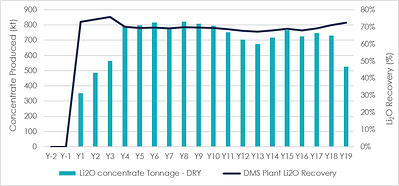
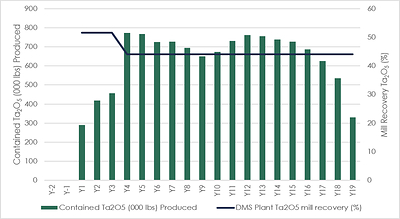
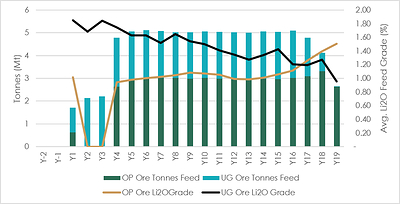
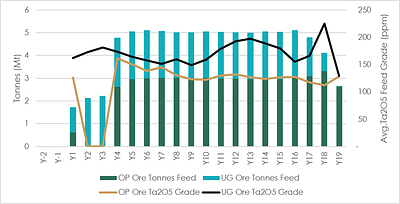
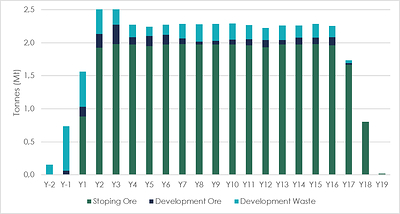
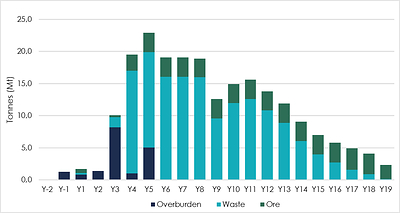
The spodumene concentrate production and recovery, processing schedules and mining schedules for both UG and OP tonnes (based solely on Mineral Reserve) are presented in Figure 5, Figure 6, Figure 7, Figure 8, Figure 9, and Figure 10.
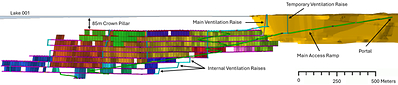
The UG operation comprises a single ramp accessible through a portal located near the run-of-mine ("ROM") pad. The selected mining method is long-hole open stoping ("LHOS") with cemented paste backfill ("CPB"), using both transverse (
The LOM for the UG mine is expected to be 21 years including construction, development, pre-production, and the full production period. Over this LOM, the UG mine is expected to be at full production for 15 years, with production declining in the last three years. At full production, the UG mine is expected to achieve a production rate of approximately 5,700 tpd of ore, with 5,375 tpd from stope production and an average 325 tpd from lateral development. Development of the UG mine includes approximately 81.1 km of lateral and 1.3 km of vertical development to be excavated. A total of 34.9 Mt of ore is expected to be mined at an average diluted grade of
The OP operation will take place over two distinct time horizons and with two distinct scopes:
- Starter Pit: Mining will commence with a very small Starter Pit requiring minimal pre-stripping and no impact to the nearby lake. The Starter Pit will be located within the main pit footprint, maintaining a 60 m stand-off distance to Lake 001. Its production (less than 700 kt) is only meant to supplement the ramp-up of UG operations in order to sustain the processing plant in the first year of operation. After Year 1, OP mining operations at the Starter Pit will be idled;
- Main OP operations: Upon launching the Phase 2 Expansion, mining of the OP will resume, albeit at a much larger rate and scale and ramp up total ore production from the Project to its 5.1 Mtpa nameplate capacity.
The main OP operation will utilize a fleet of diesel-powered equipment, including drills, hydraulic shovels and excavators, and off-highway haul trucks. The OP peak mining rate is 23.0 Mtpa over the LOM. A total of 48.2 Mt at
The primary loading and hauling fleet will consist of 15 m3 diesel-hydraulic shovels for waste and 7 m3 diesel-hydraulic excavators for ore paired with 140 t off-highway mining trucks. While the main OP operations will be owner-operated, the Starter Pit is assumed to be operated with smaller equipment and contracted out.
Figure 12 provides a plan view of the Starter Pit (nestled within the broader OP outline), highlighting its relative distance from the lake. Figure 13 shows a plan view of the final OP operation.
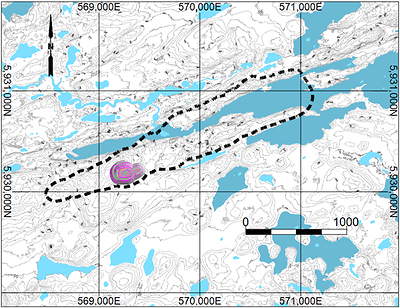
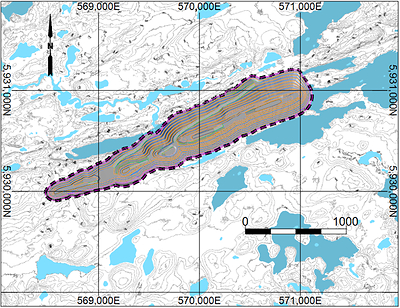
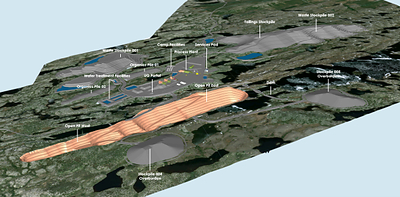
A total of 154.7 Mt of waste rock, 17.8 Mt overburden, and 52.0 Mt tailings will be stored on site, primarily in stockpiles (Figure 14). Mine waste materials are classified and stored in the various site stockpiles allocated to each category. Organic material will be stored on separate piles. Apart from overburden, which will be mined using contractor equipment, all waste rock will be hauled to the Stockpiles and dry stacked using 140 t off-highway mining trucks and tracked dozers.
The mineral processing facility is designed to produce both spodumene (
The Updated Feasibility process plant design and production outcomes have been informed by multiple extensive bench and pilot scale testwork programs. Further, samples contributing to those programs are derived from a wide-spread and representative data-set, to inform a feasibility level assessment.
The Project will have two process trains (referred to as DMS1 associated with Phase 1 and DMS2 associated with Phase 2). Operations begin with only DMS1, processing 2.2 Mtpa of high-grade ore predominantly from UG mining, supplemented in Year 1 by a small "starter" OP (referred as the Starter Pit) while UG production is ramping up. In Year 4 of the mine life, DMS2 becomes operational, with both trains operating in parallel for the rest of the LOM. Phase 2 processes lower-grade OP ore at 2.9 Mtpa. The total installed processing capacity once DMS2 is online is 5.1 Mtpa across the whole facility.
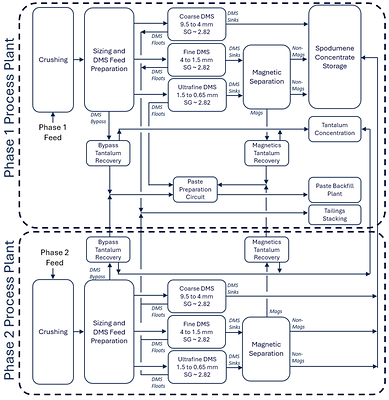
DMS1 and DMS2 are mostly separate process trains. Although similar in design, the two crushing/processing plants are largely unique and operate independently. Interaction between the two plants occurs for the spodumene concentrate storage, the pastefill preparation circuit, the final tantalite concentration stage, and for the tailings dewatering and handling. Figure 15 presents a simplified process flow diagram.
Each process train will be inside three (3) main buildings: the primary crushing building, the secondary and tertiary crushing building, and the main processing plant. The crushed mineralized material will be stored in silos. The mineral processing facility is designed to produce spodumene concentrate at
The following are the major process circuit descriptions:
- Crushing circuit: Receives and reduces the ROM material to a product with a top size of 9.5 mm. The crushing circuit has three stages and is closed with screens. The crushed product reports to a fine ore silo which feeds the processing plant;
- Spodumene processing: Plant feed is screened into three size fractions; coarse, fine, and ultrafine, with material smaller than 0.65 mm (DMS bypass fraction) reporting directly to pastefill preparation, which will feed the tantalum processing circuit. Each size fraction reports to a dedicated DMS circuit where there is a separation of material based on particle density. The fine and ultrafine concentrates are further processed via magnetic separation to both lessen the elemental iron that reports to the final concentrate and to recover tantalum-bearing minerals for further processing in the tantalum recovery circuit;
- Tantalite processing: Tantalum is recovered from non-spodumene concentrate process streams (i.e., spodumene processing tailings/waste streams; DMS bypass, DMS magnetics, and DMS floats that are made available during pastefill preparation (i.e. middlings). A primary concentrate (<
3% Ta2O5) is generated via conventional gravity recovery and magnetic concentration and is subsequently upgraded to the target final concentrate grade of20% Ta2O5 via shaking tables; - Pastefill Preparation/Pastefill: DMS floats (fine, ultrafine), DMS bypass (post tantalite recovery) and DMS magnetics (also post tantalite recovery) are fed to a closed ball mill circuit for grinding. The ground material is thickened and pumped to the paste backfill plant where the material is filtered, mixed with binder and water and then pumped to the target stopes underground.
- Tailings dewatering/handling: The DMS rejects (i.e., floats) that are not being used as pastefill in the pastefill preparation circuit report to a conveyor belt where they are stacked in a pile outside prior to be transported to the tailings pile.
The concentrator has a recovery that is a function of the feed lithia grade (i.e., % Li2O):
Lithium Recovery = 38 + (85 - 38) x [1 - e-0.88(Li2OGrade%)]
The LOM global lithia recovery (in spodumene concentrate) estimated in the Updated Feasibility Study is ~
The global tantalum recovery for DMS1 is
The site infrastructure plan has been outlined to minimize environmental impacts on surrounding water bodies, improve vehicle traffic safety and distances, optimize construction costs, and maximize operational efficiency and flexibility.
The main site infrastructure includes the following:
- Site main access road.
- UG mine and portal.
- OP mine.
- Surface infrastructure for UG mine such as mine ventilation and heating, UG raises to surface.
- Process plant (crusher and screening, crushed ore silos, DMS concentrators, concentrate and tailings loadouts).
- Pastefill plant.
- Vehicle maintenance garage.
- Administrative offices, dry rooms, warehouses, laboratory and auxiliary buildings for the concentrator and the mine areas.
- Waste rock and tailings management piles with their associated ditching and basin systems for water management.
- Overburden piles storage with their associated water management infrastructure.
- Fresh / raw water lake intake and water treatment plants.
- Electrical substation and overhead electrical powerlines.
- Site roads and pads with their associated ditching and culvert, and bridge systems for drainage.
- Aggregate crushing plant area.
- Emulsion storage and explosive storage magazines buildings.
- Laydown areas.
- Fuel storage pad and refuelling stations.
- Run-Of-Mine (ROM) pad.
- Water diversion dams and diversion channel for Lake 001.
- Permanent workers camp for construction and operational needs (400 beds capacity for Phase 1, with 200 beds added for Phase 2) and temporary workers camp for construction needs (250 beds for Phase 1 construction) in addition to the exploration camp (150 beds).
- First Nations cultural centre.
- Temporary construction facilities.
The site is expected to be powered by Hydro-
An off-site 315/120 kV substation, rated at 50 MVA, will be constructed in the vicinity of the existing 735/315 kV Tilly substation. This facility will step down the transmission voltage and supply 120 kV power to the mine site via a new 54 km long 120 kV overhead transmission line. Wherever feasible, the transmission line routing will follow existing roadways to reduce environmental impact and simplify construction logistics. The 120 kV line also provides a sizeable buffer for future expansion and/or midstream development initiatives.
Power supply to site will form part of the Company's continued engagement with regulatory authorities. Access to power will be subject to continued engagement on the detailed engineering solutions and approval to access power via the Hydro-
The mine site is located along the Trans-Taiga Road, approximately 844 km from the Matagami Transshipment Center. This route includes 290 km on the east–west Trans-Taiga Road and 554 km on the north–south Billy Diamond Highway.
Transportation of spodumene concentrate to
These 72 t vehicles will consist of a four-axle tractor and a five-axle bi-train trailer, equipped with a trailer cover and side-discharge system. Accounting for an additional
The Company recently signed a Letter of Intent ("LOI") with the
From
Annual shipments will total approximately 9,300 trips – which amounts to approximately 179 railcars per week required, assuming a 52-week operational year. A full round trip, including loading, CN transport, transit time, and unloading, is estimated at roughly 25 days. To sustain operations, approximately 700 leased railcars will be required at full-scale operations. For the Updated FS, an average price between the
Logistics costs have increased within the Updated Feasibility Study as a function of;
- General inflationary pressure;
- Diesel fuel price and surcharge; and
- Increase in scope (including but not limited to) slightly reduced truck and railcar capacity, seasonal haulage variation and loads, transhipment and port costs.
Transportation of the tantalite concentrate to market is modeled as an incremental cost to material transport to site, as the tantalite concentrate will be shipped in 1 tonne bulk bags as backhaul on standard 30 tonnes capacity flat bed trucks used to bring reagents and materials to site.
The Updated FS analysis provides a robust basis for the logistics strategy, and final routing will be confirmed through commercial negotiations with the entities involved.
The Company continues to advance the environmental assessment and permitting progress for the Shaakichiuwaanaan Project. The regulatory process reached a major milestone in March 2026, when the Company officially submitted the comprehensive Environmental and Social Impact Assessment ("ESIA") documentation to both federal and provincial regulators. The Impact Assessment Agency of
Additionally, in accordance with Section 22 of the
The Updated Feasibility Study incorporates refinements to the Project design while maintaining alignment with the submitted scope of the ongoing environmental assessments. The Company continues to regularly engage with the Cree Nation of
Full closure and reclamation considerations have been included within the Updated FS outcomes.
Widely recognized as a Tier-1 pegmatite critical mineral asset globally, hosting one the world's largest lithium-tantalum pegmatites as well as the world's largest caesium (pollucite) pegmatite, Shaakichiuwaanaan continues to hold considerable exploration upside.
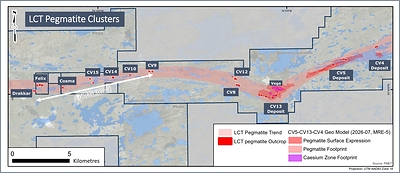
To date, eleven (11) distinct LCT pegmatite clusters have been discovered at the Property with Mineral Resources determined for three (3) – CV5, CV13, and CV4 (Figure 16). A total of five (5) clusters remain to be drill tested and outline a prospective trend exceeding 10 km in length (the "Mickel Trend"). Significant potential is present to grow Mineral Resources through further step-out drill delineation of the CV5, CV13, and CV4 pegmatites – which all remain open in several directions – drill testing along the Mickel Trend, as well as other prospective areas of the Property that remain to be evaluated.
Additionally, the current Mineral Reserve includes only the CV5 Pegmatite and is derived solely from the CV5 Pegmatite's Indicated Mineral Resource. The CV13 and CV4 pegmatite Mineral Resources, including the high-grade Vega Zone within CV13, are not included in the current Mineral Reserve.
The Company, in consultation with its tax advisors, reviewed the Project's initial capital budget and has updated its assessment of eligible Project expenditures and associated tax benefits.
The CTM-ITC provides up to a
In September 2026, the Government of
The Project's potential tax credits, deductions, and government support are contingent on eligibility requirements and government approval. There is no guarantee the Company will obtain any or all of the above-mentioned government initiatives.
With the Updated FS now completed, the Company will formally introduce the key Project modifications to the regulators for inclusion into the Environmental and Social Impact Assessment ("ESIA") process, via the existing feedback mechanisms. The first round of information requests has already been received from the Federal level and the same is expected from the Provincial level by year end. The Company expects that the changes introduced by the Updated FS will be seen as either neutral or positive on the Project's environmental and social impacts, and that the process timelines will not be negatively impacted. On this basis, and subject to securing project approvals and financing, FID remains targeted for late 2027.
In the meantime, the Company will continue to advance detailed engineering. Some further optimisation opportunities (such as modularization, which could cut down construction/installation times for certain elements) will be examined through basic and value engineering steps. Current Project schedule targets DMS commissioning to begin in late 2029, with processing activities quickly ramping up to commercial production at the end of Q1 2030.
The Company continues to target release of a Preliminary Economic Assessment ("PEA") later this quarter exploring an alternative development scenario inclusive of both CV5 and CV13 and on all three commodities present – lithium, caesium, and tantalum.
Concurrently with the main Project's authorisations process, the Company intends to continue to pursue its bulk sample advanced exploration project at CV5, via the development of a 2,300 m exploration ramp to access the mineralized zone at two distinct elevations (210 m depth and 245 m depth) to validate key geological, geotechnical, and hydrogeological assumptions for the Project. Development in the mineralized zone would specifically target the high-grade Nova Zone, and even more specifically well-mineralized lithium-caesium-tantalum intercepts to improve geological understanding. The Company has submitted its application for the bulk sample project and is expecting to receive confirmation before the year end.
The Updated FS sets out a stronger starting position for Shaakichiuwaanaan: higher early production, more immediate access to higher grade ore, a simpler DMS processing flowsheet, and a second revenue stream from tantalum as a valuable co-product. By prioritising the high-grade Nova Zone, the underground-first strategy is designed to deliver more spodumene concentrate from fewer tonnes processed earlier in the mine plan, strengthening early cash flow generation while preserving the Project's long-term scale.
Just as importantly, the revised development sequence removes seasonally sensitive activities from the Phase 1 critical path. With no anticipated change to the ESIA authorisations timeline, the Updated FS combines improved economics with a more robust execution pathway, providing a stronger basis for the Company's targeted FID in late 2027.
The Company's focus now turns to advancing detailed engineering, progressing the underground bulk sample program, and developing the commercial and financing framework to support funding of Phase 1. No FID has yet been made; that decision will take into account detailed engineering, prevailing market conditions, available sources of funding, commercial relationships, and customer requirements.
Beyond this development case, the forthcoming PEA will evaluate the potential of an alternative development scenario that integrates both the CV5 and CV13 Pegmatites, extracting value beyond lithium and tantalum, with the addition of caesium. Building on the Updated FS, the PEA expected to be released before year-end will explore the broader opportunity for Shaakichiuwaanaan to become a large-scale, long-life supplier of critical minerals to global markets.
This press release includes non-IFRS financial measures and non-IFRS financial ratios. The Company believes that these measures provide additional insight, but these measures are not standardized financial measures prescribed under IFRS and therefore should not be confused with, or used as an alternative for, performance measures calculated according to IFRS. Furthermore, these measures should not be compared with similarly titled measures provided or used by other issuers.
The non-IFRS financial measures and non-IFRS financial ratios used in this news release and common to the mining industry are defined below:
- Spodumene cash operating costs at site and spodumene cash operating costs at site per tonne: Spodumene cash operating costs at site is a non-IFRS financial measure which includes mining, processing, and site administration costs. Spodumene cash operating costs at site per tonne is a non-IFRS financial ratio which is calculated as spodumene cash operating costs at site divided by anticipated spodumene concentrate production expressed in tonnes. These measures capture the important components of the Company's anticipated production and related costs and are used to indicate anticipated cost performance of the Company's operations.
- Net cash operating costs at site and net cash operating costs at site per tonne: Net cash operating costs at site is a non-IFRS financial measure which includes mining, processing, and site administration costs, and tantalum credit. The composition of net cash operating costs at site has changed from that disclosed previously to reflect the inclusion of a tantalum by-product credit, because tantalum production is now expected to form part of the Company's operations. Net cash operating costs at site per tonne is a non-IFRS financial ratio which is calculated as net cash operating costs at site divided by anticipated spodumene concentrate production expressed in tonnes. These measures capture the important components of the Company's anticipated production and related costs and are used to indicate anticipated cost performance of the Company's operations.
- Total cash operating costs (FOB Quebec ports) and total cash operating costs per tonne (FOB Quebec ports): Total cash operating costs (FOB Quebec ports) is a non-IFRS financial measure which includes mining, processing, site administration, and product transportation costs to a port in
Quebec , and tantalum credit, but excludes royalties. The composition of total cash operating costs has changed from that disclosed previously to reflect the inclusion of a tantalum by-product credit, because tantalum production is now expected to form part of the Company's operations. Total cash operating costs (FOB Quebec ports) per tonne is a non-IFRS financial ratio which is calculated as total cash operating costs (FOB Quebec ports) divided by anticipated production expressed in tonnes. These measures capture the important components of the Company's anticipated production and related costs and are used to indicate anticipated cost performance of the Company's operations. - All-in sustaining costs (AISC) (FOB Quebec ports) and AISC per tonne (FOB Quebec ports): AISC (FOB Quebec ports) is a non-IFRS financial measure which includes mining, processing, site administration, and product transportation costs to a port in
Quebec , and tantalum credit and sustaining capital, but excludes royalties. The composition of AISC (FOB Quebec ports) has changed from that disclosed previously in the 2025 CV5 Lithium only Feasibility Study to reflect the inclusion of a tantalum by-product credit. This change was made because tantalum production is now expected to form part of the Company's operations and the related credit is expected to offset operating costs. AISC per tonne (FOB Quebec ports) of spodumene concentrate is a non-IFRS financial ratio which is calculated as AISC (FOB Quebec ports) divided by anticipated production expressed in tonnes. These measures capture the important components of the Company's anticipated production and related costs and are used to indicate anticipated cost performance of the Company's operations.
The Company does not currently have operations and therefore does not have historical equivalent measures to compare and cannot therefore reconcile with historical measures.
PMET Resources Inc. is a pegmatite critical mineral exploration and development company focused on advancing its district-scale
In late 2026, the Company announced a positive Updated Lithium-Tantalum Feasibility Study on the CV5 Pegmatite for the Shaakichiuwaanaan Property and a Mineral Reserve of 83.0 Mt at
The Project hosts a Consolidated Mineral Resource19 totalling 113.9 Mt at
This news release has been approved by
"KEN BRINSDEN"
Kenneth Brinsden, President, CEO, & Managing Director
|
___________ |
|
18 See Feasibility Study news release dated November 10, 2026. Probable Mineral Reserve cut-off grade is |
|
19 Consolidated MRE (CV5, CV13, & CV4 pegmatites) is reported at an Li2O cut-off grade of |
This press release contains "forward-looking information" or "forward-looking statements" within the meaning of applicable securities laws.
All statements, other than statements of present or historical facts, are forward-looking statements. Forward-looking statements involve known and unknown risks, uncertainties and assumptions and accordingly, actual results could differ materially from those expressed or implied in such statements. You are hence cautioned not to place undue reliance on forward-looking statements. Forward-looking statements are typically identified by words such as "plan", "development", "growth", "continued", "intentions", "expectations", "strategy", "opportunities", "anticipated", "trends", "potential", "outlook", "ability", "additional", "on track", "prospects", "viability", "estimated", "reaches", "enhancing", "strengthen", "target", "will", "believes", or variations of such words and phrases or statements that certain actions, events or results "may", "could", "would", "might" or "will" be taken, occur or be achieved. Forward-looking statements in this release include, but are not limited to, statements concerning: the results of the Updated FS, including, without limitation, the estimation of Mineral Reserves and Mineral Resources, project economics, and financial and operational parameters such as expected throughput, production, processing methods, cash costs, all-in sustaining costs, other costs, capital expenditures, NPV, IRR, payback period and life of mine, upside potential, opportunities for growth and expected next steps in the development of the project, including detailed engineering and optimisation and timing for potential commencement of construction and first production of concentrate, the economic potential of the Project, including its potential resilience to lower market cycles, the upcoming ESIA, including the proposed permitting and development timeline, the expected incorporation of the Updated FS changes into the ESIA process and the authorisation timeline, the opportunities for additional conversion at CV5, CV13 and CV4, exploration potential and Mineral Resource growth, the anticipated production rate, the phased development plan, including the timing and scope of the Phase 2 Expansion, the expected improvements relative to the 2025 FS, the potential for the Project to become a cornerstone supplier to North American, European, and/or Asian battery supply chains, the timing of the FID, which remains subject to securing project approvals and financing, the eligibility for tax credits and other government support programs, including the anticipated pre-production credits, the CTM-ITC, the TCRR, the
Although the Company believes its expectations are based upon reasonable assumptions and has attempted to identify important factors that could cause actual actions, events or results to differ materially from those described in forward-looking statements, there may be other factors that cause actions, events or results not to be as anticipated, estimated or intended. There can be no assurance that forward-looking information will prove to be accurate, as actual results and future events could differ materially from those anticipated in such information. Key assumptions upon which the Company's forward-looking information is based include without limitation, the key assumptions, parameters and methods used to estimate the Mineral Reserves and Mineral Resources and to prepare the Updated FS; the capital and operating cost estimates and the metallurgical recovery assumptions; the availability of the tax credits and the
Forward-looking statements are also subject to risks and uncertainties facing the Company's business, any of which could have a material adverse effect on the Company's business, financial condition, results of operations and growth prospects. Some of the risks the Company faces and the uncertainties that could cause actual results to differ materially from those expressed in the forward-looking statements include, among others, requirements for additional capital , operating and technical difficulties in connection with mineral exploration and development activities; actual results of exploration activities, including on the Project; the estimation or realization of mineral reserves and mineral resources; the timing and results of estimated future production; the costs of production and capital expenditures, and the accuracy of capital and operating cost estimates, including inflation; the costs and timing of the development of new deposits; future prices of spodumene and tantalum, including the small and relatively opaque nature of the tantalum market and the risk that the Company may be unable to secure offtake for tantalite concentrate on the terms assumed or at all; the risk that the Company does not qualify for, or receive, the tax credits and government support assumed in the Updated FS; the risk that proposed tax measures are not enacted as proposed or at all; the risk that required authorisations are delayed or not obtained; the Company's ability to conclude an agreement with the Cree Nation Government and the Cree Nation of
Forward-looking statements contained herein are presented for the purpose of assisting investors in understanding the Company's business plans, financial performance and condition and may not be appropriate for other purposes.
The forward-looking statements contained herein are made only as of the date hereof. The Company disclaims any intention or obligation to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise, except to the extent required by applicable law. The Company qualifies all of its forward-looking statements by these cautionary statements.
The mineral resource estimate in this release was reported by the Company in accordance with ASX Listing Rule 5.8 on November 3, 2026. The Company confirms that, as of the date of this news release, it is not aware of any new information or data verified by the competent person that materially affects the information included in the announcement and that all material assumptions and technical parameters underpinning the estimates in the announcement continue to apply and have not materially changed. The Company confirms that, as at the date of this announcement, the form and context in which the competent person's findings are presented have not been materially modified from the original market announcement.
The information in this news release that relates to geology and the Consolidated MRE for the Shaakichiuwaanaan Project, which includes the CV5 Pegmatite, is based on, and fairly represents, information compiled by BBA Consultants and Mr. Todd McCracken, P.Geo., who is a Qualified Person as defined by NI 43-101, and member in good standing with the Ordre des Géologues du
The information in this news release that relates to Mineral Reserve, mining, project infrastructure, market study and price assumptions for spodumene and tantalite concentrates and capital and operating costs, is based on, and fairly represents, information compiled by BBA Consultants and Mr. Hugo Latulippe, P.Eng., who is a Qualified Person as defined by NI 43-101, and member in good standing with the Ordre des Ingénieurs du
The information in this news release that relates to financial and economic analysis, is based on, and fairly represents, information compiled by BBA Consultants and Ms. Isabelle Leblanc, P.Eng., who is a Qualified Person as defined by NI 43-101, and member in good standing with the OIQ. Ms. Leblanc has reviewed and approved the technical information in this news release. Ms. Leblanc has verified and reviewed the information provided by a reputable tax advisory firm, including the applicable tax regime, fiscal assumptions, and tax-related inputs incorporated into the financial model. The QP verified that these inputs were correctly integrated into the economic evaluation and assessed the resulting after-tax cash flows, NPV, and IRR for consistency with the technical and economic parameters of the Project. Although Ms. Leblanc is not qualified as a tax specialist and did not independently validate the underlying tax legislation or recreate the tax calculations, Ms. Leblanc considers reliance on the tax advisory firm's expertise appropriate and believes that the after-tax financial model is reasonable for the level of study represented by this Feasibility Study. Ms. Leblanc is Vice-President, Mining and Metals Market at BBA Consultants, a consulting firm based in
The information in this news release that relates to mineral processing and pastefill, is based on, and fairly represents, information compiled by Primero Group Americas Inc. and Ryan Cunningham P. Eng., who is a Qualified Person as defined by NI 43-101, and member in good standing with the OIQ. Mr. Cunningham has reviewed and approved the technical information in this news release. Mr. Cunningham has verified and reviewed the metallurgical testwork, process design and supporting engineering data, including direct oversight of selected testwork programs at the involved testwork facilities. Based on this review, the Mr. Cunningham considers the information adequate and reliable to support the processing assumptions, recovery estimates and economic analysis presented in the Feasibility Study. Mr. Cunningham is Process Engineering Consultant for Primero Group Americas Inc., an engineering consulting firm based in
The information in this news release that relates to mine waste geochemistry, is based on, and fairly represents, information compiled by Vision Geochemistry Ltd. and Mr. Neal Sullivan, Ph.D., P.Geo., who is a Qualified Person as defined by NI 43-101, and member in good standing with the OGQ and with the PGO. Mr. Sullivan has reviewed and approved the technical information in this news release. Mr. Sullivan has reviewed and verified the mine waste geochemical characterization programs and supporting data, including the sample selection, sample representativeness, laboratory QA/QC results, static and kinetic testing data, and the inputs and assumptions used in stockpile geochemical modelling. Mr. Sullivan also provided direct oversight of the static and kinetic testing programs conducted at SGS Canada –
The information in this news release that relates to water management, water balance, pumping and water treatment design, is based on, and fairly represents, information compiled by AtkinsRéalis Inc. and Mr. Antoine Cogulet, P.Eng., who is a Qualified Person as defined by NI 43-101, and member in good standing with the OIQ. Mr. Cogulet has reviewed and approved the technical information in this news release. Mr. Cogulet, visited the Property in June 2025, including the CV5 area, Lake 308, the proposed freshwater intake source, and the CE15 River, the planned final discharge point and the proposed locations of the water management infrastructure. Mr. Cogulet led the multidisciplinary team responsible for and has verified and reviewed the design of the pumping stations, pipelines, water treatment systems, and site water balance. He also contributed to the design of water management infrastructure, including ponds, drainage ditches, diversion channels, and the lake dewatering strategy. In Mr. Cogulet's professional opinion, the water management and water treatment components of the Project have been developed with the level of detail and engineering rigor expected for a feasibility study. Mr. Cogulet is Project Engineer, Mine Water Management at AtkinsRéalis and based in
The information in this news release that relates to tailings, waste rock and overburden stockpile design and mine closure design and management, is based on, and fairly represents, information compiled by AtkinsRéalis Inc. and Mr. Eric Thiesburger, P.Eng., P.Geo., who is a Qualified Person as defined by NI 43-101, and member in good standing with the
The information in this news release that relates to hydrogeology, is based on, and fairly represents, information compiled by AtkinsRéalis Inc. and Mr. Guillaume Comeau, P.Eng., M.Sc., who is a Qualified Person as defined by NI 43-101, and member in good standing with the OIQ. Mr. Comeau has reviewed and approved the technical information in this news release. Mr. Comeau has verified and reviewed environmental baseline reports and hydrogeological modelling studies, including contaminant transport and CV5 pit dewatering assessments. He also developed and supervised a complementary hydrogeological field investigation program for other areas of the Property. He visited the Property in September 2026 and examined locations directly relevant to his areas of responsibility, including the camp infrastructure, core logging and storage facilities, the potable water supply well and a general assessment of the Project area, including the proposed pit location, tailings storage facilities, surrounding lakes and wetlands, and selected groundwater monitoring wells. In Mr. Comeau's professional opinion, the hydrogeological work completed to date for the Project has been conducted in accordance with the level of detail, technical standards, and engineering rigor expected for a feasibility study. Mr. Comeau believes the hydrogeological work completed to date provides a sufficient and appropriate basis for feasibility-level engineering evaluation and decision-making. Mr. Comeau is National Lead, Hydrogeology and Geothermal, at AtkinsRéalis Inc., based in
The information in this news release that relates to mine geotechnics and geomechanics, is based on, and fairly represents, information compiled by Alius Mine Consulting Inc. and Mr. Sébastien Guido, Ing., who is a Qualified Person as defined by NI 43-101, and member in good standing with the OIQ. Mr. Guido has reviewed and approved the technical information in this news release. Mr. Guido has verified and reviewed the geotechnical data that supports the geotechnical analyses and recommendations presented herein. Mr. Guido believes the geotechnical work completed to date provides a sufficient and appropriate basis for feasibility-level engineering evaluation and decision-making . Mr. Guido is Senior Engineer, Rock Mechanics at Alius Mine Consulting Inc., a consulting firm based in
The information in this news release that relates to mine ventilation design, is based on, and fairly represents, information compiled by CGM Expert Inc. and Mr. Charles Gagnon, P.Eng., who is a Qualified Person as defined by NI 43-101, and member in good standing with the OIQ. Mr. Gagnon has reviewed and approved the technical information in this news release. Mr. Gagnon has verified and reviewed the ventilation information and supporting documentation provided for this study. Based on the level of assessment and the intended use of the report, no further validation of the ventilation data was considered necessary. It is Mr. Gagnon's opinion that the information supplied is adequate and appropriate to support the ventilation-related conclusions presented herein. Mr. Gagnon is Mine Ventilation Specialist at CGM Expert Inc. and based in
The information in this news release that relates to environmental and social aspects, is based on, and fairly represents, information compiled by WSP Canada Inc. and Ms. Nathalie Fortin, P.Eng., M.Env., who is a Qualified Person as defined by NI 43-101, and member in good standing with the OIQ. Ms. Fortin has reviewed and approved the technical information in this news release. Ms. Fortin has verified and reviewed field investigations supporting the environmental and social components under her responsibility which were carried out by WSP field teams and other specialized consultants involved in the preparation of the environmental baseline and the Environmental and Social Impact Assessment. These programs, conducted between 2022 and 2026, covered noise, air quality, hydrology, surface water and sediment quality, vegetation and wetlands, fish and fish habitat, herpetofauna, avian fauna, bats, small mammals, large fauna, special status species, archaeology, and land use. Ms. Fortin participated in the preparation and review of the environmental and social aspects of this Feasibility Study, with the exception of hydrogeology, geochemistry, and rehabilitation and closure planning, which are addressed by other QPs. The QP relied on the field data collected by WSP and the other consultants and did not independently reproduce field surveys, sampling, or laboratory analyses. It is Ms. Fortin's professional opinion that the environmental and social data used for the components under her responsibility has been suitably validated, and that the work completed was carried out in accordance with the level of detail, technical standards, and professional rigor expected for a feasibility study. Ms. Fortin is Senior Director, Project Delivery Simplification and Standardization at WSP and based in
The Mineral Reserve Estimate is based on the Updated Feasibility Study completed for the CV5 Lithium-Tantalum Project. A summary of the material assumptions and outcomes required under ASX Listing Rule 5.9.1 is provided below.
|
Requirement under ASX Listing Rule 5.9.1 |
Summary |
|
Material assumptions and outcomes from the Feasibility Study |
The Updated Feasibility Study ("Updated FS") confirms the technical feasibility and economic viability of the CV5 Lithium-Tantalum Project. The Project is based on a phased development strategy comprising an initial underground operation and 2.2 Mtpa DMS processing plant (Phase 1), followed by an open pit expansion and second DMS processing train increasing total processing capacity to 5.1 Mtpa (Phase 2). The Updated FS generates an after-tax NPV Total cash operating costs estimated at CA CA$/US$ rate of 1.37. |
|
Criteria used for classification and confidence in Modifying Factors |
The Mineral Reserve Estimate is derived entirely from Indicated Mineral Resources within the CV5 Pegmatite. No Measured Mineral Resources have been defined, and no Inferred Mineral Resources have been converted to Mineral Reserves. Inferred Mineral Resources contained within mine designs were treated as waste with zero grade. Following application of mining, metallurgical, economic, environmental, infrastructure, permitting and other Modifying Factors at feasibility study level, the Competent Person determined that the appropriate classification is Probable Mineral Reserve. The resulting Mineral Reserve is 83.0 Mt at |
|
Mining methods and mining assumptions |
Mining comprises a combination of underground and open-pit extraction. Underground mining uses mechanised long-hole open stoping with cemented paste backfill and is accessed via a single ramp. Underground stopes apply a |
|
Processing method and processing assumptions |
Processing is based on conventional crushing and Dense Media Separation (DMS) technology using two processing trains. The process is designed to produce spodumene concentrate grading |
|
Basis of cut-off grades |
Reserve cut-off grades were determined using feasibility-level operating, processing, transport, royalty and recovery assumptions. The open pit Mineral Reserve cut-off grade is |
|
Estimation methodology |
The Mineral Reserve estimate was completed by BBA Consultants and is based on the July 2026 Mineral Resource Estimate. Mine designs, schedules and economic optimisation were completed to feasibility study level. Open-pit reserves were derived from detailed pit optimisation and mine design. Underground reserves were derived using Deswik Stope Optimiser and detailed mine design supported by geotechnical parameters, dilution estimates, mining recovery factors and economic assessment. Zone-by-zone economic evaluation was undertaken for underground stopes to confirm economic viability. |
|
Material Modifying Factors |
Environmental and social baseline studies and an Environmental and Social Impact Assessment (ESIA) have been completed and submitted to federal and provincial regulators. The federal ESIA was deemed complete by the Impact Assessment Agency of |
Note, JORC Code Table 1, Sections 1, 2, and 3, for the current Mineral Resource Estimate that underpins the Feasibility Study discussed herein are presented in the news release dated November 3, 2026.
(Criteria in this section apply to all succeeding sections)
See ASX Announcement dated November 3, 2026
(Criteria in this section apply to all succeeding sections)
See ASX Announcement dated November 3, 2026
(Criteria in this section apply to all succeeding sections)
See ASX Announcement dated November 3, 2026
|
Criteria |
JORC Code explanation |
Commentary |
||||||
|
Mineral Resource estimate for Conversion to Ore Reserves |
|
|
||||||
|
Site Visits |
|
|
||||||
|
Study Status |
|
|
||||||
|
Cut-off parameters |
|
Open Pit
Underground
|
||||||
|
Mining factors or assumptions |
|
Open Pit
Underground
Infrastructure Requirements
|
||||||
|
Metallurgical factors or assumptions |
|
|
||||||
|
Environment |
|
Studies of Potential Environmental Impacts of the operations as a whole:
Waste and Tailings Management Facilities and characterization:
|
||||||
|
Infrastructure |
|
|
||||||
|
Costs |
|
The following assumptions apply to the capital and operating cost estimate:
|
||||||
|
Revenue factors |
|
|
||||||
|
Market assessment |
|
|
||||||
|
Economic |
|
|
||||||
|
Social |
|
|
||||||
|
Other |
|
|
||||||
|
Classification |
|
|
||||||
|
Audits or reviews |
|
|
||||||
|
Discussion of relative accuracy/ confidence |
|
|
||||||
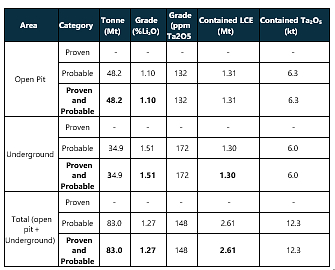
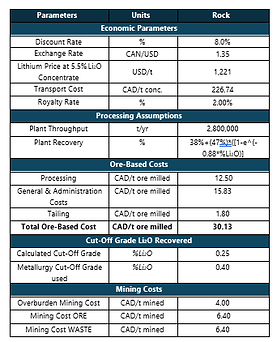
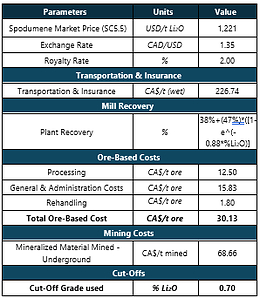
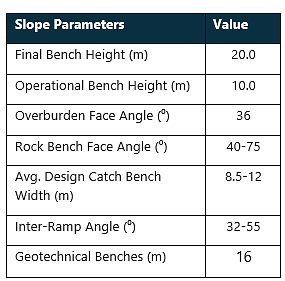
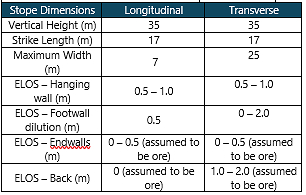
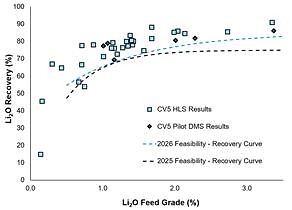
 View original content to download multimedia:https://www.prnewswire.com/news-releases/pmet-resources-delivers-enhanced-cv5-lithium-tantalum-feasibility-study-302935613.html
SOURCE PMET Resources Inc.
FAQ
AI-generated questions and answers. How Rhea-AI works. Not financial advice.
What economics does PMET Resources project for the updated CV5 lithium-tantalum project?
The updated study projects CA$5,100 million after-tax net present value at an 8% discount rate and a 40.4% after-tax internal rate of return. These estimates assume long-term spodumene concentrate pricing of US$1,788/t and tantalum pricing of US$120/lb of contained tantalum pentoxide.
When does PMET Resources expect CV5 commissioning and an investment decision?
PMET targets plant commissioning from the latter part of 2029 and a final investment decision in late 2027. The investment decision has not yet been made.
When will PMET Resources publish the updated CV5 technical report?
The technical report detailing the updated feasibility study and mineral resource estimate will be filed on SEDAR+ within 45 days of the announcement. It will be prepared under National Instrument 43-101, the Canadian standards for mineral-project disclosure.