
Soluna Reports Q3'26 Results; Begins Construction Work at Kati 2 and Dorothy 3
Sentiment and the balance of points
Rhea-AI Sentiment reads the wording of the document, how positive or negative its language is on a 1 to 5 scale. The balance of points shown with the takes weighs what the document actually discloses, so the two can disagree, for example when a trial that missed its main goal is described in upbeat language.
Rhea-AI Summary
Soluna Holdings (SLNH) reported third-quarter revenue of $15.1 million and began construction at its Kati 2 and Dorothy 3 projects. Revenue rose 80% year over year, or 29% excluding gross presentation of pass-through electricity. Net loss widened to $34.3 million from $25.8 million, with $3.0 million in unplanned wind-turbine repairs weighing on results.
A November non-binding letter of intent covers 118 IT MW at Kati 2. An October agreement with Applied Digital provides for a planned 50 MW Dorothy 3 joint venture, owned 51% by Applied Digital and 49% by Soluna; closing is expected by year-end 2026, subject to remaining conditions. Kati 1 reached its full 83 MW. Quarter-end unrestricted cash was $109.3 million. Following the October payoff of its remaining Generate Capital debt, total debt principal was approximately $7.7 million. Equity fundraising totaled $170.1 million year to date.
Positive
- Q3 revenue rose 80% year over year to $15.1 million; growth excluding gross pass-through electricity was 29%.
- Q3 data hosting revenue increased to $12.449 million from $5.257 million a year earlier.
- Wind generation contributed $594,000 in Q3 revenue, versus none a year earlier.
- Nine-month revenue increased to $39.601 million from $20.510 million in 2025.
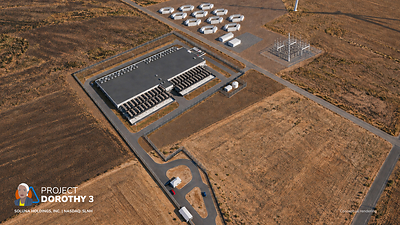
- Kati 2 and Dorothy 3 construction began in October, advancing both development projects.
- Kati 2's November tenant letter of intent covers 118 IT MW at the planned 350+ MW campus.
- Dorothy 3's signed subscription agreement provides for a planned 50 MW facility with Applied Digital.
- Dorothy 3 acquired 397 acres on August 24 for its planned 300 MW campus.
- ERCOT Base Load classifications cover 266 MW of existing capacity: 166 MW at Kati and 100 MW at Dorothy.
- Kati 2 and Dorothy 3 received sales and use tax exemptions.
- Dorothy 3 Phase 1 tax abatement received county approval on November 9, 2026.
- Kati 1 reached its full 83 MW on September 8; newly energized K1BC first recognized revenue in Q3.
- Unrestricted cash rose 43% to $109.3 million at September 30 from $76.4 million at year-end 2025.
- Equity fundraising provided $170.1 million year to date, including $37.7 million through the Q3 ATM program.
- Generate Capital debt was fully repaid by October 22; facility termination released liens on project assets.
- Total debt principal fell to approximately $7.7 million following October repayment, from $37.9 million at June 30.
- Q3 loss per common share narrowed to $0.16 from $1.14 a year earlier.
- Q3 other financing expense fell to $10,000 from $4.746 million a year earlier.
- Q3 fair-value adjustment loss was zero, compared with $22.047 million a year earlier.
Negative
- Q3 net loss widened to $34.329 million from $25.787 million a year earlier.
- Q3 gross result deteriorated to a $1.9 million loss from a $2.3 million profit a year earlier.
- Unplanned Briscoe turbine repairs cost $3.0 million and caused related downtime.
- Q3 adjusted EBITDA loss widened to $7.5 million from $6.4 million a year earlier.
- Q3 operating loss widened to $28.963 million from $7.780 million a year earlier.
- Q3 general and administrative expenses reached $27.072 million, versus $10.109 million a year earlier.
- Q3 debt extinguishment and revaluation produced a $5.729 million loss, versus a $10.107 million gain.
- Q3 cryptocurrency mining revenue fell to $1.853 million from $2.769 million a year earlier.
- Average hashprice declined 37%, reducing proprietary mining and profit-share hosting revenue.
- Q3 demand response revenue fell to $251,000 from $389,000 a year earlier.
- Nine-month net loss widened to $74.855 million from $40.921 million in 2025.
- Common shares outstanding increased to 256,182,519 at September 30 from 102,531,089 at year-end 2025, diluting holders.
- Authorized common shares increased from 375 million to 1.0 billion; shareholders also approved Yorkville SEPA issuance above Nasdaq's 20% limit.
- Kati 2's tenant letter of intent remains non-binding; a definitive lease is not secured.
- Dorothy 3 joint-venture closing remains conditional, with completion expected by year-end 2026.
- ChronoScale's Dorothy 3 lease letter of intent is non-binding.
- Project financing and definitive leases remain priorities for advancing Kati 2 and Dorothy 3 toward delivery.
- ERCOT capacity classifications await verification; an additional 50 MW Dorothy request remains under study.
- Kati 1 suffered a mid-September substation outage that temporarily affected part of the site.
News Explained
Expanded share authorization adds potential dilution capacity, alongside a higher reported issued-share count.
At the
The company reported 256,387,010 common shares issued at
Key Figures
- Revenue
- $15.1 million; up 80% year over year
- Q3 2026 vs. Q3 2025
- Gross profit
- Loss of $1.9 million
- Q3 2026, vs. $2.3 million profit in Q3 2025
- Net loss
- $34.3 million
- Q3 2026, vs. $25.8 million in Q3 2025
- Adjusted EBITDA loss
- $7.5 million
- Q3 2026, vs. $6.4 million in Q3 2025
- Unrestricted cash
- $109.3 million
- At September 30, 2026
- Total debt principal
- Approximately $7.7 million
- Following the October repayment of the remaining Generate balance
- Kati 2 prospective tenant LOI
- 118 MW
- Non-binding letter of intent signed in November
- Dorothy 3 Phase 1 facility
- Planned 50 MW
- AI/HPC facility under the Applied Digital joint venture
Historical Context
-
Prior Applied Digital agreement set planned 50 MW Dorothy 3 JV; construction has begun.
24h Move is the share-price change in the day after each event; other market factors may also have contributed.
Key Terms
non-binding letter of intent financial
atm program financial
adjusted ebitda financial
tax abatement agreement regulatory
AI-generated analysis. How Rhea-AI works. Not financial advice.


Revenue up
"Our focus is converting the AI projects in our pipeline to signed leases," said John Belizaire, CEO of Soluna Holdings. "In recent months, we advanced development and initial construction at Kati 2 and Dorothy 3. We received ERCOT Base Load classifications for 266 megawatts across our two
"Our third-quarter results reflect continued revenue growth, despite
Recent Highlights:
Advanced AI strategy and project execution
- Project Kati 2 / AI – After the prior prospective tenant's exclusivity period ended, Soluna remarketed the site and, in November, signed a non-binding letter of intent with a new prospective tenant to lease 118 IT MW at the planned 350+ MW Kati 2 campus.
- Project Dorothy 3 / AI – Acquired 397 acres on August 24 for the planned 300 MW renewable-first AI campus. On October 20, Soluna signed a subscription agreement to form a joint venture,
51% Applied Digital and49% Soluna, for a planned 50 MW critical IT Phase 1 AI/HPC facility at Dorothy 3. ChronoScale signed a non-binding letter of intent to lease the facility. Closing is expected by year-end 2026, subject to remaining conditions. - Kati 2 and Dorothy 3 construction – Construction began at both sites in October.
- Power and interconnection – Received ERCOT Base Load classifications in September covering 266 MW of existing interconnection capacity across the Kati (166 MW), including the planned Kati 2 expansion) and Dorothy (100 MW) campuses. These classifications preserve existing capacity and exempt it from further reliability evaluation and megawatt allocation in the Batch Zero study, pending completion of ERCOT's verification process. An additional 50 MW request at Dorothy is under study.
- Tax exemptions and abatement – Soluna received sales and use tax exemptions for Projects Kati 2 and Dorothy 3. On November 9, 2026, the Briscoe County Commissioners Court approved a Chapter 312 tax abatement agreement for Phase 1 of Dorothy 3.
- Project Kati 1 – Completed the final 14 MW on September 8, fully energizing the 83 MW site. Revenue from the newly energized K1BC phase was first recognized in Q3. A substation outage in mid-September temporarily affected part of the site.
Strengthened the balance sheet and financial flexibility
- Liquidity and capital formation – Soluna ended the quarter with
$109.3 million $16.7 million $37.7 million - Generate Capital debt fully repaid – In August, Soluna prepaid its Generate facilities at Dorothy 1A and Dorothy 2 for
$19.1 million $27.5 million $37.9 million $7.7 million - Authorized share increase – At the Company's 2026 annual meeting of stockholders held on October 16, 2026, Soluna's stockholders approved an increase in the Company's authorized common stock from 375 million to 1.0 billion shares and the issuance of shares above Nasdaq's
20% limit under the Yorkville SEPA.
Expanded leadership and internal AI capability
- Leadership and team – Ryan Carver joined as Chief Development Officer in July to lead AI infrastructure development. He has since built out the development team, bringing on Neil Robinson as Vice President of Construction and Michal Stark as Vice President of Procurement.
- Board election – At the Company's 2026 annual meeting of stockholders held on October 16, 2026, Soluna's stockholders elected Dan Golding to the Company's Board of Directors. Dan brings more than 30 years of experience in data centers and digital infrastructure, including leadership roles at Google and Iron Mountain.
Third Quarter Financial Highlights:
- Revenue grew
80% over Q3 2025 to$15.1 million 29% excluding the gross presentation of pass-through electricity), marking a sixth consecutive quarter of sequential growth. Hosting capacity additions, contract termination revenue, and new wind generation revenue fromBriscoe were partially offset by a37% decline in average hashprice, which reduced proprietary mining and profit-share hosting revenue. - Gross profit decreased to a loss of (
$-1.9 $2.3 million $3.0 million $1.1 million - Net loss increased to $-34.3 million from
$-25.8 million $22.0 million $15.8 million $14.0 million $3.1 million $4.2 million $4.7 million - Adjusted EBITDA loss widened to
$-7.5 $-6.4 million Briscoe turbine repairs and higher G&A reflecting continued investment in the HPC business, mainly legal and consulting fees for Kati 2 development and new site evaluation, partially offset by the absence of prior-year financing costs. Reconciliation of Adjusted EBITDAto net loss, the most comparable GAAP financial metric, is in the Appendix. - Unrestricted cash was
$109.3 million 43% from$76.4 million - Deleveraged while funding growth. The
$170.1 million $40.5 million $16.7 million $26.8 million $7.7 million
The unaudited financial statements and Quarterly Report on Form 10-Q for the three months ended September 30, 2026, filed with the
Our current Investor Presentation is available here.
Soluna's glossary of terms is available here.
Safe Harbor Statement
This announcement contains forward-looking statements. These statements are made under the "safe harbor" provisions of the
Non-GAAP Measures
In addition to figures prepared in accordance with generally accepted accounting principles ("GAAP"), Soluna from time to time may present alternative non-GAAP performance measures, e.g., EBITDA, adjusted EBITDA, adjusted net profit/loss, adjusted earnings per share, free cash flow, both on a company basis and on a project-level basis, among others. EBITDA is defined as earnings before interest, taxes, and depreciation and amortization. Adjusted EBITDA is defined as EBITDA adjusted for stock-based compensation costs, loss on sale of fixed assets and deposit on equipment, right of first refusal amortization gain, accretion of asset retirement obligation, SEPA commitment fee, fair value adjustment loss, and gain on debt extinguishment and revaluation, net. Project-level measures may not take into account a full allocation of corporate expenses. These measures should be considered in addition to, but not as a substitute for, the information prepared in accordance with GAAP. Alternative performance measures are not subject to GAAP or any other generally accepted accounting principles. Other companies may define these terms in different ways. See our quarterly report on Form 10-Q for the quarter ended September 30, 2026 for an explanation of how management uses these measures in evaluating its operations. Investors should review the non-GAAP reconciliations provided in the Appendix and not rely on any single financial measure to evaluate the Company's business.
About Soluna Holdings, Inc. (Nasdaq: SLNH)
Soluna is on a mission to make renewable energy a global superpower using computing as a catalyst. The company designs, develops, and operates digital infrastructure that transforms surplus renewable energy into global computing resources. Soluna's pioneering data centers are strategically co-located with wind, solar, or hydroelectric power plants to support high-performance computing applications, including Bitcoin Mining, Generative AI, and other compute-intensive applications. Soluna's proprietary software MaestroOS(™) helps energize a greener grid while delivering cost-effective and sustainable computing solutions and superior returns. To learn more, visit solunacomputing.com and follow us on:
LinkedIn: https://www.linkedin.com/company/solunaholdings/
X (formerly Twitter): x.com/solunaholdings
YouTube: youtube.com/c/solunacomputing
Newsletter: bit.ly/solunasubscribe
Resource Center: solunacomputing.com/resources
Soluna regularly posts important information on its website and encourages investors and potential investors to consult the Soluna investor relations and investor resources sections of its website regularly.
|
Soluna Holdings, Inc. and Subsidiaries Condensed Consolidated Balance Sheets As of September 30, 2026 (Unaudited) and December 31, 2025
|
|||
|
|
|||
|
(Dollars in thousands, except per share) |
September 30, 2026 |
|
December 31, 2025 |
|
Assets |
|
|
|
|
Current Assets: |
|
|
|
|
Cash |
$ 109,293 |
|
$ 76,423 |
|
Restricted cash |
5,846 |
|
4,500 |
|
Accounts receivable, net (allowance for expected credit losses of |
6,803 |
|
5,522 |
|
Prepaid expenses and other current assets |
7,045 |
|
2,664 |
|
Loan commitment assets |
— |
|
3,018 |
|
Total Current Assets |
128,987 |
|
92,127 |
|
Restricted cash, noncurrent |
7,920 |
|
7,920 |
|
Other assets |
973 |
|
978 |
|
Deposits and credits on equipment |
5,452 |
|
1,377 |
|
Property, plant and equipment, net |
147,358 |
|
74,783 |
|
Intangible assets, net |
1,153 |
|
8,261 |
|
Operating lease right-of-use assets |
4,132 |
|
252 |
|
Financing lease right-of-use assets |
1,752 |
|
2,246 |
|
Total Assets |
$ 297,727 |
|
$ 187,944 |
|
|
|
|
|
|
Liabilities and Equity |
|
|
|
|
Current Liabilities: |
|
|
|
|
Accounts payable |
$ 4,013 |
|
$ 4,859 |
|
Accrued liabilities |
10,560 |
|
13,182 |
|
Accrued interest payable |
38 |
|
303 |
|
Contract termination liability |
19,348 |
|
19,348 |
|
Current portion of debt |
14,376 |
|
8,858 |
|
Income tax payable |
207 |
|
123 |
|
Deferred revenue |
— |
|
518 |
|
Customer deposits- current |
2,963 |
|
1,913 |
|
Operating lease liability |
111 |
|
65 |
|
Financing lease liability |
23 |
|
20 |
|
Other current liabilities |
414 |
|
— |
|
Total Current Liabilities |
52,053 |
|
49,189 |
|
|
|
|
|
|
Other liabilities |
917 |
|
743 |
|
Customer deposits- long-term |
1,569 |
|
2,533 |
|
Long-term debt |
2,332 |
|
17,899 |
|
Asset retirement obligation |
3,828 |
|
— |
|
Operating lease liability |
4,409 |
|
187 |
|
Financing lease liability |
1,763 |
|
2,236 |
|
Deferred tax liability, net |
180 |
|
2,911 |
|
Total Liabilities |
67,051 |
|
75,698 |
|
|
|
|
|
|
Commitments and Contingencies (Note 12) |
|
|
|
|
|
|
|
|
|
Mezzanine Equity: |
|
|
|
|
Placement agent warrants |
1,313 |
|
1,313 |
|
|
|
|
|
|
Equity: |
|
|
|
|
|
5 |
|
5 |
|
Series B Preferred Stock, par value |
— |
|
— |
|
Common stock, par value |
256 |
|
103 |
|
Additional paid-in capital |
629,182 |
|
435,030 |
|
Accumulated deficit |
(434,564) |
|
(367,715) |
|
Common stock in treasury, at cost, 204,491 shares at September 30, 2026 and 86,595 shares at December 31, 2025 |
(14,045) |
|
(13,873) |
|
Total Soluna Holdings, Inc. Stockholders' Equity (Deficit) |
180,834 |
|
53,550 |
|
Non-Controlling Interest |
48,529 |
|
57,383 |
|
Total Equity |
229,363 |
|
110,933 |
|
Total Liabilities, Mezzanine Equity, and Equity |
$ 297,727 |
|
$ 187,944 |
|
The accompanying notes are an integral part of these unaudited condensed consolidated financial statements. |
|||
|
Soluna Holdings, Inc. and Subsidiaries Condensed Consolidated Statements of Operations (Unaudited) For the Three and Nine Months Ended September 30, 2026 and 2025
|
|||||||
|
|
|||||||
|
(Dollars in thousands, except per share) |
Three Months Ended |
|
Nine Months Ended |
||||
|
|
2026 |
|
2025 |
|
2026 |
|
2025 |
|
|
|
|
|
|
|
|
|
|
Cryptocurrency mining revenue |
$ 1,853 |
|
$ 2,769 |
|
$ 5,742 |
|
$ 8,630 |
|
Data hosting revenue |
12,449 |
|
5,257 |
|
31,790 |
|
10,795 |
|
Wind energy generation revenue |
594 |
|
— |
|
960 |
|
— |
|
Demand response service revenue |
251 |
|
389 |
|
1,109 |
|
1,057 |
|
High-performance computing service revenue |
— |
|
— |
|
— |
|
28 |
|
Total revenue |
15,147 |
|
8,415 |
|
39,601 |
|
20,510 |
|
Operating costs: |
|
|
|
|
|
|
|
|
Cost of cryptocurrency mining revenue, exclusive of depreciation |
1,396 |
|
1,708 |
|
4,012 |
|
5,428 |
|
Cost of data hosting revenue, exclusive of depreciation |
7,547 |
|
2,660 |
|
18,838 |
|
5,605 |
|
Cost of wind energy generation revenue, exclusive of depreciation |
5,020 |
|
— |
|
7,273 |
|
— |
|
Cost of high-performance computing services |
— |
|
— |
|
— |
|
7 |
|
Cost of cryptocurrency mining revenue- depreciation |
612 |
|
1,053 |
|
2,659 |
|
3,200 |
|
Cost of data hosting revenue- depreciation |
1,466 |
|
665 |
|
3,979 |
|
1,578 |
|
Cost of wind energy generation revenue- depreciation and accretion expense |
997 |
|
— |
|
2,050 |
|
— |
|
Total costs of revenue |
17,038 |
|
6,086 |
|
38,811 |
|
15,818 |
|
Operating expenses: |
|
|
|
|
|
|
|
|
General and administrative expenses, exclusive of depreciation and amortization |
24,669 |
|
7,708 |
|
56,048 |
|
19,053 |
|
Depreciation and amortization associated with general and administrative expenses |
2,403 |
|
2,401 |
|
7,204 |
|
7,207 |
|
Total general and administrative expenses |
27,072 |
|
10,109 |
|
63,252 |
|
26,260 |
|
Impairment on intangibles |
— |
|
— |
|
70 |
|
— |
|
Impairment on fixed assets |
— |
|
— |
|
— |
|
12 |
|
Operating loss |
(28,963) |
|
(7,780) |
|
(62,532) |
|
(21,580) |
|
Interest expense |
(1,274) |
|
(1,212) |
|
(5,922) |
|
(3,246) |
|
(Loss) gain on debt extinguishment and revaluation, net |
(5,729) |
|
10,107 |
|
(9,926) |
|
10,658 |
|
Loss on sale of fixed assets and deposits on equipment |
(65) |
|
(780) |
|
(618) |
|
(802) |
|
Fair value adjustment gain (loss) |
— |
|
(22,047) |
|
246 |
|
(22,165) |
|
Other financing expense |
(10) |
|
(4,746) |
|
(579) |
|
(5,203) |
|
Other income (expense), net |
205 |
|
5 |
|
1,798 |
|
(280) |
|
Loss before income taxes |
(35,836) |
|
(26,453) |
|
(77,533) |
|
(42,618) |
|
Income tax benefit, net |
1,507 |
|
666 |
|
2,678 |
|
1,697 |
|
Net loss |
(34,329) |
|
(25,787) |
|
(74,855) |
|
(40,921) |
|
(Less) Net loss (income) attributable to non-controlling interest |
5,655 |
|
1,831 |
|
8,006 |
|
2,027 |
|
Net loss attributable to Soluna Holdings, Inc. |
$ (28,674) |
|
$ (23,956) |
|
$ (66,849) |
|
$ (38,894) |
|
|
|
|
|
|
|
|
|
|
Basic and Diluted loss per common share: |
|
|
|
|
|
|
|
|
Basic & Diluted loss per share |
$ (0.16) |
|
$ (1.14) |
|
$ (0.55) |
|
$ (3.29) |
|
|
|
|
|
|
|
|
|
|
Weighted average shares outstanding (Basic and Diluted) |
196,323,727 |
|
26,983,023 |
|
137,544,674 |
|
15,683,072 |
|
The accompanying notes are an integral part of these unaudited condensed consolidated financial statements. |
|||||||
|
Soluna Holdings, Inc. and Subsidiaries Condensed Consolidated Statements of Cash Flows (Unaudited) For the Nine Months Ended September 30, 2026 and 2025 |
|||
|
|
|||
|
|
Nine Months Ended September 30, |
||
|
(Dollars in thousands) |
2026 |
|
2025 |
|
Operating Activities |
|
|
|
|
Net loss |
$ (74,855) |
|
$ (40,921) |
|
|
|
|
|
|
Adjustments to reconcile net loss to net cash used in operating activities: |
|
|
|
|
Depreciation expense |
8,528 |
|
4,866 |
|
Amortization expense |
7,121 |
|
7,119 |
|
Stock-based compensation |
35,581 |
|
5,671 |
|
Deferred income taxes |
(2,731) |
|
(1,716) |
|
Right of first refusal amortization gain |
(180) |
|
— |
|
Impairment on fixed assets and intangibles |
70 |
|
12 |
|
Amortization of operating and finance lease asset |
247 |
|
79 |
|
Loss (gain) on debt extinguishment and revaluation, net |
9,926 |
|
(10,658) |
|
Amortization of deferred financing costs and discount on notes |
2,642 |
|
561 |
|
Fair value adjustments, including SEPA |
(246) |
|
22,165 |
|
Fair value on placement warrant financing cost |
— |
|
146 |
|
SEPA commitment cost |
250 |
|
- |
|
Accretion of asset retirement obligation |
243 |
|
— |
|
Gain on transformer settlement |
(1,409) |
|
— |
|
Loss on sale of fixed assets and deposit on equipment, net |
618 |
|
802 |
|
Changes in operating assets and liabilities: |
|
|
|
|
Accounts receivable |
211 |
|
(1,715) |
|
Prepaid expenses and other current assets |
(3,092) |
|
(1,741) |
|
Other long-term assets |
— |
|
1,608 |
|
Accounts payable |
(2,605) |
|
2,020 |
|
Contract termination liability |
— |
|
(667) |
|
Deferred revenue |
(1,090) |
|
— |
|
Operating lease liabilities |
259 |
|
(75) |
|
Other liabilities and customer deposits |
1,350 |
|
2,173 |
|
Accrued liabilities and interest payable |
(1,959) |
|
6,792 |
|
Net cash used in operating activities |
(21,121) |
|
(3,479) |
|
Investing Activities |
|
|
|
|
Purchases of property, plant, and equipment |
(19,480) |
|
(17,008) |
|
Purchases of intangible assets |
(84) |
|
(92) |
|
Proceeds from sale and settlement of property, plant, and equipment |
1,460 |
|
— |
|
|
(51,415) |
|
— |
|
Deposits on equipment |
(9,374) |
|
(1,028) |
|
Net cash used in investing activities |
(78,893) |
|
(18,128) |
|
Financing Activities |
|
|
|
|
Proceeds from common stock warrant exercises |
2,553 |
|
9,455 |
|
Net proceeds from sale of common stock on SEPA |
18,928 |
|
6,176 |
|
Proceeds from notes |
24,500 |
|
18,434 |
|
Net proceeds from sale of common stock on ATM |
151,204 |
|
22,799 |
|
Net proceeds from equity issuance |
— |
|
4,364 |
|
Payments on notes and deferred financing costs |
(40,502) |
|
(6,938) |
|
Payments on ATM |
— |
|
— |
|
Payments on Series B dividends |
(2,058) |
|
— |
|
Costs on treasury stock |
(172) |
|
— |
|
Payments on financing lease liabilities |
(170) |
|
— |
|
Purchase of membership interest of Dorothy 1A and Dorothy 1B |
(25,266) |
|
— |
|
Contributions from non-controlling interest |
10,918 |
|
22,078 |
|
Distributions to non-controlling interest |
(5,705) |
|
(4,753) |
|
Net cash provided by financing activities |
134,230 |
|
71,615 |
|
|
|
|
|
|
Increase (decrease) in cash & restricted cash |
34,216 |
|
50,008 |
|
Cash & restricted cash – beginning of period |
88,843 |
|
10,453 |
|
Cash & restricted cash – end of period |
$ 123,059 |
|
$ 60,461 |
|
|
|
|
|
|
Supplemental Disclosure of Cash Flow Information |
|
|
|
|
Interest paid on debt |
3,415 |
|
1,081 |
|
Fair value consideration for Green Cloud issuance of shares |
— |
|
810 |
|
Construction in progress included in accounts payable and accrued liabilities |
2,771 |
|
— |
|
Noncash deferred financing cost accrual |
— |
|
1,078 |
|
Warrant consideration in relation to Generate and Yorkville Warrants |
3,249 |
|
2,635 |
|
Noncash financing cost accrual |
— |
|
647 |
|
Noncash deferred investing fees for joint venture |
1,307 |
|
— |
|
Noncash membership distribution accrual |
270 |
|
— |
|
Warrant adjustment |
682 |
|
— |
|
Noncash non-controlling interest contributions |
— |
|
2,675 |
|
Noncash activity right-of-use assets adjustment |
430 |
|
3,441 |
|
The accompanying notes are an integral part of these unaudited condensed consolidated financial statements. |
|||
|
EBITDA and Adjusted EBITDA Tables: |
||||||||
|
Reconciliations of EBITDA and Adjusted EBITDA to net loss, the most comparable GAAP financial metric, for historical periods are presented in the table below: |
||||||||
|
|
||||||||
|
(Dollars in thousands) |
|
Three Months Ended |
|
Nine Months Ended |
||||
|
|
|
2026 |
|
2025 |
|
2026 |
|
2025 |
|
|
|
|
|
|
|
|
|
|
|
Net loss |
|
$ (34,329) |
|
$ (25,787) |
|
$ (74,855) |
|
$ (40,921) |
|
Interest expense |
|
1,274 |
|
1,212 |
|
5,922 |
|
3,246 |
|
Income tax benefit |
|
(1,507) |
|
(666) |
|
(2,678) |
|
(1,697) |
|
Depreciation and amortization |
|
5,314 |
|
4,119 |
|
15,649 |
|
11,985 |
|
EBITDA |
|
(29,248) |
|
(21,122) |
|
(55,962) |
|
(27,387) |
|
|
|
|
|
|
|
|
|
|
|
Adjustments: Non-cash or Non-recurring items |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Stock-based compensation costs |
|
15,879 |
|
1,882 |
|
35,581 |
|
5,671 |
|
Loss on sale of fixed assets and deposit on equipment |
|
65 |
|
780 |
|
618 |
|
802 |
|
Right of first refusal amortization gain |
|
(45) |
|
— |
|
(180) |
|
— |
|
Accretion of asset retirement obligation |
|
164 |
|
— |
|
243 |
|
— |
|
Gain on transformer settlement |
|
— |
|
— |
|
(1,409) |
|
— |
|
SEPA commitment fee |
|
— |
|
— |
|
250 |
|
— |
|
Fair value adjustment loss (gain) |
|
— |
|
22,047 |
|
(246) |
|
22,165 |
|
Fair value on placement agent warrants financing fee |
|
— |
|
146 |
|
— |
|
146 |
|
Impairment on fixed assets and intangibles |
|
— |
|
— |
|
70 |
|
12 |
|
Loss (gain) on debt extinguishment and revaluation, net |
|
5,729 |
|
(10,107) |
|
9,926 |
|
(10,658) |
|
Adjusted EBITDA |
|
$ (7,456) |
|
$ (6,374) |
|
$ (11,109) |
|
$ (9,249) |
The following table represents the Adjusted EBITDA activity between each three-month period from January 1, 2026 through September 30, 2026.
|
(Dollars in thousands) |
|
Three months |
|
Three months |
|
Three months |
|
|
|
|
|
|
|
|
|
Net loss |
|
$ (17,902) |
|
$ (22,624) |
|
$ (34,329) |
|
Interest expense |
|
1,481 |
|
3,167 |
|
1,274 |
|
Income tax benefit |
|
(624) |
|
(547) |
|
(1,507) |
|
Depreciation and amortization |
|
4,603 |
|
5,732 |
|
5,314 |
|
EBITDA |
|
(12,442) |
|
(14,272) |
|
(29,248) |
|
|
|
|
|
|
|
|
|
Adjustments: Non-cash or Non-recurring items |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Stock-based compensation costs |
|
10,222 |
|
9,480 |
|
15,879 |
|
(Gain) loss on sale of fixed assets and deposits on equipment |
|
(32) |
|
585 |
|
65 |
|
Right of first refusal amortization gain |
|
(90) |
|
(45) |
|
(45) |
|
Accretion of asset retirement obligation |
|
— |
|
79 |
|
164 |
|
Gain on transformer settlement |
|
— |
|
(1,409) |
|
— |
|
SEPA commitment fee |
|
250 |
|
— |
|
— |
|
Fair value adjustment, net |
|
— |
|
(246) |
|
— |
|
Impairment on fixed assets and intangibles |
|
— |
|
70 |
|
— |
|
Loss on debt extinguishment and revaluation, net |
|
— |
|
4,197 |
|
5,729 |
|
Adjusted EBITDA |
|
$ (2,092) |
|
$ (1,561) |
|
$ (7,456) |
The following table represents the Adjusted EBITDA activity between each three-month period from January 1, 2025 through December 31, 2025.
|
(Dollars in thousands) |
|
Three months |
|
Three months |
|
Three months |
|
Three months |
|
|
|
|
|
|
|
|
|
|
|
Net loss |
|
$ (7,354) |
|
$ (7,780) |
|
$ (25,787) |
|
$ (16,070) |
|
Interest expense |
|
838 |
|
1,196 |
|
1,212 |
|
1,589 |
|
Income tax benefit |
|
(425) |
|
(608) |
|
(666) |
|
(617) |
|
Depreciation and amortization |
|
3,879 |
|
3,989 |
|
4,119 |
|
4,358 |
|
EBITDA |
|
(3,062) |
|
(3,203) |
|
(21,122) |
|
(10,740) |
|
|
|
|
|
|
|
|
|
|
|
Adjustments: Non-cash items or Non-recurring items |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Stock-based compensation costs |
|
1,847 |
|
1,942 |
|
1,882 |
|
4,895 |
|
Loss on sale of fixed assets and credit on equipment deposits |
|
— |
|
22 |
|
780 |
|
349 |
|
Fair value on placement agent warrant and financing fees |
|
— |
|
— |
|
146 |
|
— |
|
Fair value adjustment loss |
|
118 |
|
— |
|
22,047 |
|
1,516 |
|
Impairment on fixed assets |
|
— |
|
12 |
|
— |
|
— |
|
(Gain) loss on debt extinguishment and revaluation, net |
|
(551) |
|
— |
|
(10,107) |
|
— |
|
Adjusted EBITDA |
|
$ (1,648) |
|
$ (1,227) |
|
$ (6,374) |
|
$ (3,980) |
 View original content to download multimedia:https://www.prnewswire.com/news-releases/soluna-reports-q326-results-begins-construction-work-at-kati-2-and-dorothy-3-302940939.html
SOURCE Soluna Holdings, Inc.
FAQ
AI-generated questions and answers. How Rhea-AI works. Not financial advice.
What were Soluna's Q3 2026 revenue and net loss?
Soluna reported $15.1 million in revenue and a $34.3 million net loss for the quarter ended September 30, 2026. Revenue increased 80% year over year, or 29% excluding gross presentation of pass-through electricity. Net loss widened from $25.8 million a year earlier.
What is Soluna's Dorothy 3 agreement with Applied Digital?
The October 20 subscription agreement provides for a joint venture owned 51% by Applied Digital and 49% by Soluna for a planned 50 MW critical IT Phase 1 AI and high-performance computing facility. Closing is expected by year-end 2026, subject to remaining conditions. ChronoScale signed a non-binding letter of intent to lease the facility.
What did Soluna use its 2026 equity fundraising for?
The $170.1 million raised year to date through its at-the-market program and Yorkville equity purchase agreement funded the Briscoe Wind acquisition, project capital spending, buyouts of joint-venture partners at Dorothy 1A and 1B, and $40.5 million of debt repayments. Those repayments included the August Generate prepayment.
What do Soluna's ERCOT Base Load classifications mean for Kati and Dorothy?
The classifications preserve 266 MW of existing interconnection capacity and exempt it from further reliability evaluation and megawatt allocation in the Batch Zero study, pending ERCOT verification. They cover 166 MW at Kati, including the planned Kati 2 expansion, and 100 MW at Dorothy. An additional 50 MW Dorothy request is under study.