
U.S. consumer debt hit $18.56 trillion in Q3 2026 as non-mortgage delinquencies stabilized
Bankcard and auto loan severe delinquency rates declined even as balances in both categories increased.
Sentiment and the balance of points
Rhea-AI Sentiment reads the wording of the document, how positive or negative its language is on a 1 to 5 scale. The balance of points shown with the takes weighs what the document actually discloses, so the two can disagree, for example when a trial that missed its main goal is described in upbeat language.
Rhea-AI Summary
Equifax (NYSE: EFX) released its third-quarter consumer credit report, showing U.S. consumer debt reached $18.56 trillion in September 2026. Total debt increased 2.9% year over year and 0.6% month over month. First mortgage balances reached $13,075 billion, up 2.8% annually. Home equity lines of credit, which let homeowners borrow against their equity, grew 13.3% annually to $461.9 billion.
Non-mortgage debt totaled $4.79 trillion. Write-offs through September were $104.9 billion, versus $104.4 billion a year earlier. Bankcard balances rose 3.9% annually to $1,125.7 billion, while the rate of payments more than 60 days overdue fell 9 basis points to 2.74%. Auto loan balances increased 3.7% to $1,745 billion; student loan balances fell 4.0% to $1,287 billion. Equifax cautioned that elevated borrowing costs and persistent inflation continued to stretch lower-income household budgets.
Key Figures
- Total U.S. consumer debt
- $18.56 trillion; +2.9% year-over-year
- September 2026
- HELOC balances
- $461.9 billion; +13.3% year-over-year
- September 2026 versus September 2025
- First mortgage loans
- $13.08 trillion
- Outstanding in September 2026
- Non-mortgage debt write-offs
- $104.9 billion
- Year-to-date through September 2026; $104.4 billion the previous year
- Severe bankcard delinquency rate
- 2.74%; down 9 basis points
- More than 60 days past due; change from September 2025
- Private label card severe delinquency rate
- 3.85%; down 40 basis points
- More than 60 days past due; change from September 2025
- Non-mortgage consumer debt
- $4.79 trillion
- September 2026
Key Terms
heloc financial
basis points financial
AI-generated analysis. How Rhea-AI works. Not financial advice.


Equifax national Market Pulse data shows HELOC debt growth and stabilizing non-mortgage write-offs amid resilient consumer borrowing
Highlights:
- Total
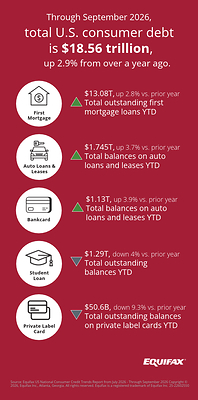
U.S . consumer debt rose2.9% year-over-year to$18.56 trillion - Mortgage obligations remain the largest driver of consumer debt, with total outstanding first mortgage loans reaching
$13.08 trillion - Non-mortgage debt write-offs year-to-date through September 2026 came in at
$104.9 billion $104.4 billion
Continued debt growth driven by mortgage and double-digit HELOC expansion
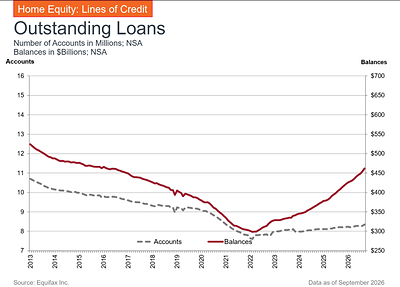
In September 2026, HELOC balances expanded to
"Homeowners continue to leverage their accumulated home equity, as evidenced by double-digit year-over-year growth in HELOC balances," said Emmaline Aliff, Advisory Leader at Equifax. "Even as overall borrowing expands, mortgage-related debt remains the cornerstone of consumer balance sheets, offering structural stability backed by real estate assets."
Stabilization across non-mortgage portfolios as write-offs hold steady and delinquencies ease
- Non-mortgage consumer debt reached
$4.79 trillion $1.745 trillion $1.287 trillion $1.126 trillion - Year-to-date non-mortgage write-offs totaled
$104.9 billion $104.4 billion - Severe delinquency rates (more than 60 days past due) across key revolving categories like bankcards were down 9 basis points to
2.74% from September 2025, while private label cards were down 40 basis points to3.85% . - Bankcard write-offs stand at 52.4 basis points, down from 55.5 basis points a year prior.
"There is a remarkably resilient segment of the population managing economic pressures with steady repayment behavior, yet we cannot overlook the consumers who are experiencing real financial friction," added Aliff. "The top-line improvement is a positive sign, but the underlying reality is complex as elevated borrowing costs and persistent inflation continue to stretch household budgets across lower-income tiers."
Diverse trends across auto, bankcard, and student loan asset classes
- Auto loan and lease balances rose
3.7% year-over-year to$1.745 trillion 1.50% . - Bankcard balances grew
3.9% to$1.13 trillion 20.3% . - Meanwhile, student loan balances continued their downward trend, falling
4.0% year-over-year to$1.29 trillion
Month-over-month and year-over-year results
Total consumer debt balances
|
Month |
Total Consumer Debt |
MoM Change (%) |
YoY Change (%) |
|
July 2026 |
|
-0.1 % |
1.6 % |
|
August 2026 |
|
1.2 % |
3.0 % |
|
September 2026 |
|
0.6 % |
2.9 % |
First mortgage balances
|
Month |
First Mortgage Balances |
MoM Change (%) |
YoY Change (%) |
|
July 2026 |
|
-0.2 % |
1.2 % |
|
August 2026 |
|
1.5 % |
3.0 % |
|
September 2026 |
|
0.5 % |
2.8 % |
Home equity lines of credit (HELOC) balances
|
Month |
HELOC Balances |
MoM Change (%) |
YoY Change (%) |
|
July 2026 |
|
0.8 % |
12.5 % |
|
August 2026 |
|
1.3 % |
12.4 % |
|
September 2026 |
|
1.7 % |
13.3 % |
Auto loan balances
|
Month |
Auto Loan Balances |
MoM Change (%) |
YoY Change (%) |
|
July 2026 |
|
0.4 % |
3.3 % |
|
August 2026 |
|
0.1 % |
3.3 % |
|
September 2026 |
|
0.6 % |
3.7 % |
Bankcard balances
|
Month |
Bankcard Balances |
MoM Change (%) |
YoY Change (%) |
|
July 2026 |
|
0.5 % |
3.8 % |
|
August 2026 |
|
0.6 % |
3.6 % |
|
September 2026 |
|
0.4 % |
3.9 % |
Student loan balances
|
Month |
Student Loan Debt |
MoM Change (%) |
YoY Change (%) |
|
July 2026 |
|
-0.2 % |
-3.2 % |
|
August 2026 |
|
-0.2 % |
-3.4 % |
|
September 2026 |
|
0.3 % |
-4.0 % |
Equifax has been tracking
ABOUT EQUIFAX INC.
At Equifax (NYSE: EFX), we believe knowledge drives progress. As a global data, analytics, and technology company, we play an essential role in the global economy by helping financial institutions, companies, employers, and government agencies make critical decisions with greater confidence. Our unique blend of differentiated data, analytics, and cloud technology drives insights to power decisions to move people forward. Headquartered in Atlanta and supported by nearly 15,000 employees worldwide, Equifax operates or has investments in 24 countries in North America, Central and South America, Europe, and the Asia Pacific region. For more information, visit Equifax.com.
FOR MORE INFORMATION:
Tiffany Smith for Equifax
mediainquiries@equifax.com
 View original content to download multimedia:https://www.prnewswire.com/news-releases/us-consumer-debt-hit-18-56-trillion-in-q3-2026-as-non-mortgage-delinquencies-stabilized-302935687.html
SOURCE Equifax Inc.
FAQ
AI-generated questions and answers. How Rhea-AI works. Not financial advice.
How much did U.S. consumer debt rise in Equifax's September 2026 data?
Total U.S. consumer debt rose 2.9% year over year to $18.56 trillion in September 2026. It increased 0.6% from August, with mortgage debt and home equity lines of credit driving growth.
What did Equifax report about auto loan and private label card delinquencies in September 2026?
Severe delinquency rates fell 7 basis points to 1.50% for auto loans and 40 basis points to 3.85% for private label cards compared with September 2025. Severe delinquency means payments more than 60 days past due.