
Oak View Bankshares, Inc. Announces Strong Third Quarter Performance
Higher quarterly earnings accompanied lower deposits, reduced available liquidity and an equity decline driven primarily by unrealized losses.
Sentiment and the balance of points
Rhea-AI Sentiment reads the wording of the document, how positive or negative its language is on a 1 to 5 scale. The balance of points shown with the takes weighs what the document actually discloses, so the two can disagree, for example when a trial that missed its main goal is described in upbeat language.
Rhea-AI Summary
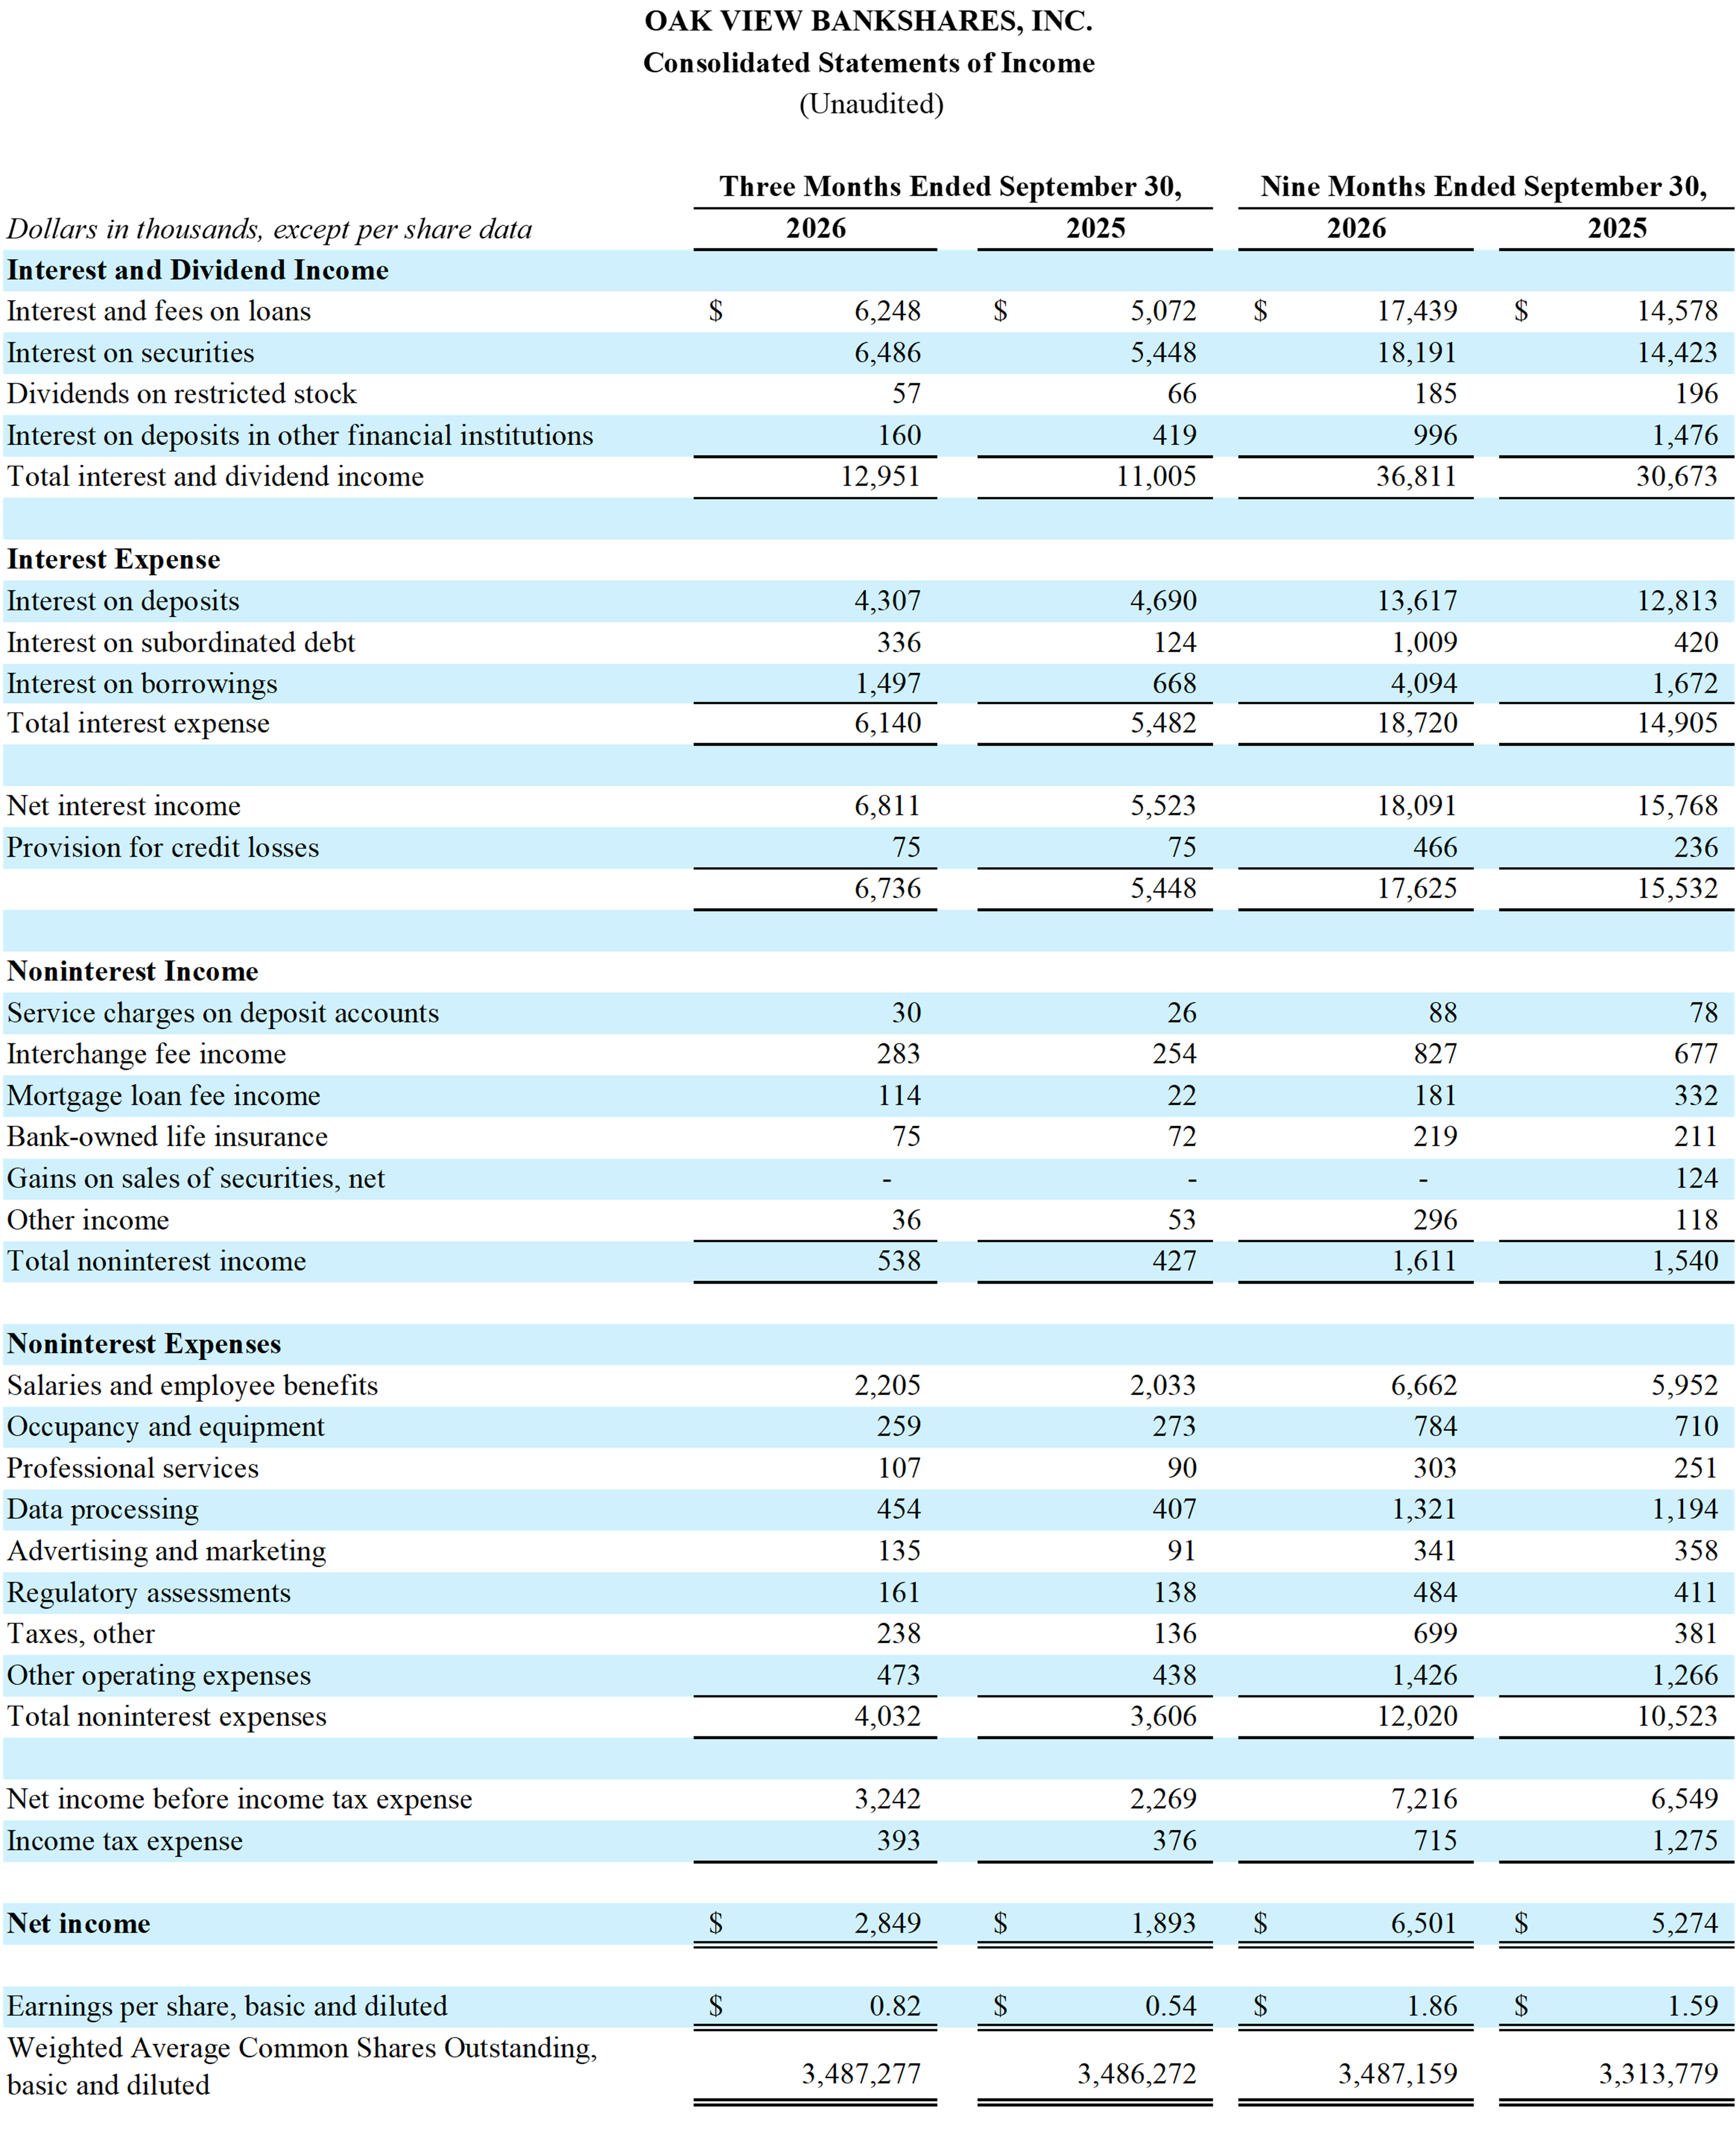
Oak View Bankshares (OAKV) reported third-quarter 2026 net income of $2.85 million, up from the same quarter a year earlier. Basic and diluted earnings per share rose to $0.82 from $0.54, while net income increased from $1.89 million. Nine-month net income reached $6.50 million versus $5.27 million, with earnings per share of $1.86 versus $1.59.
Quarterly net interest margin rose to 3.13% from 2.98%. Balance sheet actions included selling $50.00 million of Treasury securities, repaying $30.00 million of short-term borrowings and terminating $90.50 million in notional hedged positions. These actions partly generated an approximately $367,000 non-recurring net interest income benefit. Loans rose to $399.24 million from $349.89 million at year-end, but deposits and available liquidity declined. Shareholders’ equity fell to $48.17 million from $57.74 million, primarily from unrealized losses. The Bank remained above all regulatory well-capitalized standards.
How this balance works
Rhea-AI gives every point it takes from this document a weight. Minor counts 1, Moderate 3 and Major 9, so one Major point outweighs several Minor ones. The bar adds up the weights on each side, and when neither side holds more than 65% of the total the balance reads Mixed.
It reads the document as published, with the same rules for every company, and it does not look at what the market expected or at how the stock traded, so a point can be objectively good on a day the stock falls.
Rhea-AI Sentiment measures something else, the tone of the wording.
Hollow bars mark forward-looking points. How the balance works
Positive
- Moderate pointThird-quarter net income rose to $2.85 million from $1.89 million in 2025.
- Moderate pointShort-term borrowing repayments totaled $30.00 million during the quarter. 44% of market cap
- Moderate pointBalance sheet actions partly generated an approximately $367,000 non-recurring net interest income benefit.
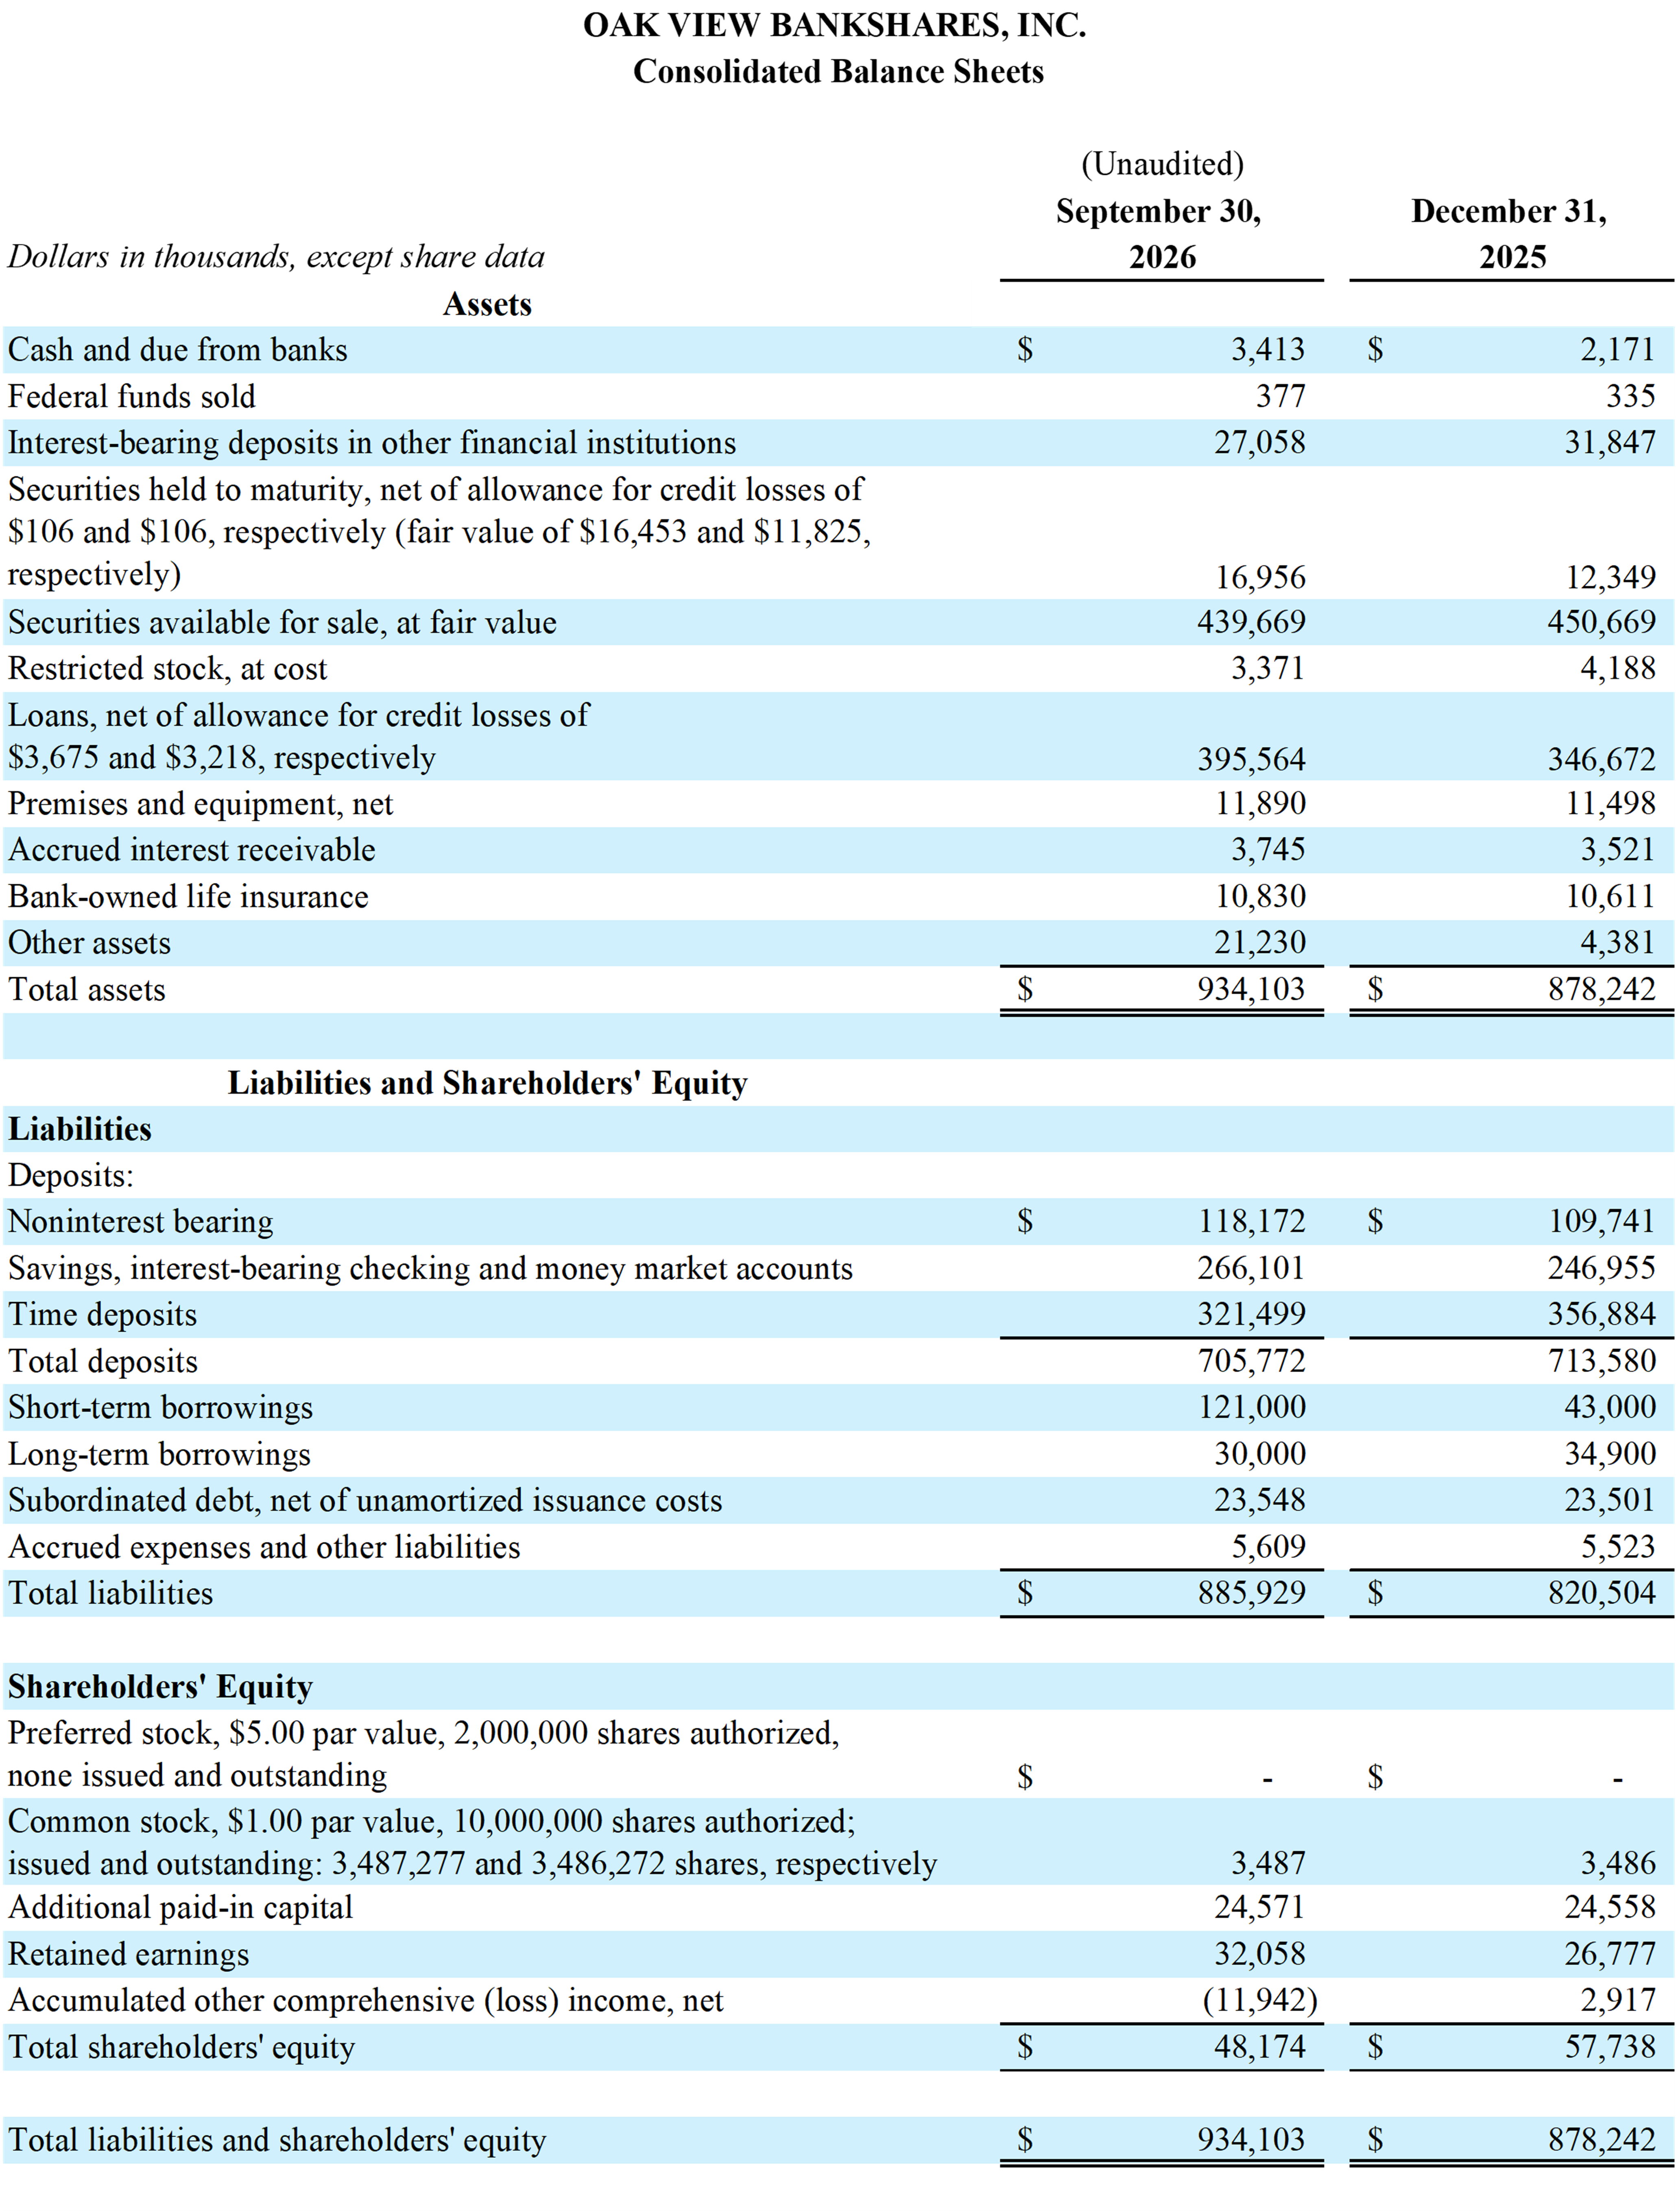
- Moderate pointTotal assets increased to $934.10 million from $878.24 million at December 31, 2025.
- Moderate pointLoans increased to $399.24 million from $349.89 million at December 31, 2025.
- Moderate pointCore deposits increased $48.38 million from December 31, 2025.
- Moderate pointThird-quarter net interest margin rose to 3.13% from 2.98% in 2025.
- Moderate pointThird-quarter net interest income before credit-loss provisions rose to $6.81 million from $5.52 million in 2025.
14 minor points
- Minor pointThird-quarter basic and diluted EPS increased to $0.82 from $0.54 in 2025.
- Minor pointNine-month net income increased to $6.50 million from $5.27 million in 2025.
- Minor pointNine-month basic and diluted EPS rose to $1.86 from $1.59 in 2025.
- Minor pointThird-quarter return on average assets rose to 1.17% from 0.93% in 2025.
- Minor pointThird-quarter return on average equity increased to 19.89% from 15.90% in 2025.
- Minor point. Forward-looking: it has not happened yet and may not happen.Management expects balance sheet actions to improve liquidity and potentially enhance net interest income.
- Minor pointCredit quality included no nonperforming, nonaccrual or 90-day-past-due loans at September 30, 2026; quarterly charge-offs were zero.
- Minor pointBank capital exceeded well-capitalized standards: 17.08% total capital, 16.31% Tier 1 and Common Equity Tier 1, 8.54% leverage.
- Minor pointNine-month net interest income before credit-loss provisions rose to $18.09 million from $15.77 million in 2025.
- Minor pointAverage earning assets rose to $930.66 million quarterly and $906.11 million year-to-date, versus $760.69 million and $720.30 million.
- Minor pointThird-quarter funding cost declined to 2.69% from 2.87% in 2025, including noninterest-bearing deposits.
- Minor pointInterchange income rose to $283,000 quarterly and $827,000 year-to-date, versus $254,000 and $677,000 in 2025.
- Minor pointQuarterly mortgage fees rose to $114,000 from $22,000 in 2025; nine-month fees fell to $181,000 from $332,000.
- Minor pointNet overhead relative to average assets fell to 1.43% quarterly and 1.47% year-to-date, versus 1.56% and 1.59%.
Negative
- Moderate pointShareholders’ equity fell to $48.17 million from $57.74 million at year-end, primarily reflecting unrealized losses.
- Moderate pointAvailable liquidity declined to $419.40 million from $574.44 million at December 31, 2025.
- Moderate pointNoninterest expenses rose to $4.03 million quarterly and $12.02 million year-to-date, versus $3.61 million and $10.52 million.
- Minor pointAccumulated other comprehensive loss reached $11.94 million, or 2.72% of available-for-sale securities, at September 30, 2026.
- Minor pointTotal deposits declined to $705.77 million from $713.58 million at year-end; brokered deposits fell $56.19 million.
6 minor points
- Minor pointNine-month net interest margin fell to 2.87% from 2.96% in 2025.
- Minor pointNine-month return on average assets declined to 0.92% from 0.93% in 2025.
- Minor pointNine-month return on average equity fell to 15.24% from 15.99% in 2025.
- Minor pointNine-month credit-loss provisions increased to $466,000 from $236,000 in 2025, primarily driven by loan growth.
- Minor pointEarning-asset yields fell to 5.75% quarterly and 5.63% year-to-date, versus 5.84% and 5.73% in 2025.
- Minor pointNine-month funding cost rose to 2.83% from 2.82% in 2025, including noninterest-bearing deposits.
AI-generated analysis. How Rhea-AI works. Not financial advice.




WARRENTON, VA / ACCESS Newswire / October 30, 2026 / Oak View Bankshares, Inc. (the "Company") (OTCID:OAKV), parent company of Oak View National Bank (the "Bank"), reported net income of
Basic and diluted earnings per share were
Michael Ewing, CEO and Chairman of the Board, said, "Our third quarter results reflect the continued strength of our community banking franchise and the successful execution of our long-term strategic objectives. During the quarter, our tireless team continued to earn lending and deposit market share. We maintained exceptional asset quality with no nonperforming loans, no nonaccrual loans, no loans past due 90 days or more and no loan charge-offs. Finally, we took advantage of market opportunities to execute several balance sheet management initiatives, which further balanced our interest rate risk profile, while maintaining robust on- and off-balance sheet liquidity." Mr. Ewing continued, "Our team is focused and energized, knowing that our balance sheet is well-positioned to thrive across multiple rate scenarios and over time. As always, everything we do aims to deliver long-term value to our shareholders, customers, and communities."
Selected Highlights:
- The return on average assets and return on average equity for the quarter and nine months ended September 30, 2026, reflect strong earnings performance and disciplined balance sheet management. Return on average assets was
1.17% and return on average equity was19.89% for the quarter ended September 30, 2026, compared to0.93% and15.90% , respectively, for the quarter ended September 30, 2025. Return on average assets was0.92% and return on average equity was15.24% for the nine months ended September 30, 2026, compared to0.93% and15.99% , respectively, for the nine months ended September 30, 2025. - Several balance sheet management initiatives were executed during the quarter, including the sale of
$50.00 million of U.S. Treasury securities, the repayment of$30.00 million in short-term borrowings, and the termination of$90.50 million (notional value) of hedged positions. These actions, in part, generated a non-recurring benefit of approximately$367,000 t o net interest income while, on a go-forward basis, are expected to improve liquidity, further optimize the interest rate risk profile and potentially enhance net interest income from the relief of short-term borrowings. - Total assets were
$934.10 million on September 30, 2026, compared to$878.24 million on December 31, 2025, an increase of$55.86 million . - Total loans were
$399.24 million on September 30, 2026, compared to$349.89 million on December 31, 2025, an increase of$49.35 million . - The total carrying value of debt securities was
$456.63 million on September 30, 2026, compared to$463.02 million on December 31, 2025, a decrease of$6.39 million . - Total deposits were
$705.77 million on September 30, 2026, compared to$713.58 million on December 31, 2025, a decrease of$7.81 million , which reflected an increase in core deposits of$48.38 million and a decrease in brokered deposits of$56.19 million . - Asset quality continues to be outstanding. No loans were charged off during the quarter, and as of September 30, 2026, there were no nonperforming loans, nonaccrual loans, or loans past due 90 days or more.
- Liquidity remains strong, with cash, unencumbered securities available for sale, and available secured and unsecured borrowing capacity totaling
$419.40 million as of September 30, 2026, compared to$574.44 million as of December 31, 2025. - Capital levels remained a key strength as of September 30, 2026. The Bank exceeded all regulatory "well-capitalized" standards, reporting a total capital ratio of
17.08% , Tier 1 capital and Common Equity Tier 1 capital ratios of16.31% , and a leverage ratio of8.54% at quarter-end.
Net Interest Income
The net interest margin was
The net interest margin was
Noninterest Income
Noninterest income was
Significant changes in noninterest income for the three and nine months ended September 30, 2026, compared to the same periods in 2025, were:
- Interchange fee income was
$283,000 and$254,000 for the quarters ended September 30, 2026, and 2025, respectively. Interchange fee income was$827,000 and$677,000 for the nine months ended September 30, 2026, and 2025, respectively. These fluctuations were primarily related to transaction volume. - Mortgage loan fee income was
$114,000 and$22,000 for the quarters ended September 30, 2026, and 2025, respectively. Mortgage loan fee income was$181,000 and$332,000 for the nine months ended September 30, 2026, and 2025, respectively. The quarterly fluctuations were primarily due to transaction volume while the fluctuations for the nine-month periods were the result of the current interest rate environment compared to the same periods of 2025.
Noninterest Expense
Noninterest expenses were
Asset Quality
With no nonperforming loans, nonaccrual loans or loans 90 days or more past due on September 30, 2026, these asset quality metrics continued to reflect the Bank's conservative underwriting practices and disciplined credit administration.
The allowance for credit losses related to the loan portfolio was
The provision for credit losses was
Shareholders' Equity & Regulatory Capital
Shareholders' equity was
Accumulated other comprehensive loss was
About Oak View Bankshares, Inc. and Oak View National Bank
The Company's common stock is listed for trading on the OTC Market Group's OTCID-Basic Market, http://www.otcmarkets.com, under the ticker symbol OAKV.
The Company's common stock closed at a price of
The Company's book value per share was
Oak View Bankshares, Inc. is the parent bank holding company for Oak View National Bank, a locally owned and managed community bank serving Fauquier, Culpeper, Rappahannock, and surrounding counties. For more information about Oak View Bankshares, Inc. and Oak View National Bank, please visit our website at www.oakviewbank.com. Member FDIC.
For additional information, contact Tammy Frazier, Executive Vice President & Chief Financial Officer, Oak View Bankshares, Inc., at 540-359-7155.
Cautionary Note Regarding Forward-Looking Statements
Any statements in this release about expectations, beliefs, plans, objectives, assumptions or future events or performance are not historical facts and are forward-looking statements. These statements are often, but not always, made through the use of words or phrases such as "may," "should," "could," "would," "predict," "potential," "believe," "likely," "expect," "anticipate," "seek," "estimate," "intend," "plan," "project" and similar expressions. Accordingly, these statements involve estimates, assumptions, and uncertainties, and actual results may differ materially from those expressed in such statements. The following factors could cause the Company's actual results to differ materially from those projected in the forward-looking statements made in this document: changes in assumptions underlying the establishment of allowances for credit losses, and other estimates; the risks of changes in interest rates on levels, composition and costs of deposits, loan demand, and the values and liquidity of loan collateral, securities, and interest sensitive assets and liabilities; the effects of future economic, business and market conditions; legislative and regulatory changes, including changes in banking, securities, and tax laws and regulations and their application by our regulators; the Company's ability to maintain adequate liquidity by retaining deposit customers and secondary funding sources, especially if the Company's or banking industry's reputation becomes damaged; computer systems and infrastructure may be vulnerable to attacks by hackers or breached due to employee error, malfeasance, or other disruptions despite security measures implemented by the Company; risks inherent in making loans, such as repayment risks and fluctuating collateral values; governmental monetary and fiscal policies; changes in accounting policies, rules and practices; competition with other banks and financial institutions, and companies outside of the banking industry, including companies that have substantially greater access to capital and other resources; demand, development and acceptance of new products and services; problems with technology utilized by the Company; changing trends in customer profiles and behavior; success of acquisitions and operating initiatives, changes in business strategy or development of plans, and management of growth; reliance on senior management, including the ability to attract and retain key personnel; and inadequate design or circumvention of disclosure controls and procedures or internal controls. These factors could cause actual results or outcomes to differ materially from those expressed in any forward-looking statements made by the Company, and you should not place undue reliance on any such forward-looking statements. Any forward-looking statement speaks only as of the date on which it is made, and the Company does not undertake any obligation to update any forward-looking statement or statements to reflect events or circumstances after the date on which such statement is made or to reflect the occurrence of unanticipated events. New factors emerge from time to time, and it is not possible for the Company to predict which will arise. In addition, the Company cannot assess the impact of each factor on the Company's business or the extent to which any factor, or combination of factors, may cause actual results to differ materially from those contained in any forward-looking statements.
SOURCE: Oak View Bankshares, Inc.
View the original press release on ACCESS Newswire
FAQ
AI-generated questions and answers. How Rhea-AI works. Not financial advice.