
Commencement Bancorp, Inc. Announces Third Quarter 2026 Results
Loan growth accompanied a quarterly deposit decline, while two credit relationships moved to nonaccrual status.
Sentiment and the balance of points
Rhea-AI Sentiment reads the wording of the document, how positive or negative its language is on a 1 to 5 scale. The balance of points shown with the takes weighs what the document actually discloses, so the two can disagree, for example when a trial that missed its main goal is described in upbeat language.
Rhea-AI Summary
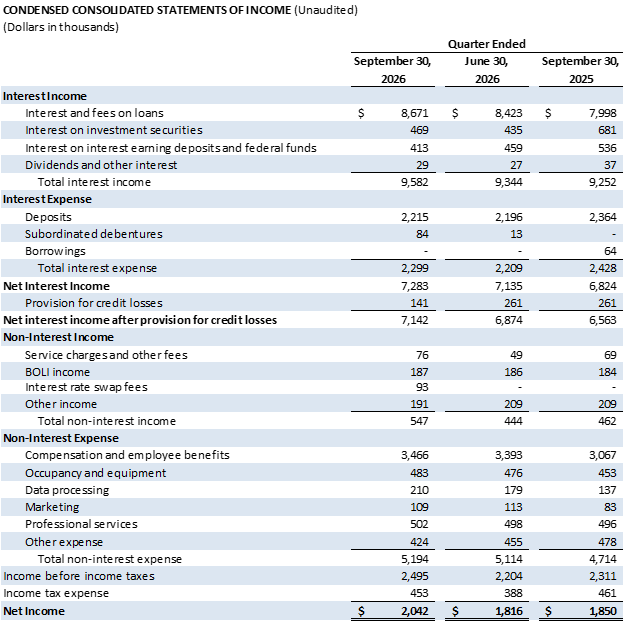
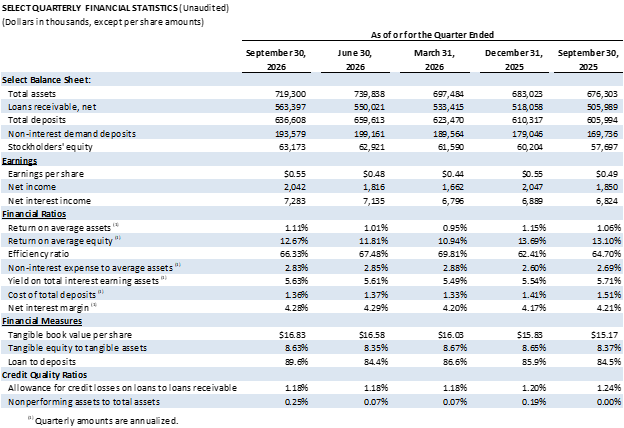
Commencement Bancorp (CBWA) reported third-quarter 2026 net income of $2.0 million, improving from both the preceding quarter and a year earlier. Earnings per share were $0.55, compared with $0.48 in the second quarter and $0.49 a year earlier. Net interest income rose 2.1% sequentially to $7.3 million. Net interest margin was 4.28%, versus 4.29% in the preceding quarter and 4.21% a year earlier.
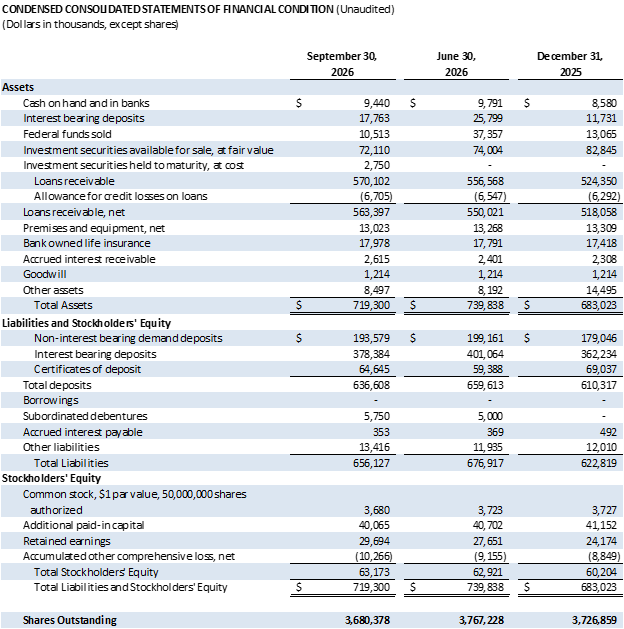
At September 30, loans reached $570.1 million, up $13.5 million from June 30, while deposits fell $23.0 million to $636.6 million. Nonperforming assets increased to $1.8 million, or 0.25% of assets, from $488,000, or 0.07%, following two credit relationships moving to nonaccrual status. The company raised another $750,000 through fixed-to-floating subordinated notes during the quarter, bringing the total to $5.8 million. Non-interest expense increased 1.6% sequentially.
How this balance works
Rhea-AI gives every point it takes from this document a weight. Minor counts 1, Moderate 3 and Major 9, so one Major point outweighs several Minor ones. The bar adds up the weights on each side, and when neither side holds more than 65% of the total the balance reads Mixed.
It reads the document as published, with the same rules for every company, and it does not look at what the market expected or at how the stock traded, so a point can be objectively good on a day the stock falls.
Rhea-AI Sentiment measures something else, the tone of the wording.
Positive
- Moderate pointThird-quarter net income of $2.0 million exceeded $1.8 million sequentially and $1.9 million a year earlier.
- Moderate pointNet interest income of $7.3 million increased 2.1% sequentially and 6.7% year over year.
- Moderate pointLoans of $570.1 million increased $13.5 million from June 30, or 9.6% annualized.
- Moderate pointReturn on average assets of 1.11% exceeded 1.01% sequentially and 1.06% a year earlier.
- Moderate pointAnnualized deposit growth was 5.8% for the nine months ended September 30, 2026.
- Moderate pointTotal deposit cost of 1.36% fell from 1.37% sequentially and 1.51% a year earlier.
- Moderate pointNon-interest income increased $103,000, or 23.2%, sequentially, driven by $93,000 of interest-rate swap income.
7 minor points
- Minor pointThird-quarter EPS of $0.55 exceeded $0.48 sequentially and $0.49 a year earlier.
- Minor point$750,000 additional subordinated-note funding raised in the third quarter is intended to support organic growth.
- Minor pointReturn on average common equity of 12.67% exceeded 11.81% sequentially but trailed 13.10% a year earlier.
- Minor pointCredit-loss provision of $141,000 decreased $120,000 sequentially, including a $16,000 unfunded-credit provision reversal.
- Minor pointClassified loans fell to 0.86% of loans at September 30 from 0.89% at June 30.
- Minor pointNoninterest-bearing deposits reached 30.4% of deposits, versus 30.2% at June 30 and 29.3% at December 31.
- Minor pointLoan interest income increased $248,000 sequentially, or 2.9%, and $673,000 year over year.
Negative
- Moderate pointNonperforming assets rose to $1.8 million, or 0.25% of assets, from $488,000, or 0.07%, sequentially.
- Moderate pointDeposits fell $23.0 million to $636.6 million from June 30; the company cited primarily seasonality.
- Moderate pointTotal assets decreased $20.5 million to $719.3 million from June 30.
- Moderate pointUnrealized investment losses increased $1.6 million during the third quarter. 2.3% of market cap
- Moderate pointLoan commitments originated totaled $40.0 million, below $60.0 million sequentially and $43.0 million a year earlier. 56% of market cap
- Moderate pointNet loan yield fell to 6.19% from 6.25% sequentially and declined eight basis points year over year.
- Moderate pointInterest-bearing liability cost increased to 2.02% from 1.94% sequentially, reflecting subordinated-debenture issuance.
- Moderate pointNon-interest expense increased $80,000, or 1.6%, sequentially and $480,000 year over year.
11 minor points
- Minor pointFederal funds sold decreased $26.8 million to $10.5 million as deposits declined during the quarter.
- Minor pointInvestment securities available for sale fell 2.6% to $72.1 million from $74.0 million at June 30.
- Minor pointNet interest margin of 4.28% fell one basis point sequentially but rose seven basis points year over year.
- Minor pointNonaccrual interest reversal reduced third-quarter net interest margin seven basis points and loan yield ten basis points.
- Minor pointSubordinated notes totaled $5.8 million at September 30, adding debt intended to qualify as regulatory Tier 2 capital.
- Minor pointSubordinated-debenture interest expense rose to $84,000 from $13,000 in the second quarter.
- Minor pointInvestment interest income decreased $212,000 year over year amid lower average balances and negative swap interest impacts.
- Minor pointDeposit interest expense increased $19,000, or 0.9%, sequentially.
- Minor pointCertificate-of-deposit cost increased 13 basis points sequentially to 3.23%, reflecting competitive pricing.
- Minor pointIncome tax expense increased $65,000, or 16.8%, sequentially.
- Minor pointEffective tax rate of 18.2% exceeded 17.6% sequentially but declined from 20.0% a year earlier.
AI-generated analysis. How Rhea-AI works. Not financial advice.




TACOMA, WA / ACCESS Newswire / October 29, 2026 / Commencement Bancorp, Inc. (OTCQX:CBWA) (the "Company", "we," or "us"), the parent company of Commencement Bank (the "Bank"), reported net income of
"I'm pleased with our continued momentum this quarter, marked by sustained growth in loans and stable core deposits while improving profitability on both a linked-quarter and year-over-year basis. Our disciplined approach to managing funding costs has helped us maintain a strong net interest margin over the past several quarters. The third-quarter results underscore the strength of our core business and our long-term focus on sustainable, profitable growth," said John E. Manolides, Chief Executive Officer.
"Our commercial and retail banking teams continue to capture market share by proving that agility, local underwriting autonomy, and simply talking to a real person still matter in an increasingly consolidated, digital-first banking landscape," stated Nigel L. English, President & Chief Operating Officer. "We remain focused on an intentional, long-term vision to scale our regional footprint and deepen our community and market impact. We are uniquely positioned to be the premier community banking partner for growing businesses and capture adjacent commercial lending opportunities. Our highly disciplined approach to relationship banking is directly reflected in our respectable financial results."
Balance Sheet
Total assets decreased
Federal funds sold decreased
Investment securities available for sale decreased
Loans receivable increased
Total deposits decreased
During the third quarter of 2026, the Company raised an additional
Credit Quality
The Bank had nonperforming assets of
The percentage of classified loans (loans rated Substandard or worse) to loans receivable decreased to
Liquidity
The Bank had ample liquidity with both on-and off-balance sheet sources. Total on-balance sheet liquidity of
Income Statement
Net interest income increased
Net interest margin ("NIM") decreased one bps to
Interest income on loans increased
Interest income on investments decreased
Interest expense on deposits increased
Interest expense on subordinated debentures increased
Total non-interest income increased
Total non-interest expense increased
Income tax expense increased
###
About Commencement Bancorp, Inc.
Commencement Bancorp, Inc. is the holding company for Commencement Bank, headquartered in Tacoma, Washington. Commencement Bank was formed in 2006 to provide traditional, reliable, and sustainable banking in Pierce, King, Kitsap, and Thurston counties and the surrounding areas. Their team of experienced banking experts focuses on personal attention, flexible service, and building strong relationships with customers through state-of-the-art technology as well as traditional delivery systems. As a local bank, Commencement Bank is deeply committed to the community. For more information, please visit www.commencementbank.com. For information related to the trading of CBWA, please visit www.otcmarkets.com.
For further discussion, please contact the following:
John E. Manolides, Chief Executive Officer | 253-284-1802
Nigel L. English, President & Chief Operating Officer | 253-284-1801
Brandi Parker, Executive Vice President & Chief Financial Officer | 253-284-1803
Forward-Looking Statement Safe Harbor: This news release contains comments or information that constitutes forward-looking statements (within the meaning of the Private Securities Litigation Reform Act of 1995) that are based on current expectations that involve a number of risks and uncertainties. Forward-looking statements describe Commencement Bancorp, Inc.'s projections, estimates, plans and expectations of future results and can be identified by words such as "believe," "intend," "estimate," "likely," "anticipate," "expect," "looking forward," and other similar expressions. They are not guarantees of future performance. Actual results may differ materially from the results expressed in these forward-looking statements, which because of their forward-looking nature, are difficult to predict. Investors should not place undue reliance on any forward-looking statement, and should consider factors that might cause differences including but not limited to the degree of competition by traditional and nontraditional competitors, declines in real estate markets, an increase in unemployment or sustained high levels of unemployment; changes in interest rates; greater than expected costs to integrate acquisitions, adverse changes in local, national and international economies; changes in the Federal Reserve's actions that affect monetary and fiscal policies; changes in legislative or regulatory actions or reform, including without limitation, the Dodd-Frank Wall Street Reform and Consumer Protection Act; demand for products and services; changes to the quality of the loan portfolio and our ability to succeed in our problem-asset resolution efforts; the impact of technological advances; changes in tax laws; and other risk factors. Commencement Bancorp, Inc. undertakes no obligation to publicly update or clarify any forward-looking statement to reflect the impact of events or circumstances that may arise after the date of this release.
SOURCE: Commencement Bank
View the original press release on ACCESS Newswire
FAQ
AI-generated questions and answers. How Rhea-AI works. Not financial advice.
What were Commencement Bancorp's third-quarter 2026 earnings?
Commencement Bancorp earned $2.0 million, or $0.55 per share, in the third quarter of 2026. That compares with $1.8 million, or $0.48 per share, in the second quarter and $1.9 million, or $0.49 per share, in the third quarter of 2025.
Why did Commencement Bancorp's nonperforming assets increase in the third quarter of 2026?
The increase followed two credit relationships being classified as nonaccrual. Nonperforming assets reached $1.8 million, or 0.25% of total assets, at September 30, compared with $488,000, or 0.07%, at June 30.
What liquidity sources did Commencement Bank have at September 30, 2026?
Commencement Bank had $109.8 million of on-balance-sheet liquidity, or 15.3% of total assets, and access to $237.7 million through available borrowing sources. On-balance-sheet liquidity included unencumbered cash, cash equivalents and investment securities available for sale. Borrowing sources included Federal Home Loan Bank advances, the Federal Reserve discount window and correspondent-bank federal funds lines.
What was Commencement Bank's credit-loss allowance ratio at September 30, 2026?
The allowance for credit losses was 1.18% of loans receivable at September 30, unchanged from June 30. The bank recorded a $141,000 credit-loss provision during the third quarter, including a $16,000 reversal of provision for unfunded credit losses.