
CreditRiskMonitor Announces Third Quarter Results
Sentiment and the balance of points
Rhea-AI Sentiment reads the wording of the document, how positive or negative its language is on a 1 to 5 scale. The balance of points shown with the takes weighs what the document actually discloses, so the two can disagree, for example when a trial that missed its main goal is described in upbeat language.
Rhea-AI Summary
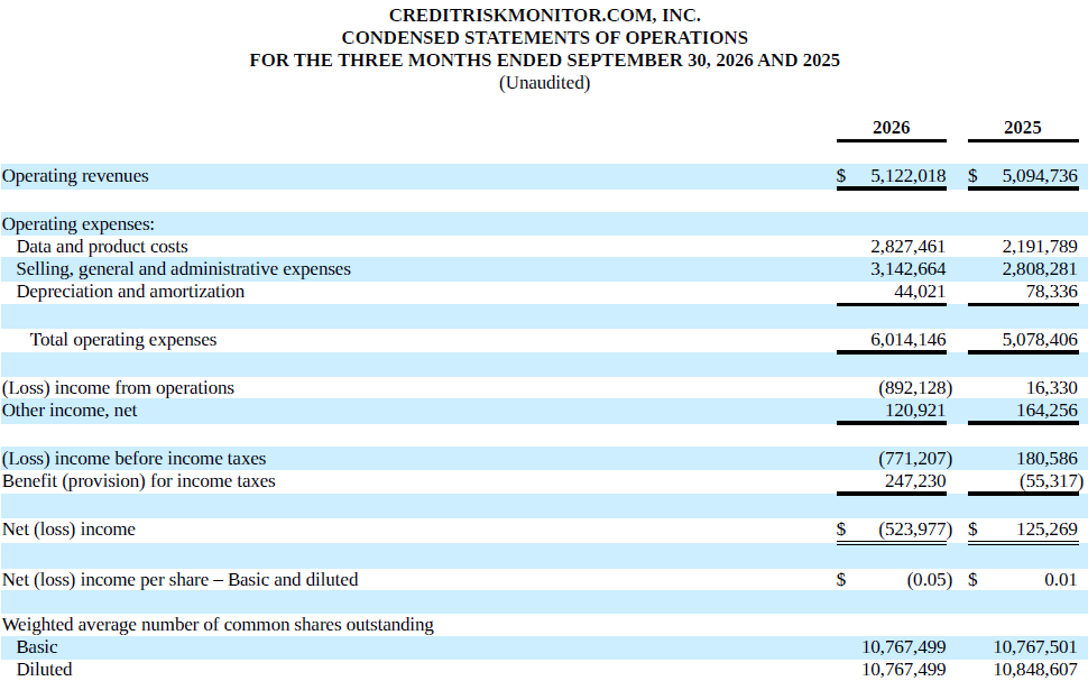
CreditRiskMonitor.com (CRMZ) reported third-quarter fiscal 2026 revenue of $5.1 million, up approximately 1% from the same quarter of fiscal 2025. Operating results swung to an approximately $892 thousand loss from approximately $16 thousand in income. Net results moved to an approximately $524 thousand loss from approximately $125 thousand in income.
Higher expenses reflected added senior technology leadership and non-recurring professional services for transformation and restatement initiatives. The company expects operating expenses to decline as restatement and voluntary tax disclosure work winds down. It continues closing agreements addressing sales and income tax liabilities and implementing remediation of a material weakness in financial reporting controls. Management reports incremental improvement in customer retention and anticipates SOC 2 Type II certification in the coming weeks.
How this balance works
Rhea-AI gives every point it takes from this document a weight. Minor counts 1, Moderate 3 and Major 9, so one Major point outweighs several Minor ones. The bar adds up the weights on each side, and when neither side holds more than 65% of the total the balance reads Mixed.
It reads the document as published, with the same rules for every company, and it does not look at what the market expected or at how the stock traded, so a point can be objectively good on a day the stock falls.
Rhea-AI Sentiment measures something else, the tone of the wording.
Hollow bars mark forward-looking points. How the balance works
Positive
- Minor pointRevenue of $5.1 million increased approximately 1% in third-quarter fiscal 2026 versus the same fiscal 2025 period.
- Minor point. Forward-looking: it has not happened yet and may not happen.Operating expenses are expected to decline as professional fees tied to restatement and voluntary disclosure work wind down.
- Minor pointVoluntary Disclosure Agreements continue closing to address sales and income tax liabilities.
- Minor pointCustomer retention is improving incrementally under the Customer Success plan, management reports.
- Minor point. Forward-looking: it has not happened yet and may not happen.SOC 2 Type II certification is anticipated in the coming weeks.
2 minor points
- Minor point. Forward-looking: it has not happened yet and may not happen.Trade data contribution is expected to increase through easier ERP connectivity and deeper data security assurances.
- Minor pointAI and automation are delivering cost and capacity benefits, management reports.
Negative
- Major pointMaterial weakness in financial reporting controls remains under remediation, with control effectiveness still being monitored.
- Moderate pointOperating loss of approximately $892 thousand versus approximately $16 thousand operating income in third-quarter fiscal 2025.
- Minor pointNet loss of approximately $524 thousand versus approximately $125 thousand net income in third-quarter fiscal 2025.
- Minor pointHigher expenses reflected added senior technology leadership and non-recurring professional services for transformation and restatement initiatives.
- Minor pointSales and income tax liabilities remain subject to ongoing voluntary disclosure work.
AI-generated analysis. How Rhea-AI works. Not financial advice.


TARRYTOWN, NY / ACCESS Newswire / November 12, 2026 / CreditRiskMonitor.com, Inc. (OTCQX:CRMZ) reported revenues of
The Company continues to make progress in closing Voluntary Disclosure Agreements (VDAs) to address its sales and income tax liability. The Company also continues implementing its remediation plan and believes it is taking the necessary steps to address the material weakness in internal control over financial reporting, with meaningful progress made with its independent third-party provider of automated tax solutions. The Company is monitoring the effectiveness of these steps while making appropriate adjustments to fully address the material weakness.
Mike Flum, CEO, said, "Resolving our sales and income tax matter remains a top priority, and we are making real progress. Each VDA we close takes a piece of this off the table, and automating the underlying tax work gives us controls that are more systematic and repeatable. We will keep testing those controls and adjusting until the material weakness is closed for good. Operating expenses are expected to decline as the professional fees tied to our restatement and VDA work wind down.
On the macroeconomic front, U.S. Courts data shows combined U.S. business Chapter 11 and Chapter 7 bankruptcy filings rose
Internally, retention is improving incrementally under the Customer Success plan, and growing interest in our new integrated workflow and supply chain solutions bodes well for more stickiness. New playbooks and support agent initiatives should improve the value we deliver, the cost to serve, and our responsiveness. We expect increased trade data contribution, thanks to easier connectivity from our new ERP integrations and deeper data security assurances under our SOC 2 Type II certification, which we anticipate in the coming weeks. Trade contribution is a focus and key to our growth. Participating subscribers renew at higher rates than non-contributors and prospects who trial with trade data close at higher rates than other trials. To complete the flywheel, the additional contributed data enhances our coverage, improving value for all subscribers and prospects.
At the end of October, we attended credit and sourcing conferences where we saw real interest in our workflow initiatives and MCP product. The sourcing event also confirmed that continuous monitoring of supplier financial risk resonates with sourcing leaders, and frequently updated analytics that provide accurate, forward-looking predictions are a differentiator. A recent webinar with one of our Fortune 500 Europe clients cemented this point by focusing on how its Procurement team uses our Confidential Financial Statements Solution with SupplyChainMonitor™ to continuously monitor its strategic private suppliers, complementing our FRISK® and PAYCE® coverage of public and large private companies worldwide.
We are also finding real cost and capacity unlocks from AI and automation across Quality Assurance, Engineering, Product, Data Science, Marketing, and Revenue, and the pace is accelerating. We keep moving workflows into production while improving the ones already running, and AI-assisted coding is now part of everyday development. As our teams become more fluent with the tools, we expect higher quality at lower unit costs.
Finally, we are starting to see benefits from the restructuring of our Engineering team, with several longer-term roadmap items targeted for release at the end of January. We are most excited about our MCP Beta with plugins for Claude, ChatGPT, and Copilot; a rebuilt, enterprise-grade API with webhooks and a developer portal; a News mobile app for iOS and Android with a personalized credit news feed, portfolio view, AI summaries, and push alerts; improved Credit Limit Ranges alongside a major update to our Credit Limit Service that uses our bankruptcy analytics to deliver frictionless, customized, and accurate limit recommendations; and platform UI updates, including admin user management for subscribers and a modernized CreditRiskMonitor® interface. As always, we remain committed to reinvesting in the business to deliver subscription services whose value exceeds their cost."
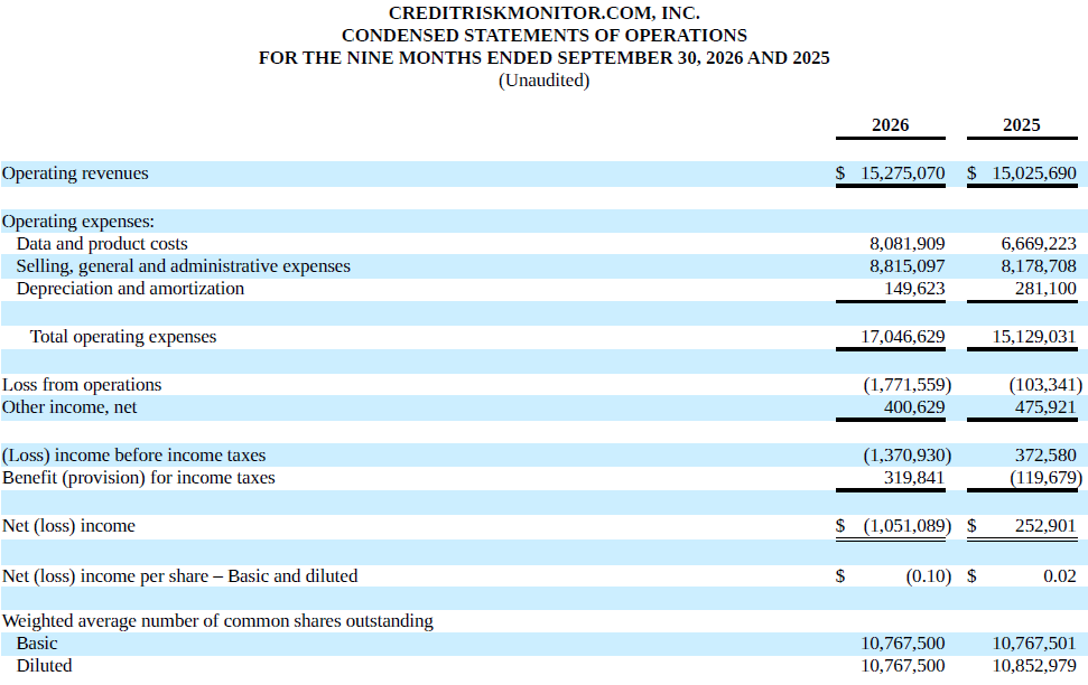
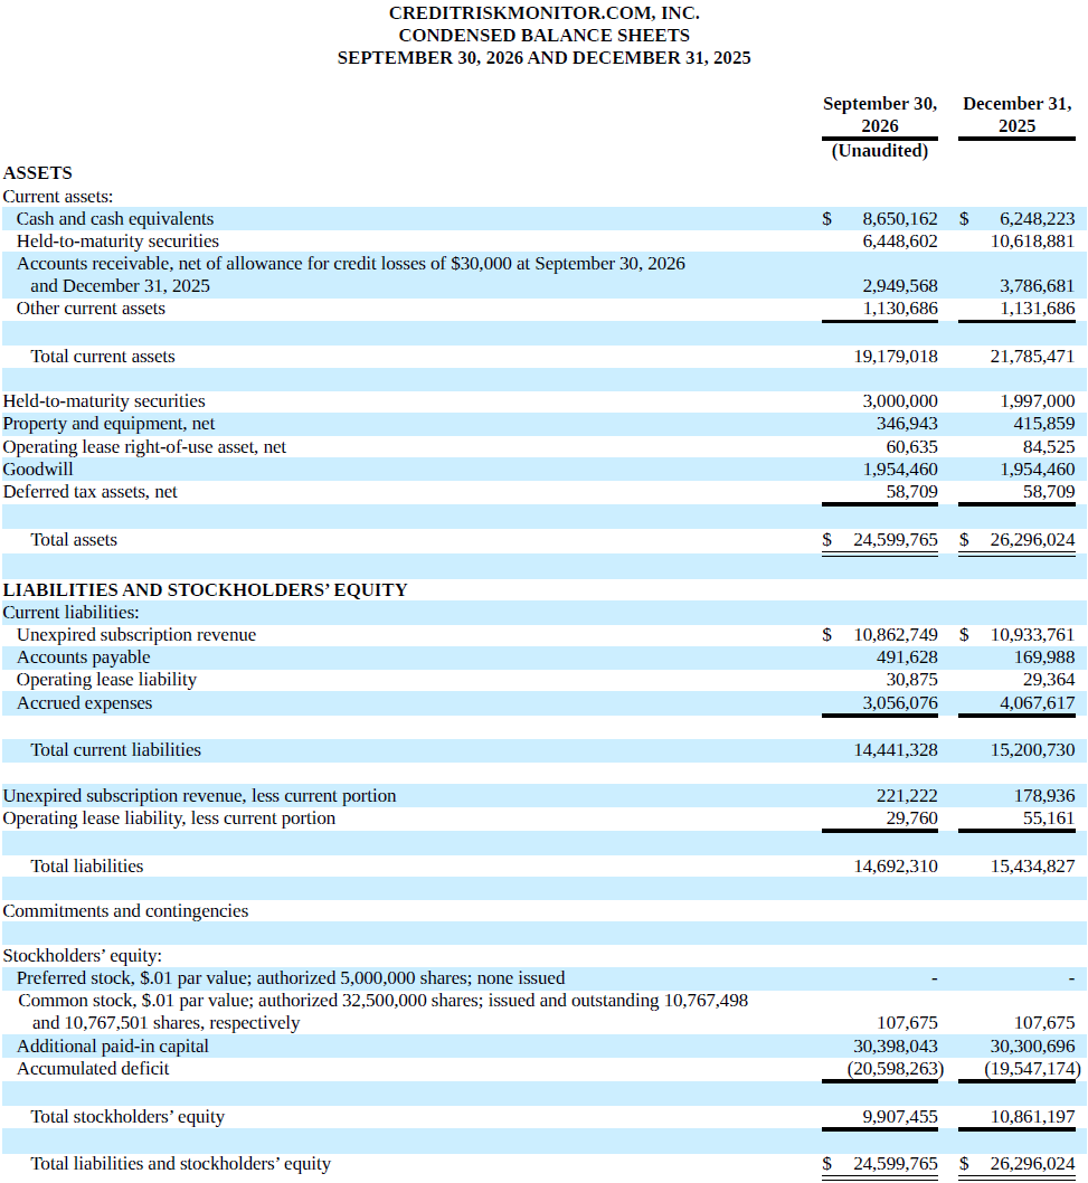
A full copy of the financial statements can be found at https://crmz.ir.edgar-online.com/
Overview
CreditRiskMonitor.com, Inc. (creditriskmonitor.com) sells a suite of web-based, SaaS subscription products providing access to comprehensive commercial credit reports, bankruptcy risk analytics, financial and payment information, and curated news on public and private companies worldwide. Our primary SaaS subscription products for analyzing commercial financial risk are CreditRiskMonitor® and SupplyChainMonitor™. These products help corporate credit and procurement professionals stay ahead of and manage financial risk more quickly, accurately, and cost-effectively. Our subscribers include nearly
To help subscribers prioritize and monitor counterparty financial risk, our SaaS platforms offer the proprietary FRISK® and PAYCE® Scores as well as the FAST Rating, the well-known Altman Z"-Score, agency ratings from key Nationally Recognized Statistical Rating Organizations ("NRSROs"), curated news, and detailed financial spreads & ratios. Our FRISK® and PAYCE® Scores are financial distress classification models that measure a business's probability of bankruptcy within a year. The FRISK® score also includes a risk signal based on the aggregate research behaviors of our subscribers, who control counterparty access to trade credit at some of the most sophisticated companies in the world. The inclusion of this risk signal boosts the overall accuracy of this bankruptcy analytic by lowering the false positive rate for the riskiest corporations.
Through its Trade Contributor Program, the Company receives monthly confidential accounts receivables data from hundreds of subscribers and non-subscribers, which it parses, processes, aggregates, and reports to summarize the invoice payment behavior of B2B counterparties without disclosing the specific contributors of this information. The size of the Trade Contributor Program's current annualized trade credit transaction data is approximately
Safe Harbor Statement
Certain statements in this press release, including statements prefaced by the words "anticipates", "estimates", "believes", "expects" or words of similar meaning, constitute "forward-looking statements" within the meaning of the Private Securities Litigation Reform Act of 1995. Forward-looking statements include details of the remediation of the related material weakness in internal control over financial reporting; the timing and terms of VDAs and the amount of Company's sales and income tax liability; the expected timing of SOC 2 Type II certification and product releases; expected levels of client data contribution, retention, and sales; expected benefits from AI and automation; and views on macroeconomic and market conditions. Such forward-looking statements involve known and unknown risks, uncertainties and other factors which may cause the actual results, performance, expectations or achievements of the Company to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements, including, among others, those risks, uncertainties and factors referenced from time to time as "risk factors" or otherwise in the Company's Registration Statements or Securities and Exchange Commission Reports. There can be no assurance that (i) the Company will be able to promptly and efficiently implement the appropriate remediation steps into its financial reporting and (ii) the Company will achieve the timeliness, cost reductions, and other benefits described above. We disclaim any intention or obligation to revise any forward-looking statements, whether as a result of new information, a future event, or otherwise.
CONTACT:
CreditRiskMonitor.com, Inc.
Mike Flum, Chief Executive Officer
(845) 230-3037
ir@creditriskmonitor.com
SOURCE: CreditRiskMonitor.com, Inc.
View the original press release on ACCESS Newswire
FAQ
AI-generated questions and answers. How Rhea-AI works. Not financial advice.
What were CreditRiskMonitor's third-quarter fiscal 2026 results?
CreditRiskMonitor reported $5.1 million in revenue, an increase of approximately 1% from third-quarter fiscal 2025. Operating loss was approximately $892 thousand, compared with operating income of approximately $16 thousand. Net loss was approximately $524 thousand, compared with net income of approximately $125 thousand.
Why does CreditRiskMonitor expect operating expenses to decline?
CreditRiskMonitor expects operating expenses to decline as professional fees associated with its restatement and Voluntary Disclosure Agreement work wind down. Third-quarter expenses included non-recurring professional services for transformation and restatement initiatives, alongside costs for added senior technology leadership.
Why is CreditRiskMonitor focusing on trade data contributions?
CreditRiskMonitor identifies trade data contribution as a growth focus because participating subscribers renew at higher rates than non-contributors, and prospects trialing with trade data close at higher rates than other trials. The company says additional contributed data also expands coverage and improves value for subscribers and prospects.