
Spartan Metals Announces US$2.14 Billion After Tax NPV8 and 30.9% IRR for Victorio Tungsten-Molybdenum Project PEA
Sentiment and the balance of points
Rhea-AI Sentiment reads the wording of the document, how positive or negative its language is on a 1 to 5 scale. The balance of points shown with the takes weighs what the document actually discloses, so the two can disagree, for example when a trial that missed its main goal is described in upbeat language.
Rhea-AI Summary
Spartan Metals (SPRMF) reported a preliminary assessment of its Victorio tungsten-molybdenum project in New Mexico, estimating an after-tax net present value of US$2.14 billion. The base case uses an 8% discount rate and models a 30.9% after-tax internal rate of return for a 24-year underground operation. It estimates US$683.0 million in initial capital and an after-tax payback of approximately 3.2 years from the start of operations, after three years of construction.
A higher-price scenario lifts modeled after-tax net present value to US$4.02 billion and the return to 43.3%. The estimates cover the whole project before financing costs. Spartan's ownership remains subject to completing its option terms, and 39% of scheduled plant feed is inferred material, the least certain resource category. Spartan plans to advance toward prefeasibility through a work program estimated at US$13.2 million.
How this balance works
Rhea-AI gives every point it takes from this document a weight. Minor counts 1, Moderate 3 and Major 9, so one Major point outweighs several Minor ones. The bar adds up the weights on each side, and when neither side holds more than 65% of the total the balance reads Mixed.
It reads the document as published, with the same rules for every company, and it does not look at what the market expected or at how the stock traded, so a point can be objectively good on a day the stock falls.
Rhea-AI Sentiment measures something else, the tone of the wording.
Hollow bars mark forward-looking points. How the balance works
Positive
- Major point. Forward-looking: it has not happened yet and may not happen.Base-case economics model US$2.14 billion in after-tax net present value at an 8% discount rate and a 30.9% after-tax internal rate of return
- Minor point. Forward-looking: it has not happened yet and may not happen.Life-of-mine after-tax free cash flow is modeled at US$6.9 billion, undiscounted and before financing costs
- Minor point. Forward-looking: it has not happened yet and may not happen.Life-of-mine net revenue is estimated at US$16.62 billion after modeled freight and royalty deductions
- Minor point. Forward-looking: it has not happened yet and may not happen.Operating margin is modeled at 73.8% before capital expenditures and taxes
- Minor point. Forward-looking: it has not happened yet and may not happen.After-tax payback is modeled at approximately 3.2 years from the start of operations
6 minor points
- Minor point. Forward-looking: it has not happened yet and may not happen.Higher-price scenario models US$4.02 billion in after-tax net present value at an 8% discount rate and a 43.3% after-tax internal rate of return at US$2,000 per tungsten trioxide unit and US$25 per pound of molybdenum
- Minor point. Forward-looking: it has not happened yet and may not happen.Conceptual underground mine would operate for 24 years, with plant design capacity of 25,000 short tons per day
- Minor point. Forward-looking: it has not happened yet and may not happen.Modeled tungsten output is 217.75 million pounds of contained tungsten trioxide after processing over the mine life
- Minor point. Forward-looking: it has not happened yet and may not happen.Modeled molybdenum output is 207.63 million pounds recovered over the mine life
- Minor point. Forward-looking: it has not happened yet and may not happen.Prefeasibility work is planned to refine the resource, mine design and processing assumptions
- Minor point. Forward-looking: it has not happened yet and may not happen.Potential fluorspar and beryllium by-products are slated for evaluation in future studies
Negative
- Major point. Forward-looking: it has not happened yet and may not happen.Initial capital is estimated at US$683.0 million, with a modeled three-year construction period 48× market cap
- Moderate pointProject ownership remains contingent on Spartan completing the terms of its option to acquire Victorio
- Moderate pointDevelopment requires financing, permitting and further technical and environmental work before a decision can be made
- Moderate pointInferred resources account for 39% of scheduled plant feed in the preliminary assessment
- Moderate point. Forward-looking: it has not happened yet and may not happen.Recommended prefeasibility work program is estimated to cost US$13.2 million 93% of market cap
5 minor points
- Minor point. Forward-looking: it has not happened yet and may not happen.Sustaining capital is estimated at US$2.03 billion over the operating life
- Minor point. Forward-looking: it has not happened yet and may not happen.Life-of-mine operating costs are modeled at US$4,355.3 million
- Minor pointCapital and operating cost estimates have stated accuracy of plus or minus 50%
- Minor point. Forward-looking: it has not happened yet and may not happen.Lowest metal-price scenario tested reduces modeled after-tax net present value to US$392.1 million at an 8% discount rate and after-tax internal rate of return to 14.0%
- Minor pointMetallurgical recoveries still require confirmation through testing on representative material
AI-generated analysis. How Rhea-AI works. Not financial advice.


- Base case outlines a 24-year, 25,000 short ton per day nameplate processing capacity U.S. tungsten-molybdenum operation with initial capital of US
$683.0 million and a 3.2-year payback (Figure 1) - Strongly leveraged to metal prices with after-tax US
$ 4.02 billion NPV8 and an IRR of43.3% at US$2,000 WO3 and US$25 molybdenum. Recent market reference prices as of November 13, 2026 were US$2,650 /mtu WO3 and US$34.23 /lb Mo.1, 2, 3 - Life-of-mine production of approximately 217.8 million pounds WO3 in APT (~9.07 million pounds annually) and 207.6 million pounds molybdenum in concentrate (~8.65 million pounds annually)
- Potential for long-term domestic sourcing initiatives for tungsten and molybdenum
The PEA is preliminary in nature, that it includes Inferred Mineral Resources that are considered too speculative geologically to have the economic considerations applied to them that would enable them to be categorized as Mineral Reserves, and there is no certainty that the PEA will be realized. Mineral Resources that are not Mineral Reserves do not have demonstrated economic viability.
Vancouver, British Columbia--(Newsfile Corp. - November 19, 2026) - Spartan Metals Corp. (TSXV: W) (OTCQB: SPRMF) (FSE: J03) ("Spartan" or the "Company") is pleased to announce the positive results of a Preliminary Economic Assessment ("PEA") for its Victorio Tungsten-Molybdenum Project ("Victorio" or the "Project") in Luna County, New Mexico. SRK Consulting ("SRK") led preparation of the PEA, with Teal CPG, Inc. ("Teal") contributing the previously announced mineral resource estimate (see news release October 22, 2026). The PEA has an effective date of September 21, 2026. All monetary amounts are in U.S. dollars unless otherwise stated. A technical report prepared in accordance with National Instrument 43-101 Standards of Disclosure for Mineral Projects ("NI 43-101") will be filed on SEDAR+ (www.sedarplus.ca) and on the Company's website within 45 days of this news release.
Brett Marsh, Spartan's President and CEO comments, "We are thrilled about the opportunity this PEA outlines for the Victorio Project. Using realistic, long-term metals prices of US
Mr. Marsh continues, "We're looking at a potential 24-year operation, with modelled cumulative, undiscounted after-tax free cash flow of US
Mr. Marsh concludes, "Having this opportunity in New Mexico is significant as it's a solid mining jurisdiction with excellent infrastructure in the vicinity of the Project. Victorio, which is supported by the results of this PEA, could become a lasting domestic source of tungsten and molybdenum for U.S. industrial and defense customers. This is a major milestone for Spartan, and we're eager to advance the technical work, permitting, financing and product qualification required to move the Victorio project forward."
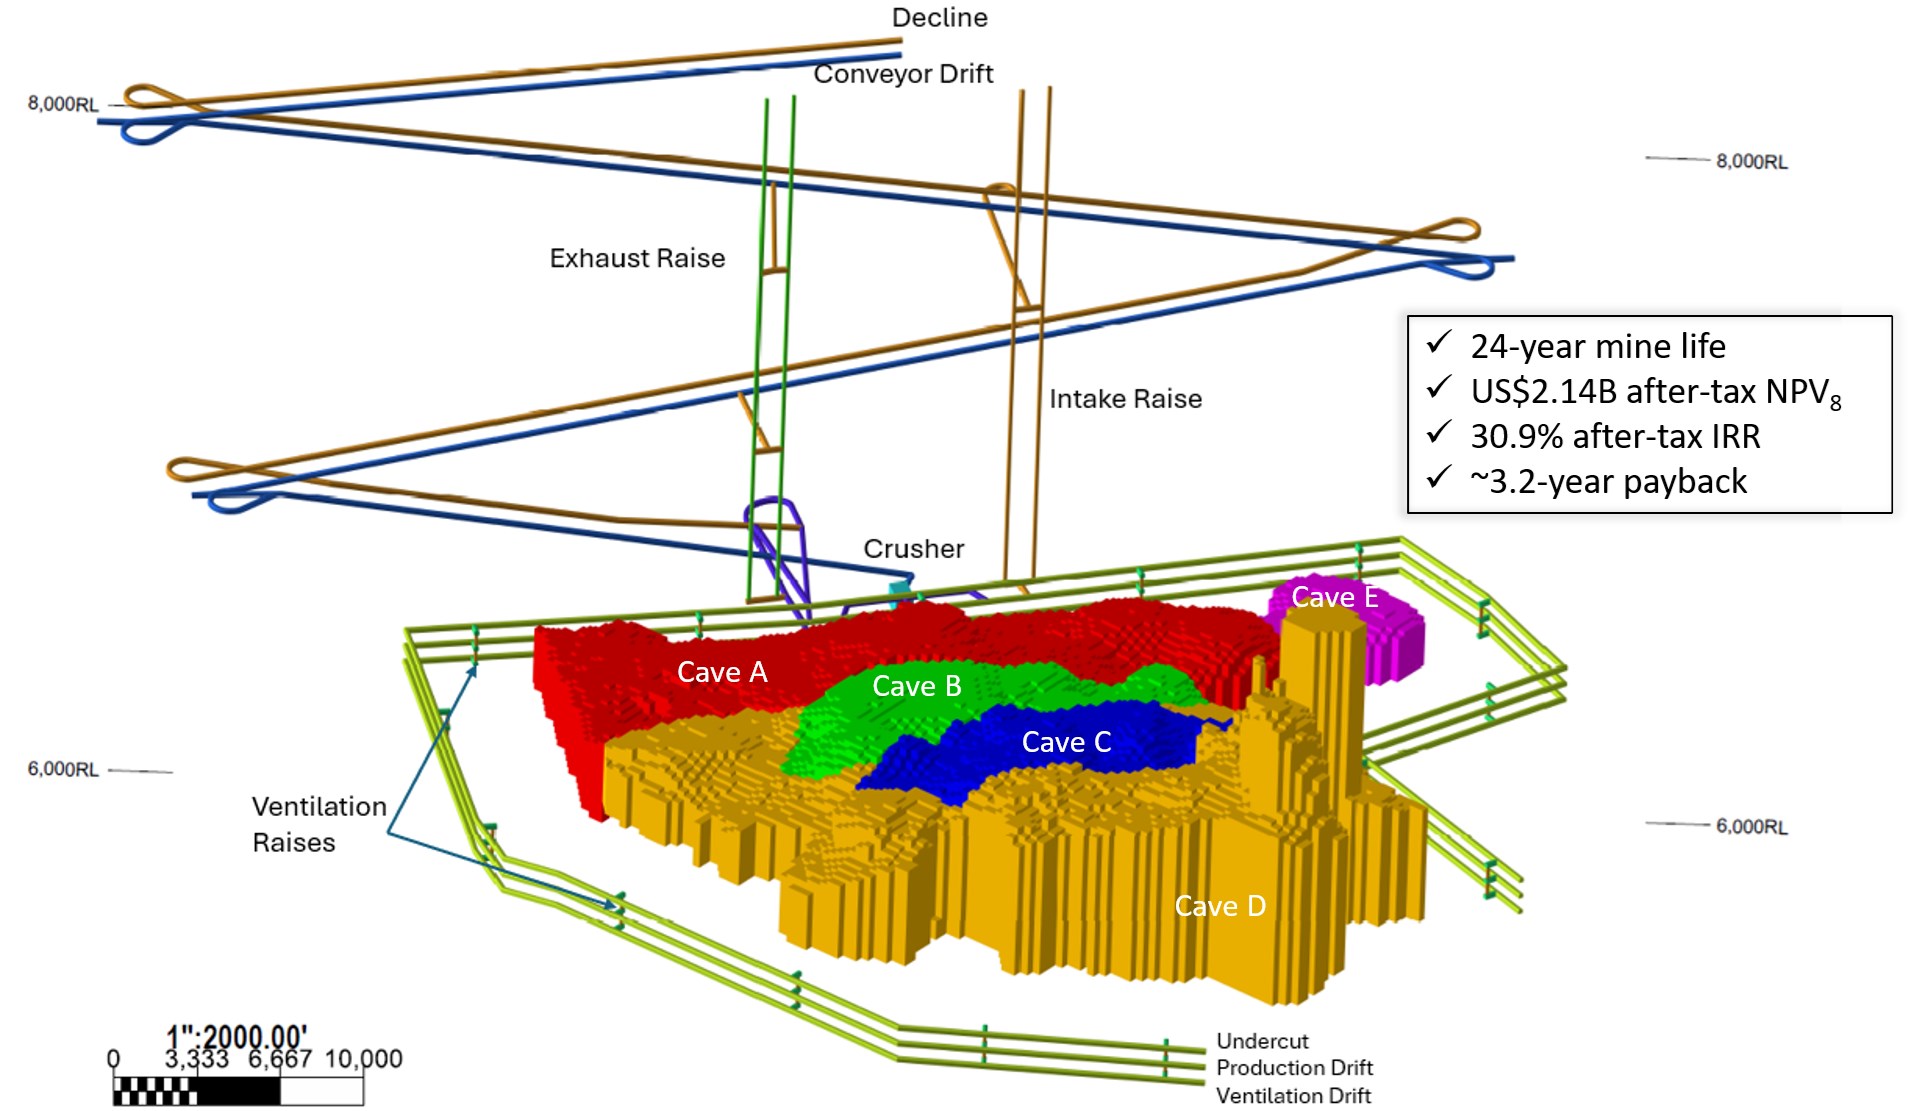
Figure 1: Orthogonal view of the Victorio development design looking northwest with key summary parameters. Caves A and B represent approximately the first 10 years of planned production.
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/12484/324692_a9675c52344ceb87_001full.jpg
Next Steps and Development Considerations
Advancing Victorio toward a development decision will require further resource evaluation, mine design, metallurgical testing, engineering, environmental studies and permitting, together with financing. Areas requiring further assessment include underground ground conditions, water supply, tailings design, product quality and commercial terms, and the timing and cost of sustaining development.
Spartan intends to address the PEA recommendations and advance the project to a Prefeasibility Study ("PFS") level Study through the following work program:
Table 1 Recommended work program to acquire Prefeasibility-level study inputs
| Recommended Work Program | Estimated Cost (US$) |
Geological and Resource Definition for:
| 4,500,000 |
| PFS-level underground mine design (following infill drilling and geotechnical studies) | 350,000 |
| Geotechnical data collection and studies to support mine and process plant design | 1,500,000 |
| Metallurgical test work program on representative composites to support process plant design | 300,000 |
| Surface infrastructure trade-off studies and PFS-level design | 150,000 |
| Tailings Storage Facility (TSF) field, laboratory and desk studies and PFS-Level design (incl. | 1,900,000 |
| Hydrogeologic study of mine area and basin | 1,500,000 |
| Environmental baseline studies and permitting | 3,000,000 |
| 13,200,000 |
Mineral Resource Basis
The Victorio Mineral Resource estimate was prepared by Teal CPG, Inc. and has an effective date of August 3, 2026. The estimate and its assumptions were previously disclosed in Spartan's October 22, 2026 news release, "Spartan Metals Expands Victorio Tungsten-Molybdenum Resource with Measured and Indicated Grades of
The PEA is preliminary in nature and includes Inferred Mineral Resources that are considered too speculative geologically to have the economic considerations applied to them that would enable them to be categorized as Mineral Reserves. There is no certainty that the PEA results will be realized. Mineral Resources that are not Mineral Reserves do not have demonstrated economic viability.
Economic Results and Assumptions
The economic analysis is presented on a
The base case generates estimated life-of-mine net revenue of US
Table 2 Project economic results at Base Case Price assumptions
| Metric | Before tax | After tax |
| NPV5 (US$ million) | 4,544.4 | 3,256.3 |
| NPV8 (US$ million) | 3,026.8 | 2,143.1 |
| NPV10 (US$ million) | 2,334.8 | 1,634.8 |
| Internal rate of return (%) | 35.8 | 30.9 |
| Undiscounted free cash flow (US$ million) | 9,534.9 | 6,903.4 |
The model indicates after-tax payback of approximately 3.2 years from the start of operations, following a 3-year construction period. NPV measures discounted Project cash flow at the study's valuation date.
The results of Table 2 are based on metal price assumptions as shown in Table 3.
Table 3 Base case model metal prices
| Assumption | Price1 |
| Molybdenum | US |
| Tungsten on a contained WO₃ basis | US Approximately US |
Sensitivity Analysis
The base case uses long-term planning prices of US
Table 4 Base case and higher price sensitivity
| Price case | WO₃ US$/mtu | Mo US$/lb | After tax NPV8 US$ billion | After tax IRR |
| Base case | 1,350 | 20 | 2.14 | |
| Higher price sensitivity | 2,000 | 25 | 4.02 |
One metric tonne unit (mtu) equals 10 kilograms of WO₃. WO₃ denotes tungsten trioxide. A quoted metal benchmark and the amount ultimately received for a product may differ because of product specifications, payability and commercial deductions.
The base case uses the long-term prices adopted for the PEA. The higher-price case illustrates the economic potential at prices closer to recent Western market benchmarks. The estimated NPV and IRR change as the metal price inputs change. The Project is sensitive to metal prices, and after-tax NPV remains positive across the range of lower prices tested.
Table 5 After-tax NPV8 price sensitivity in US$ million
| Mo US$/lb WO3 US$/mtu | WO₃ 750 | WO₃ 1,000 | WO₃ 1,350 | WO₃ 1,550 | WO₃ 2,000 |
| 15 | 392.1 | 1,021.1 | 1,900.2 | 2,402.5 | 3,532.5 |
| 20 | 635.6 | 1,264.2 | 2,143.1 | 2,654.4 | 3,775.5 |
| 25 | 878.9 | 1,507.1 | 2,386.1 | 2,888.3 | 4,018.4 |
| 30 | 1,122.1 | 1,750.1 | 2,629.0 | 3,131.3 | 4,261.3 |
Table 6 After-tax IRR price sensitivity
| Mo US$/lb WO3 US$/mtu | WO₃ 750 | WO₃ 1,000 | WO₃ 1,350 | WO₃ 1,550 | WO₃ 2,000 |
| 15 | |||||
| 20 | |||||
| 25 | |||||
| 30 |
Source: SRK's economic model and price-sensitivity analysis. Column headings are WO₃ prices in US$/mtu; row headings are Mo prices in US$/lb. Pink cells show the base case; blue cells show the featured higher-price sensitivity. Figures are rounded. These price scenarios are illustrations, not forecasts.
At, US
NPV8 expresses estimated future Project cash flow as a value at the study's valuation date using an
Table 7 Life of mine cash flow
| Item | US$ million |
| Net revenue | 16,619.8 |
| Operating costs | (4,355.3) |
| Operating margin before capital and taxes | 12,264.5 |
| Operating margin ratio (before capital and taxes) | |
| Initial capital | (683.0) |
| Sustaining capital | (2,031.3) |
| Severance tax | (15.3) |
| Corporate income tax | (2,631.5) |
| After-tax free cash flow | 6,903.4 |
Net revenue is after the modelled freight and royalty deductions. Operating margin is net revenue less operating costs, before capital expenditures and taxes. Cash flow is undiscounted and excludes financing costs. Figures may not sum exactly due to rounding.
Conceptual Operating Plan
The PEA evaluates an underground block cave operation feeding a molybdenum flotation circuit and an ammonium paratungstate ("APT") plant. The conceptual schedule processes approximately 199.5 million U.S. short tons over 24 operating years. Block cave mining is an underground mining method that uses gravity to help break and move large masses of rock. Tunnels are built beneath the deposit, and a supporting layer is removed to allow the rock above to break and fall to collection points. Block cave can produce large volumes of ore at relatively low operating costs, although substantial underground development is required before production begins.
An APT plant uses chemical treatments to dissolve the tungsten from concentrate, remove any potential impurities and form crystals ready for sale to end consumers. Manufacturers convert APT into tungsten metal and tungsten carbide, used in cutting tools, industrial equipment and other specialized products. Producing APT on site would place Victorio's output at a key intermediate stage of the tungsten supply chain.
Table 8 Operating assumptions and recovered output
| Parameter | PEA value |
| Mining approach | Underground block cave |
| Construction period | 3 years |
| Operating life | 24 years |
| Average mineralized material mining rate | 22,760 short tons/day |
| Total scheduled material processed | 199.5 million short tons |
| Average mill feed grade WO₃ | |
| Average mill feed grade Mo | |
| Molybdenum recovery | |
| WO₃ recovery before APT processing | |
| WO₃ recovery in APT plant | |
| Combined WO₃ recovery through both stages | |
| Life of mine recovered molybdenum | 207.63 million lb Mo |
| Average annual recovered molybdenum | 8.65 million lb Mo |
| Life of mine recovered WO₃ after APT processing | 217.75 million lb WO₃ 9.07 million mtu WO₃ |
| Average annual recovered WO₃ after APT processing | Approximately 412,000 mtu WO₃ |
Annual averages divide total recovered output by all 24 operating years, including ramp-up and later years. The planned nameplate production is 25,000 short tons per day through the process plant. Recovered metal is not the same as payable metal. WO₃ quantities are contained WO₃, not the mass of APT product. All mining and processing tonnages shown above are U.S. short tons; one short ton equals 0.90718474 metric tonnes. The mining rate is a life of mine average, not a plant nameplate capacity. Grades and production use unrounded model values.
The total scheduled processed material consists of
Capital and Operating Costs
The economic model estimates initial capital of US
Table 9 Capital Requirements
| Component | US$ million |
| Initial mining capital | 224.7 |
| Initial processing capital | 296.2 |
| Initial infrastructure capital | 162.0 |
| Total initial capital | 683.0 |
| Life of mine sustaining capital | 2,031.3 |
| Total initial and sustaining capital | 2,714.3 |
Figures may not sum exactly due to rounding.
Table 10 Operating cost estimate
| Component | Life of mine US$ million |
| Underground mining | 1,759.8 |
| Processing | 2,307.5 |
| General and administration | 288.0 |
| Total operating costs | 4,355.3 |
Total operating costs average approximately US
Metal Prices and Long-term Supply Opportunity
The PEA base case uses US
Table 11 Price cases and recent market references
| Metal | Base case | Higher price case | Recent market reference |
| Tungsten | US | US | US |
| Molybdenum | US | US | US |
The base case tungsten price is approximately
S&P Global's October 2026 report expects tungsten demand to grow approximately
Molybdenum supply comes from primary mines and as a byproduct of copper mining, tying part of its growth to copper operations and investment. Recent European tightness and expectations of constrained mine output have supported prices. These conditions provide upside exposure, while steel demand and new production can change the balance.
Major discoveries cannot be assumed to provide timely new supply: resource definition, engineering, permitting, construction and product qualification can take many years. The limited pool of advanced domestic tungsten supply options makes the development pipeline particularly relevant to U.S. defense sourcing. From January 1, 2027, DFARS 252.225-7052 extends covered-country restrictions for specified tungsten products back through the ore and feedstock stages, subject to its exceptions, which can impact U.S. demand.
Victorio's New Mexico location and 24-year operating concept position it as a potential long-term domestic source of tungsten and an additional source of molybdenum alongside existing U.S. production. This could support industrial and defense supply diversification if the Project is advanced successfully. Development remains subject to further technical studies, permitting and financing. Supplying defense customers would also require appropriate product quality, traceability and downstream qualifications.
References
1 Fastmarkets, 2026, Tungsten Market - Long Term Assessment - August 2026, report commissioned by Spartan Metals
2 Fastmarkets, November 13, 2026 Tungsten APT
3 https://www.lme.com/metals/ev/lme-molybdenum-platts#Intraday+data November 13, 2026
Qualified Persons
Brett Marsh, CPG, Spartan's President and CEO, is a qualified person as defined by NI 43-101 and has reviewed and approved the scientific and technical information in this news release. Mr. Marsh is not independent of Spartan. The independent qualified persons listed below have reviewed and approved the scientific and technical information in this news release relating to their respective areas of responsibility:
| Independent QP | Firm | Responsibilities |
| Anton Chan, P.Eng. | SRK | Mine design, production schedule and infrastructure |
| Bruno Serra | SRK | Mineral Economics |
| Eric Olin, SME-RM, MAusIMM | SRK | Metallurgy |
| Katie Bertrando, SME-RM | SRK | Environmental |
| Terry Braun, PE | SRK | Civil Engineering, TSF |
| Lewis Teal, CPG | Teal CPG, Inc. | Geology, deposit type, exploration, drilling, sample preparation and analysis |
| Rita M. Teal, PhD, CPG | Teal CPG, Inc. | Mineral Resource Estimation |
About Spartan Metals Corp.
Spartan Metals Corp. is focused on advancing critical minerals projects in established mining jurisdictions in the western United States, with an emphasis on tungsten, molybdenum and associated strategic minerals. Spartan holds an option to earn a
Victorio is an advanced-stage tungsten-molybdenum project located approximately 45 kilometres west of Deming in Luna County, New Mexico. The Project comprises 222 unpatented lode claims covering approximately 15.8 km², with beryllium and fluorspar present as additional critical minerals.
On behalf of the Board of Spartan
"Brett Marsh"
President, CEO & Director
Further Information:
Brett Marsh, M.Sc., MBA, CPG | President, CEO & Director | 1-888-535-0325 | info@spartanmetals.com
Jeff Walker | VP, The Howard Group | 403-221-0915 | jeff@howardgroupinc.com
Neither the TSX Venture Exchange nor its Regulation Service Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this press release
Forward-Looking Statements
This news release contains statements that are not historical facts. Such statements constitute "forward-looking information" within the meaning of Canadian securities legislation. Forward-looking information includes, but is not limited to, statements concerning the opportunities for the Victorio Project, and all other statements that are not historical in nature. Forward-looking information is generally, but not always, identified by the words "expects," "plans," "anticipates," "believes," "intends," "estimates," "projects," "potential" and similar expressions, or that events or conditions "will," "would," "may," "could" or "should" occur. Forward-looking information involves known and unknown risks, uncertainties and other factors that may cause the Company's actual results, performance or achievements, or developments in the industry to differ materially from the anticipated results, performance or achievements expressed or implied by such forward-looking information.
Although the Company believes the forward-looking information contained in this news release is reasonable based on information available on the date hereof, by their nature forward-looking information involves known and unknown risks, uncertainties and other factors which may cause our actual results, performance or achievements, or other future events, to be materially different from any future results, performance or achievements expressed or implied by such forward-looking information. By their nature, these statements involve a variety of assumptions, known and unknown risks and uncertainties and other factors, which may cause actual results, levels of activity and achievements to differ materially from those expressed or implied by such statements. Forward-looking statements in this news release include, but are not limited to, specific results of the PEA such as, NPV, IRR, payback period, metal prices; conversion of Inferred Mineral Resources; permitting; and timing or success of future studies.
Examples of such assumptions, risks and uncertainties include, without limitation, assumptions, risks and uncertainties associated with general economic conditions; market prices for tungsten and molybdenum, adverse industry events; future legislative, regulatory, policy and executive action developments, changes in government procurement policy or defense spending; the Company's ability to access sufficient capital from internal and external sources, and/or inability to access sufficient capital on favorable terms; the ability of the Company to implement its business strategies; competition; the ability of the Company to obtain and retain all applicable regulatory and other approvals and other assumptions, risks and uncertainties.
THE FORWARD-LOOKING INFORMATION CONTAINED IN THIS NEWS RELEASE REPRESENTS THE EXPECTATIONS OF THE COMPANY AS OF THE DATE OF THIS NEWS RELEASE AND, ACCORDINGLY, IS SUBJECT TO CHANGE AFTER SUCH DATE. READERS SHOULD NOT PLACE UNDUE IMPORTANCE ON FORWARD-LOOKING INFORMATION AND SHOULD NOT RELY UPON THIS INFORMATION AS OF ANY OTHER DATE. WHILE THE COMPANY MAY ELECT TO, IT DOES NOT UNDERTAKE TO UPDATE THIS INFORMATION AT ANY PARTICULAR TIME EXCEPT AS REQUIRED IN ACCORDANCE WITH APPLICABLE LAWS.
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/324692
FAQ
AI-generated questions and answers. How Rhea-AI works. Not financial advice.